A reader asks, “I have a question regarding Taxation on withdrawal of SIP mutual fund units. Can you throw some light on how the units would be taxed?”
First, it must be understood that the SIP is just an automated way of buying mutual funds units each month (typically). However you buy mutual fund units – via SIP or lump sum at arbitrary intervals, the taxation rule is the same.
The only difference concerns the type of fund: equity or non-equity (debt funds, gold funds, international funds and all fund of funds).
Now let us consider a schedule of mutual fund transactions. All of these except the last entry represent purchases. We have used our Google sheets MF and stock tracker to generate this instantly.
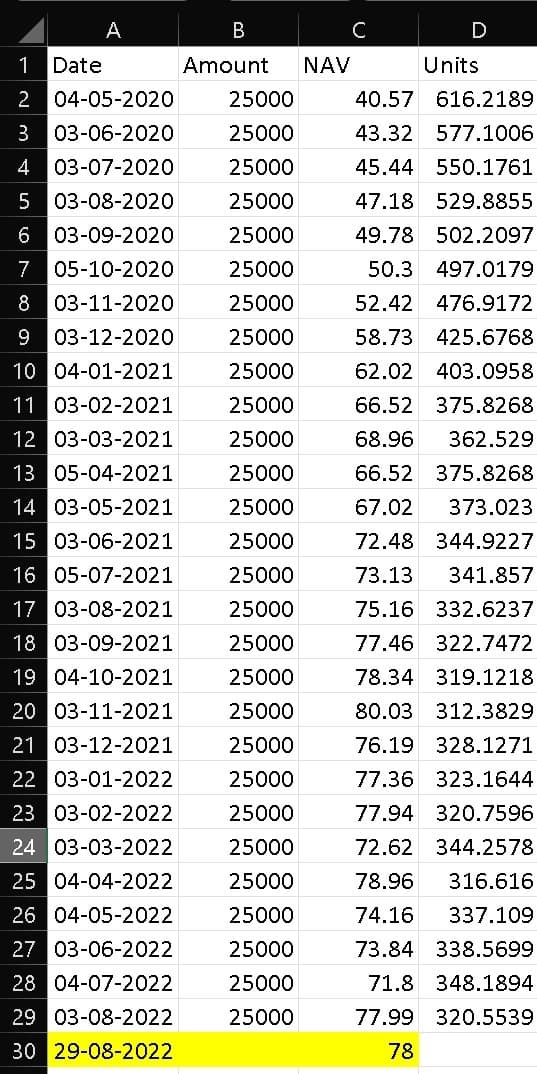
The last line in yellow represents the redemption date with a NAV of Rs. 78 per unit. Now, suppose we redeem Rs. 3 lakhs. We need to find out how many units will be redeemed. We also need to find the age of such units. In this example, we will assume all units are older than one year. So we shall only consider long-term capital gains tax of equity funds.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
This is easy: 300000/78 = 3846.1538 units (technically, NAV is declared up to 4 digits, so the units also should be rounded off to four digits, but most NAV portals only report up to 2 digits).
The next step is to determine which units will be redeemed. The rule is first-in, first-out. That is, units invested first will be redeemed first. This is easier said than done in a SIP or in any situation with multiple transactions.
In the image, column E (cell E2) represents the units’ current value in column D’s corresponding rows (cell D2). For example, 616.2189 units purchased on 4-5-2020 have a current value (date of redemption) of 616.2189 x 78 = Rs. 48,065.07271. This is well below the total redemption amount of Rs. 3 lakhs.
So we keep going. E3, E4, E5, etc., while also noting their sum.
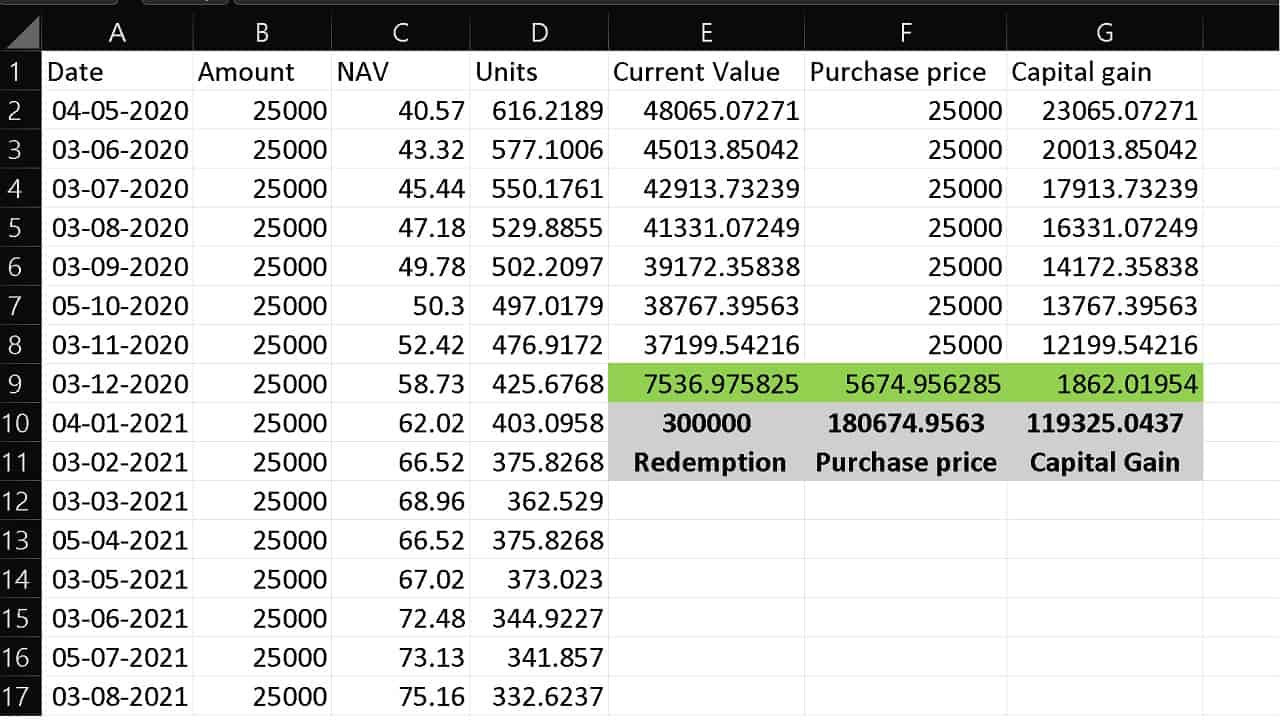
The sum of cells E2 to E8 is Rs. 292463.0242. So all the units corresponding to the first seven purchases (cells D2 to D8) will be redeemed.
Since the total redemption amount is Rs. 3 lakhs, only units currently worth 300000 – 292463.0242 = Rs. 7536.9758 will be redeemed. This is shown in cell E9 (highlighted in green).
Using the current NAV of Rs. 78, we find that this corresponds to 96.6279 units purchased on 3-12-2020 (row 9). The NAV on this date is Rs. 58.73 per unit.
The purchase price of these units = 96.6279 x 58.73 = Rs. 5674.9563.
Now we pay tax on the capital gain. Capital gain = current price minus purchase price.
We shall assume the fund is an equity fund. In the case of a non-equity fund, the purchase price will have to be modified using the cost inflation index. This is illustrated here: Taxation of international mutual funds explained with an example.
Some units were purchased at a NAV of Rs. 40.57 per unit and some at a NAV of Rs. 43.32 per unit etc. Therefore the capital gain will have to be accounted for with the correct purchase price. Column G in the image above = Column E minus Column F (corresponding rows).
- The sum of the current value of the units redeemed: Rs. 3,00,000
- The sum of the purchase price of the units redeemed: Rs. 180674.9563
- The total capital gain is the difference: Rs. 119325.0437
Since this is an equity fund, the first Rs. 1 lakh is tax-free. So the effective taxable gain is only Rs. 19325.0437.
Now 10% of this will be taxed. So Rs. 1932.5043. There is a 4% education cess on this = Rs. 77.3. So the total tax is Rs. 2009.8045. So the post-tax redemption is Rs. 300000 minus Rs. 2009.8045 = Rs. 297990.1955.
Imagine how complex the calculation will be if (a) some units are less than 365 days old and some older or (b) if it is a non-equity fund. Then we need to determine the cost inflation index in each financial year of the redeemed units and inflate the purchase price to the financial year of purchase (see example linked above) or (c) if there are multiple redemptions in the past – we need to ensure redeemed units are not accounted for again.
This naturally brings a question: “If I wish to redeem Rs. 1 lakh from equity funds each year, can I find the approximate units to redeem?” As a spreadsheet implementation challenge, developing a tool for this would be interesting. However, we do not recommend this as it is unnecessary. See examples here: Should I book yearly profits (up to the tax-free limit of one lakh) to lower Equity LTCG Tax?