Last Updated on December 21, 2023 at 5:17 pm
We had recently discussed how to enter STCG and LTCG from equity shares and mutual funds in ITR2 or ITR3. We now follow this up with a guide to enter capital gains from the sale of property in ITR2 or ITR3.
Do check out our earlier articles on tax filing:
- How to enter mutual fund and share capital gains in ITR2 (or ITR3)
- How to use MF capital gains statement for STCG & LTCG entries in ITR2 (or ITR3)
As with any capital asset, the cost of sale and the cost of acquisition (purchase) are the keys to computing capital gains. CG from property use index cost of acquisition. That is, the purchase price of the property will be inflated using the cost inflation index to the financial year of sale.
For example, a property that cost 50,00,000 on 1st Jan 2009 will today (1st March 2022, financial years of sale) cost 1,15,69,343. This value will be auto-calculated by the ITR2 or ITR3 form and will be used to compute the capital gain = Full value of consideration minus the indexed cost of acquisition.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
If the property was sold for Rs. 2 Crore in March 2022, the actual capital gain is Rs. 1.5 Crores where the taxable capital gain is only Rs. 84.3 lakhs!
However, there is an issue with the cost of acquisition. If we had purchased the property after 31/03/2001, there is no issue, we can enter the cost as per the sale deed.
If the property was acquired on or before 31/03/2001, the fair market value as of 01/04/2001 should be entered. The reason for this is the cost inflation index was reset from 1st April 2001.
There are two ways to obtain fair market value as of 01/04/2001
- Consult a property evaluator who would visit the premises and estimate this. This is what CAs would recommend.
- Use the old cost inflation index data to compute this value. See: Cost Inflation Index Historical Data. Many CAs may not agree with this but I don’t see why this should not be done.
How to enter capital gains from the sale of property in ITR2 (or ITR3)
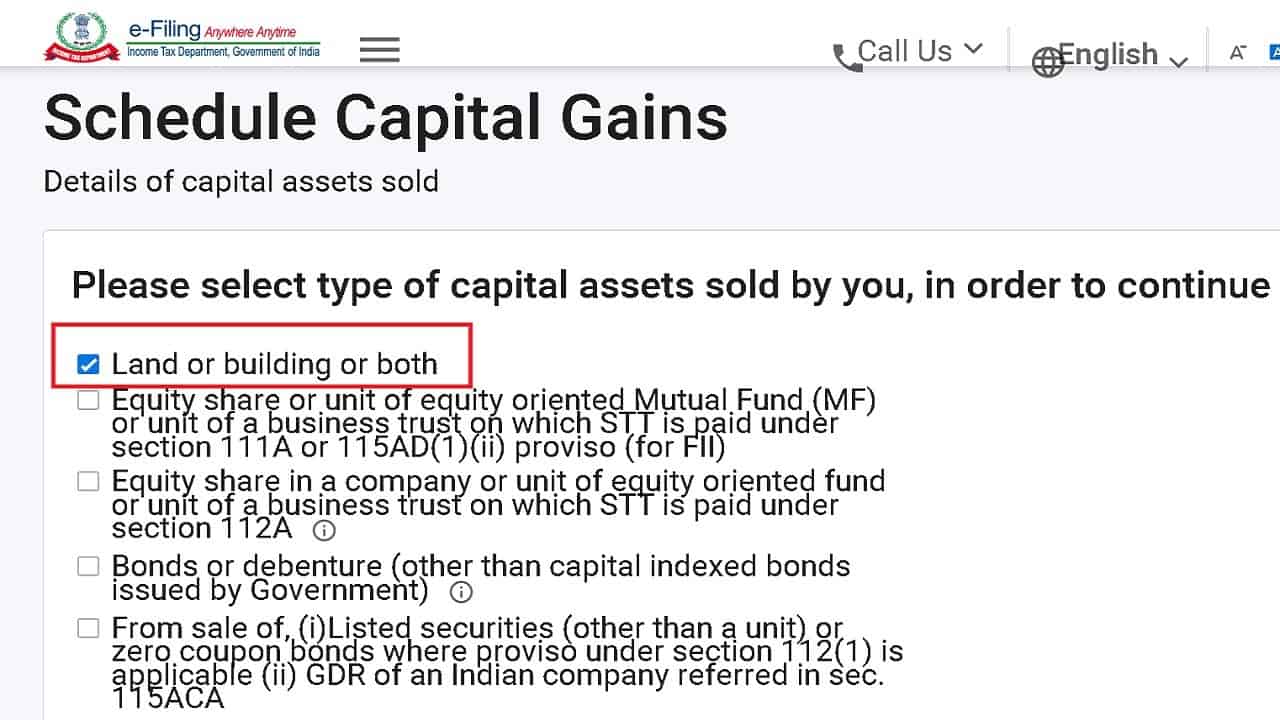
In the CG schedule, select, “Land or Building or both”
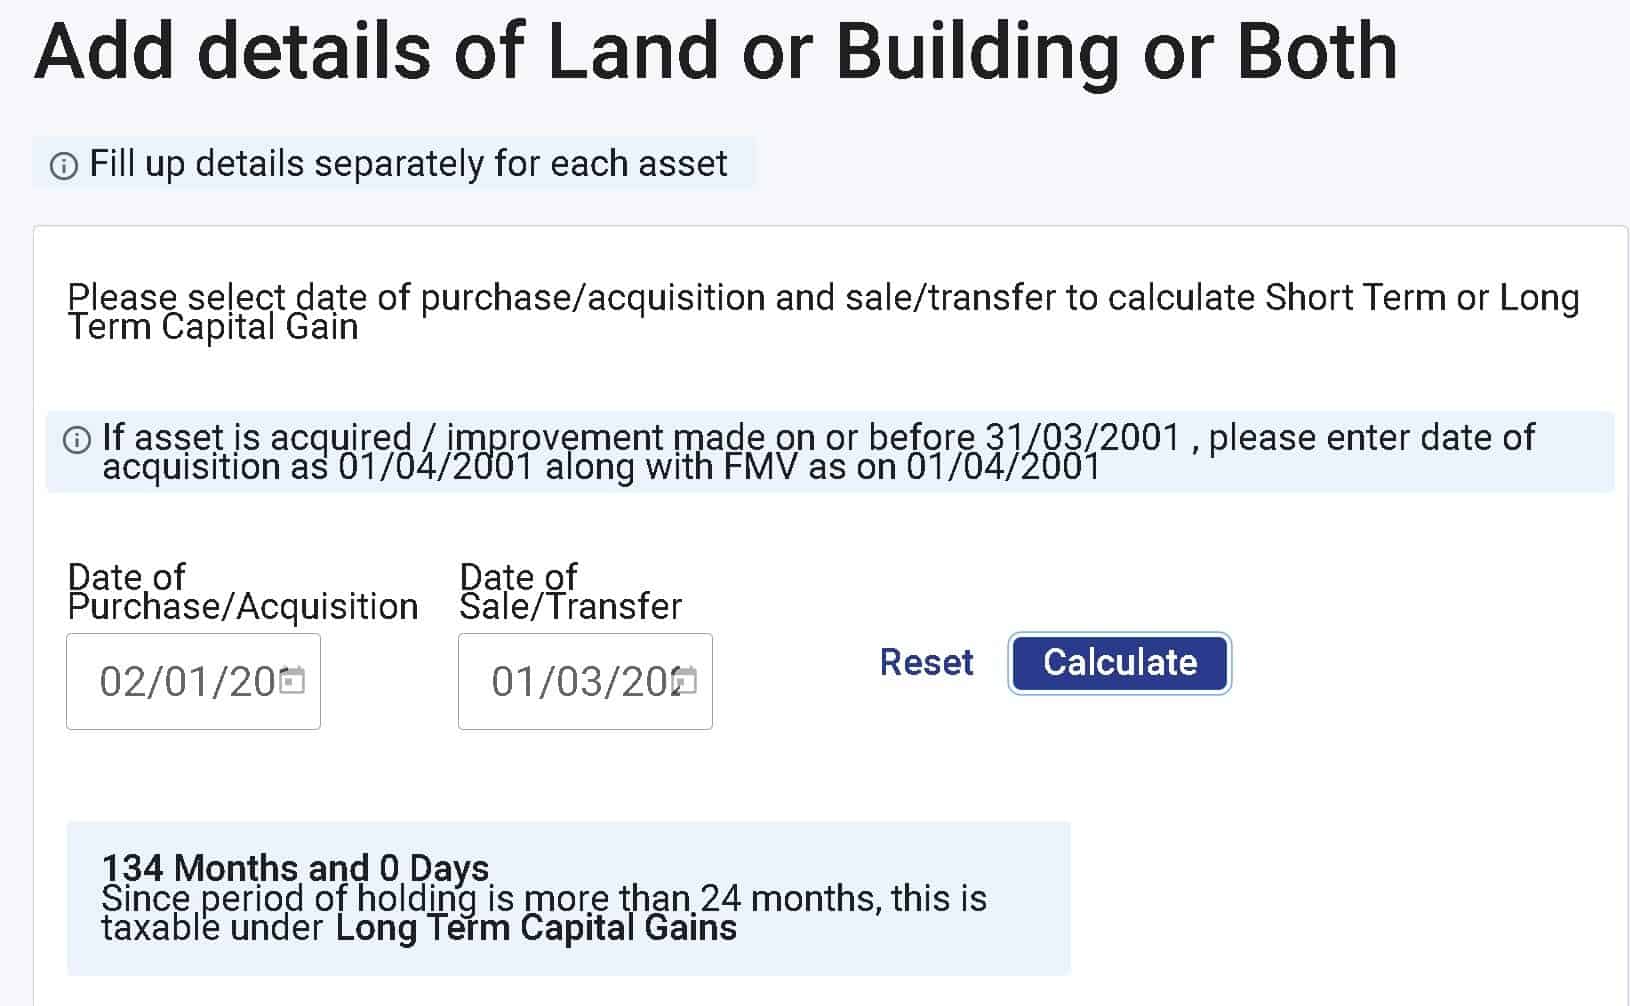
Enter the date of purchase and sale. The sheet will automatically determine if the CG is short-term or long-term.
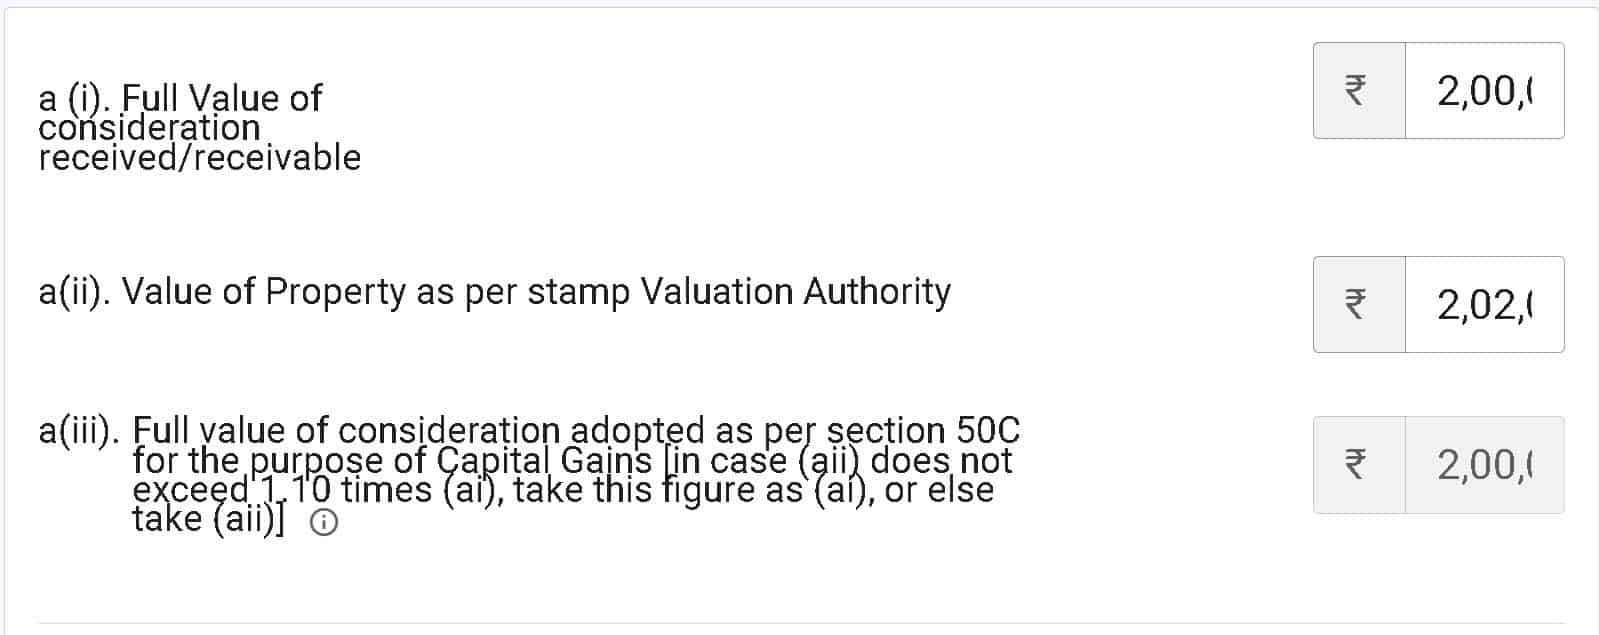
The next step is to enter the sale value (full value of consideration) and the stamp duty property value. The full value can be at most 10% lower than the stamp duty property value. If it is any lower, then only the stamp duty value will be used.
Next, the cost of acquisition should be entered. The cost of acquisition with indexation will be auto-calculated.
Cost of improvement: Any expense made on the property with an aim to improve its value can be shown as a cost of improvement. These expenses made in different financial years can be entered separately and their indexed cost will be auto-computed.
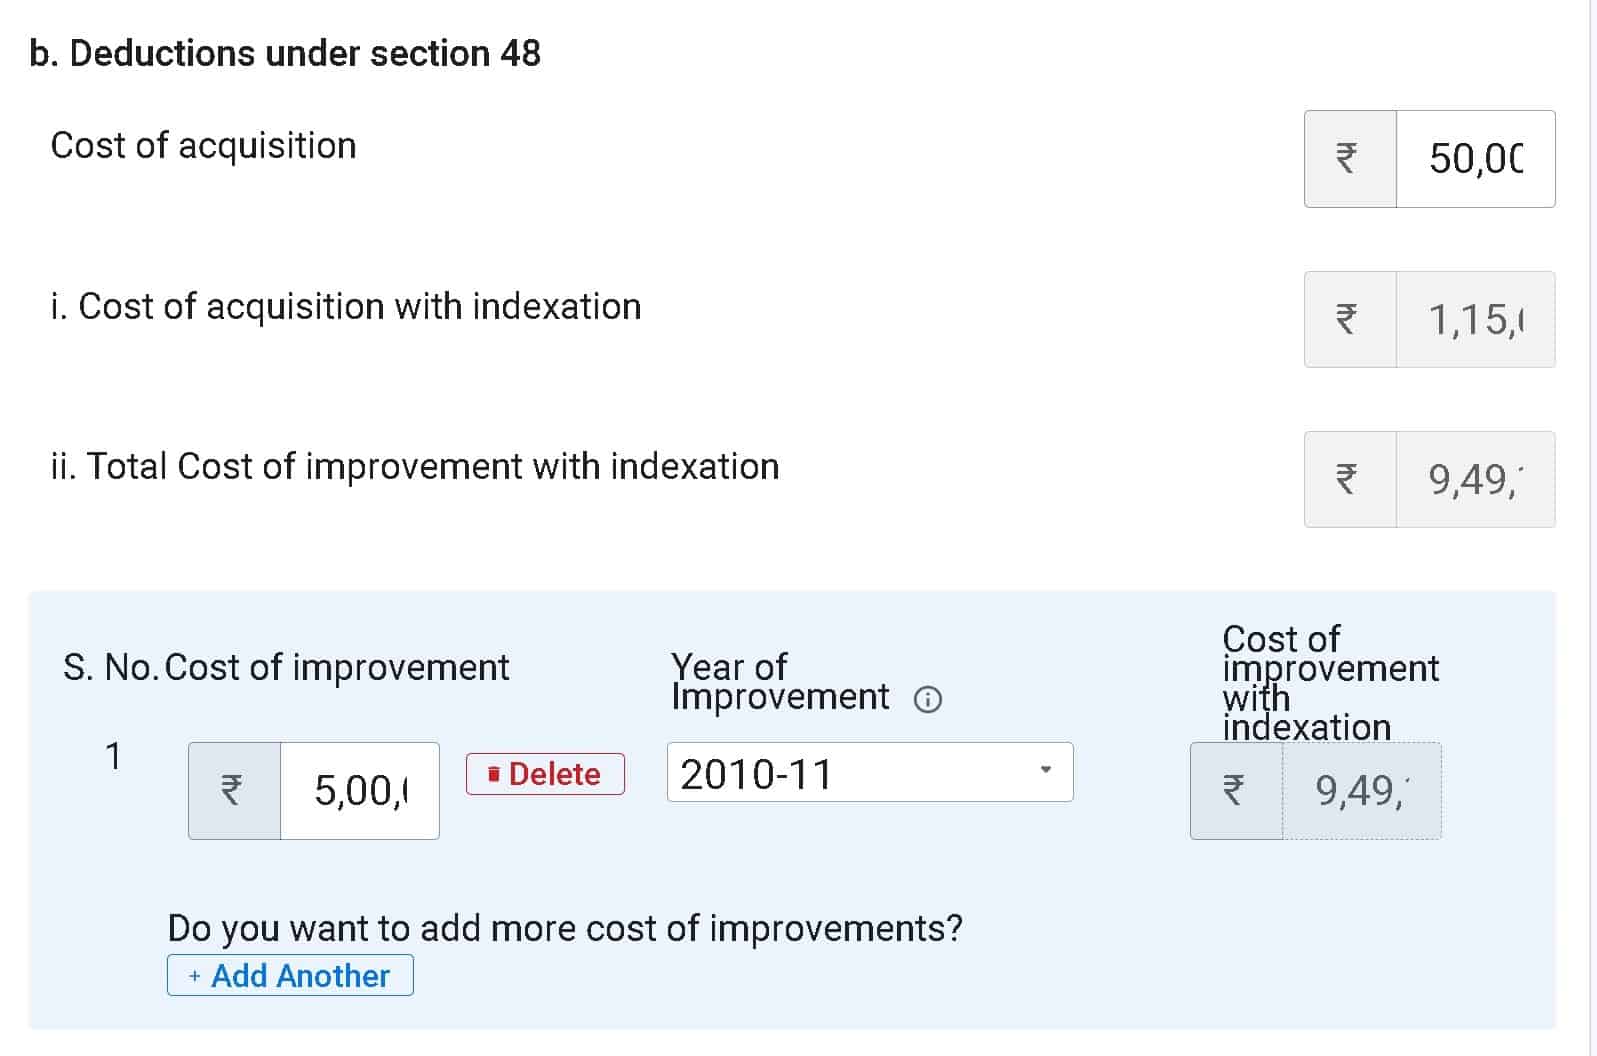
For properties improvements done on or before 1st March 2001, 2001-02 should be entered as the FY of improvement and fair market value as on 1st April 2001 should be used. We can use the old cost inflation index scale to determine this.
Next expenditures connected to the transfer such as brokerage, commissions, stamp duty cost, travelling expenses or registration fees can be entered.
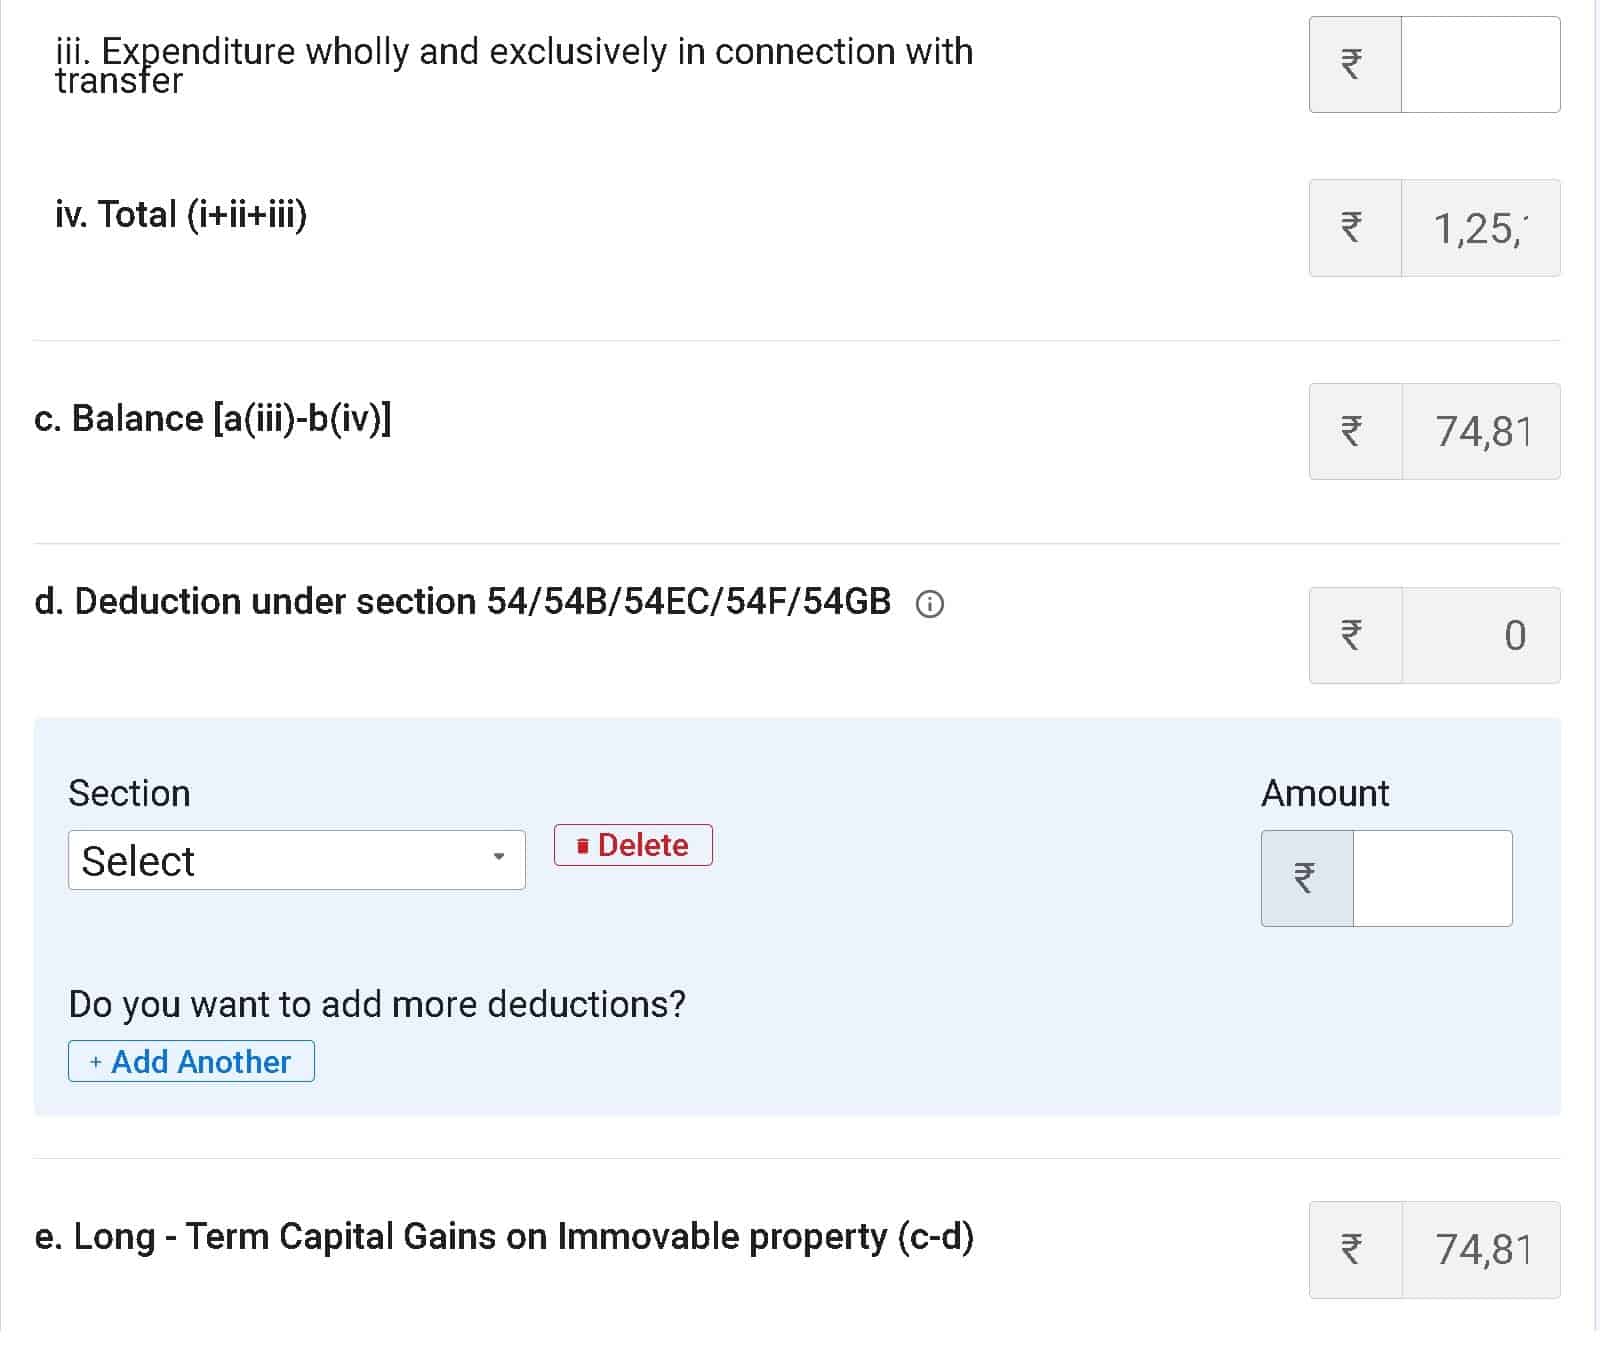
Deduction under section 54/54B/54EC/54F/54GB: If the proceeds from the property sale are reinvested in a residential house or if section 54EC bonds are purchased, then tax payable on the sale can be proportionally lowered. This is a huge section in itself and cannot be covered in this article. Interested readers may consult this guide by CA Karan Batra: Section 54, 54EC, 54F: Capital Gain Tax Exemption in 2022.
Finally the details of the buyer. If the buyer’s Pan and Aadhaar are mentioned in the sale deed or if the buyer of an immobile property deducted TDS at 1% while making the payment to the owner or seller of the property then Pan and Aadhaar must be mentioned here. The TDS is applicable only for transactions over Rs. 50 lakhs. See this resource for other conditions under section 194IA.
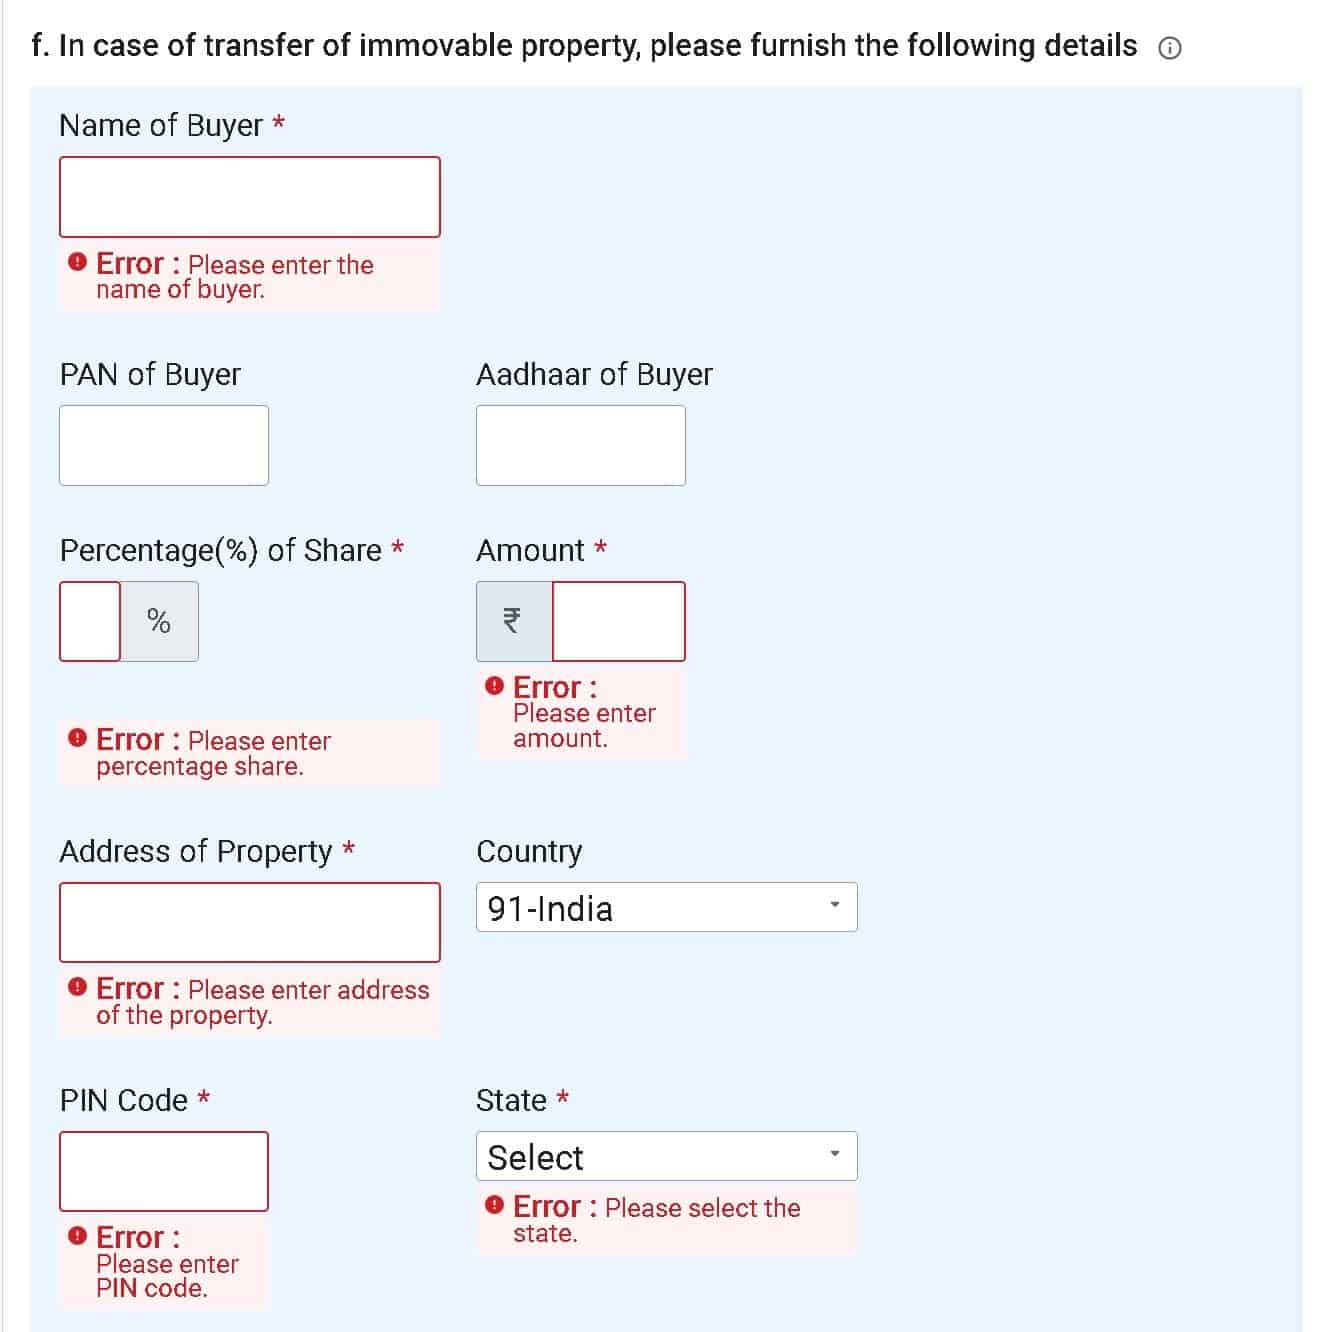
This completes the process of entering capital gains from the sale of property in ITR2 (or ITR3)