Last Updated on December 29, 2021 at 5:41 pm
Here is how you can set off LTCG from shares against LTCL in ITR2 for the financial year 2019-2020, that is for the assessment year 2020-2021. Some readers have pointed out that the benefit of the Rs 1 lakh exemption is not being applied in the ITR2. This is not an error in the ITR2 file. Here is how it works.
About the author: Anjesh Bharatiya is a 30+ taxman by profession and a Chemical Engineer by education. He has been an investor in the stock market since age 15! He likes to write about personal finance, stock markets, government policies, taxation, philosophy and football. Editor’s note: This article was made possible thanks to the expertise and help rendered by Manmohan Sethumadhavan
If you have earned Long Term Capital Gains (LTCG) in the FY 2019-20, you are supposed to file your return in ITR-2 form. As you may know, LTCG from the sale of shares/equity mutual funds (covered under section 112A) up to Rs 1 lakh is exempt from tax. However, if you have incurred Long Term Capital Loss (LTCL) from some other avenue, there is a certain peculiarity in store for you.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
This LTCL is set off against the LTCG under section 112A without providing the benefit of the Rs 1 lakh exemption. You might think this is an error in the ITR-2 return filing utility. Let’s find out more about this.
Setting off losses: You can set-off losses incurred under a head of income against gains/profits from other heads subject to certain conditions. Both intra-head and inter-head set-off are possible. The rules are tabulated below:
| Type of loss | Intra Head Adjustment Allowed | Inter Head Adjustment Allowed |
| Short Term Capital Loss (STCL) | Yes. Only against STCG & LTCG | No |
| Long Term Capital Loss (LTCL) | Yes. Only against LTCG | No |
| Loss from House Property | Yes | Yes (up to Rs 2 lakh) |
| Loss from speculative business (Includes intraday trading in stocks) | Yes. Only against gains from speculative business | No |
| Loss from specified business | Yes. Only against gains from specified business | No |
| Other business losses | Yes | Yes (except against salary income) |
Also, losses which couldn’t be set-off can be carried forward for different time limits and can be set-off in the future years as per the rules laid out in the above table. Both STCL & LTCL can be carried forward for 8 years.
Setting off LTCG from shares against other LTCL
This is where there is a technicality. If you have earned LTCG from shares of less than Rs 1 lakh and have also incurred LTCL from some other source (like from sale of land), you might think that the other LTCL will be set off against the LTCG from shares only after the free limit of Rs 1 lakh allowed under section 112A and you will be able to carry forward the entire LTCL for setting off in future years. But this is not exactly how this works. Let’s understand this with an example and screenshots from the ITR-2 utility.
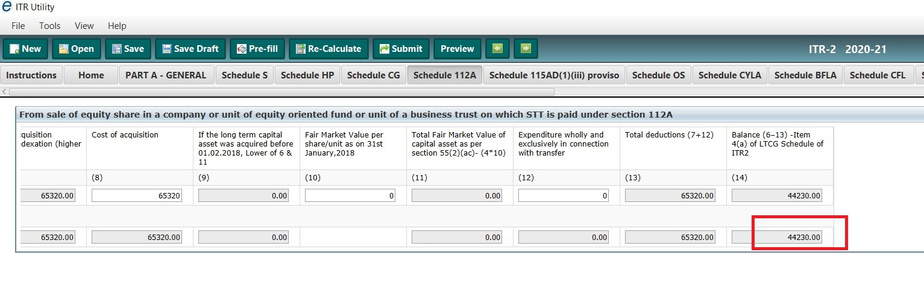
1. I sold stocks of a company after 1 year and earned LTCG of Rs 44,230/- (marked in red)

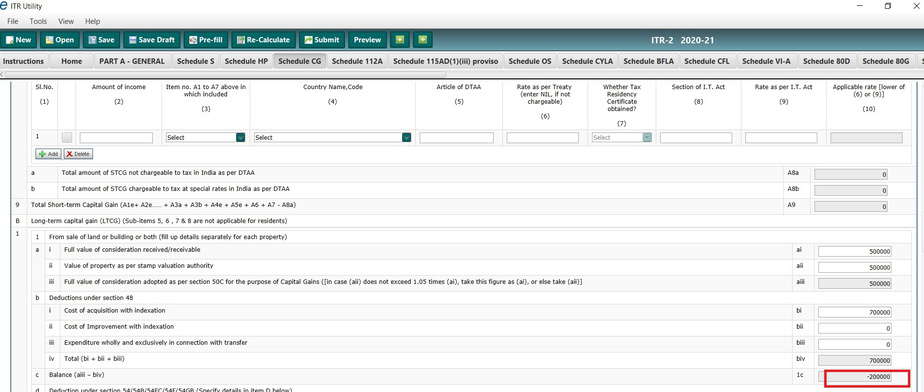
2. I also sold some land and incurred an LTCL of Rs 2,00,000/- (marked in red)
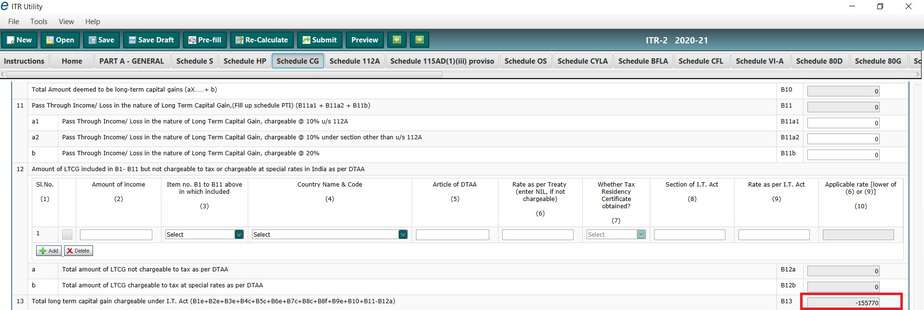
3. Now, the ITR utility does not set-off the LTCL after considering the Rs 1 lakh exemption under section 112A. So, the total LTCL is not Rs 2,00,000/-. Instead, the utility sets off the LTCL of Rs 2,00,000/- from the sale of land against the LTCG from the sale of shares of Rs 44,230/- even though LTCG from the of shares is exempt up to Rs 1,00,000/-. So, the total LTCL for the year is only Rs 1,55,770/- (marked in red) which can be carried forward to the next year.
What happened here? The exact wording of the relevant part of Section 112A is: The tax payable by the assessee on the total income referred to in sub-section (1) shall be the aggregate of—(i) the amount of income-tax calculated on such long-term capital gains exceeding one lakh rupees at the rate of ten per cent
So, the gains of up to Rs 1 lakh under section 112A are still technically LTCG and will be set off against any other LTCL. The section does not provide any exemption up to Rs 1 lakh but only says that tax is calculated only on the portion above Rs 1 lakh. Also, if there are brought forward LTCL from previous years, they too will be set-off against this LTCG under section 112A (even if the LTCG is below Rs 1 lakh). This set-off is not optional.
In summary, for people having both LTCG under section 112A and other LTCL, the benefit of Rs 1 lakh will not be available to the extent of the LTCL. There is no glitch in the ITR 2 utility. And the LTCL will be carried forward only after setting off against the LTCG under section 112A, whatever the LTCG.