About 80% of those who ask us about Sovereign Gold Bonds want to buy them for the wrong reasons. I would wager that the number is about the same in the Facebook group Asan Ideas for Wealth, if not more.
When not to buy Sovereign Gold Bonds!
Those who want “some returns” from gold or some gold exposure in their portfolio for “diversification” should not buy Sovereign Gold Bonds. They are not liquid enough, you cannot sell them mid-way (unless you are ready to sell lower than the market rate of gold), and if you wait for them to mature, the returns can be anything! Below are the 8-year rolling returns of gold USD and gold INR price per troy ounce from Jan 1979 to Feb 2023.
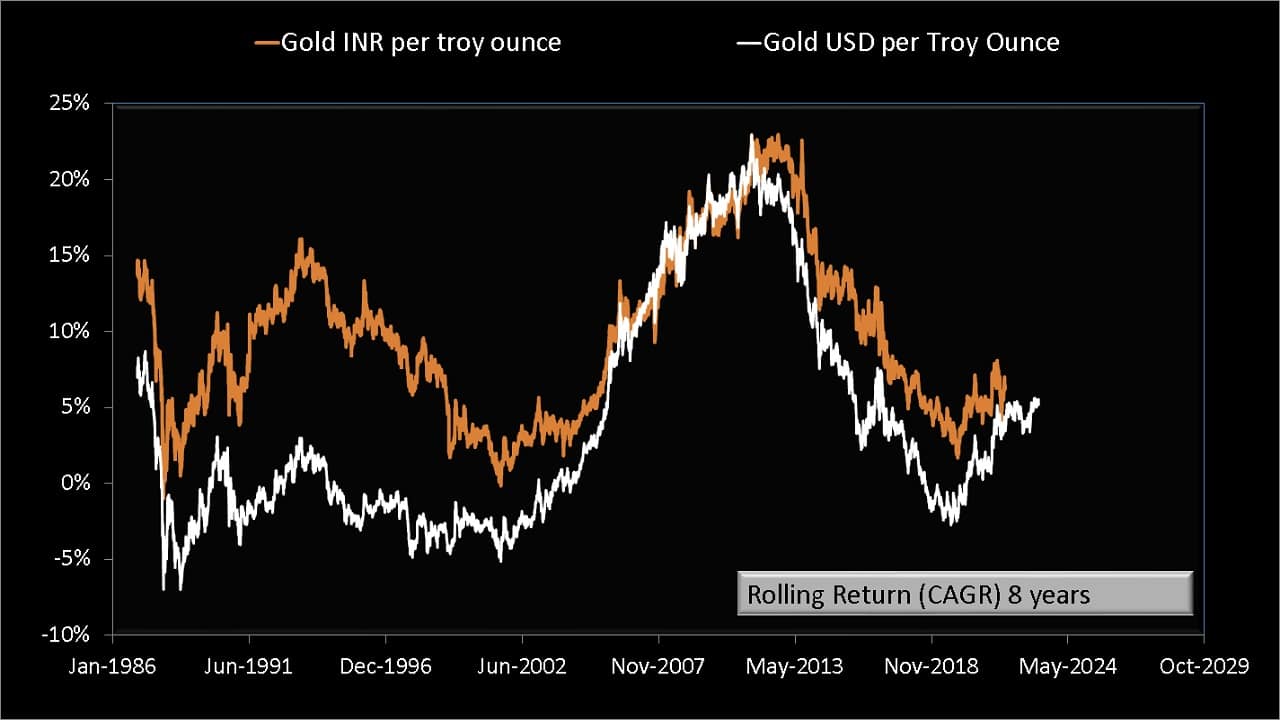
Since you cannot sell them freely, you cannot tactically book profits or rebalance systematically with these bonds. If you wish to do this, choose a liquid ETF with low-price-NAV variations. A gold fund that invests in a gold ETF would be a better choice.
Sadly, many people who chase after returns from these bonds wish to hold them to maturity only because they are tax-free if done so, and most investors do not care about asset allocation or rebalancing. This is the same as leaving the fate of our hard-earned money to luck. Our money deserves better respect.
When to buy Sovereign Gold Bonds
Use these only to accumulate gold for a future need, say, for a marriage. Sovereign gold bonds offer a tax-free, risk-free way to accumulate gold if your future gold purchase is over eight years away. You also get 2.5% interest (taxable as per slab) on the initial gold value as a “thank you for trying to reduce gold imports” gift from the govt.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
You can buy these bonds in the primary market (via banks) or (in principle) in the secondary market via a demat account from desperate investors looking for cash and willing to take a loss. This approach is risk-free because the bond tracks the price of 24-carat gold, and at any given time and after eight years, one could buy 22-carat jewellery.
In summary, if you wish to buy sov gold bonds for “returns” or their tax-free status, you will do so for the wrong reasons. Use them only if you aim to buy physical gold after eight years. If you intend to buy gold after over ten years, a simple mix of equity and fixed income is better.