Last Updated on December 18, 2021 at 10:32 pm
I have been holding an individual health insurance cover for my family for the last 10 years. In this post, I look at how the insurance premium has increased during this period.
I hold a United India Platinum policy for self, wife and son and a Gold policy for my mother. Each year, I have increased the cover for each member by as much as the insurer would allow.
The cover for me and my wife has doubled from 3L in 2006 to 6L in 2016. For my mom, it has gone up 3.33 times from 1.5L to 5L.
I did not apply my mind much when I got the policy as it was purchased in a hurry when my dad was diagnosed with cancer and none of us has any insurance. During this period, I have made three successful claims: Once for myself, my mom, and my wife. So I am reasonably happy with my rash decision.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Our premium has increased because of three reasons: because of increase in cover, because of movement into the next age band and possibly because of claim-based loading.
The total annual premium was about 0.5 times (50%) the monthly expenses in 2006 and has now grown to 1.2 to 1.3 times more than monthly expenses in 2016.
Health insurance is a personalised product. So consider the trends mentioned in this post as a rough indication of what to expect with your own policy.
The life insurance space has changed quite a lot in the last 10 years. We now have more options from private players. In Feb. 2014, IRDA mandated no-claim-based loading for health insurance policies. We now have the convenience of portability (at least on paper). And we now have group insurance policies offered by banks, which makes it more affordable.
The premium per lakh considered below is the bare premium before service tax, stamp duty, family discount and no-claim discount.
Amma

The circle represents the renewal premium when a claim was made in the previous policy. The sharp jump could be due to claim based loading and/or movement into a higher age band (post 65).
The claim arose days before the IRDA announced no claim based loading rules. So I wonder if it is due to loading.
Notice that although the sum insured increased steadily with age, the premium per lakh seems to have decreased for a few years! This seems to be the behaviour within each age band as seen below.
Myself
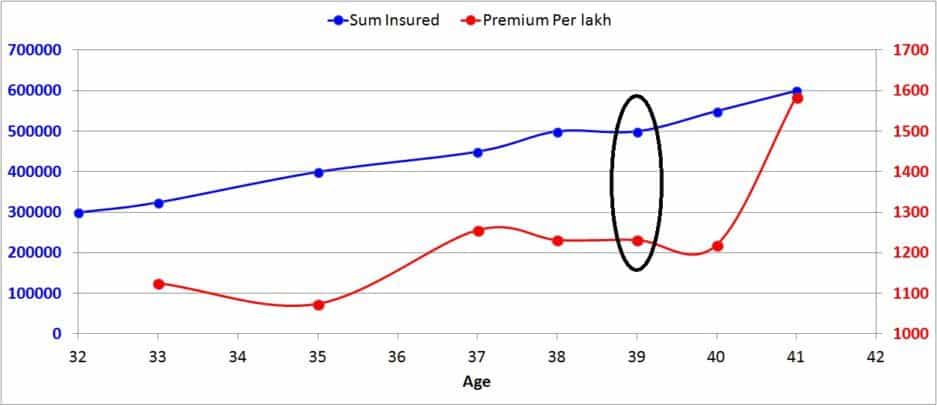
The oval represents the renewal after a claim. This was when no no-claim loading was firmly in place. The insurer did not increase the premium, but told me that I cannot increase the sum insured that year!
The sharp increases in premium per lakh at ages 36 and 41 should correspond to my moving into different age bands and hence increased risk of hospitalisation.
Wife
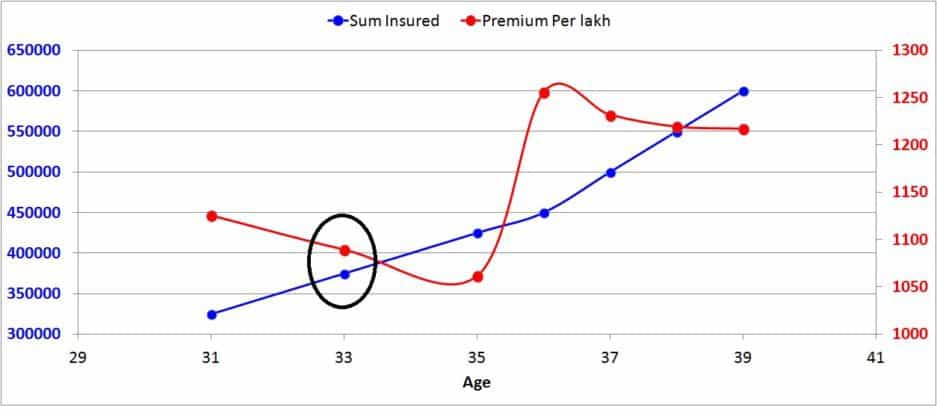
Notice here again that the premium per lakh sharply jumps above 35 and comes down a bit within that age band (35-40).
My Son

I can’t find the policy when he was new-born and 1Y old. Notice how the premium per lakh has dropped sharply. This is because infants and toddlers are high risk for hospitalisation (even with all the vaccinations that we have now).
Overall Increase
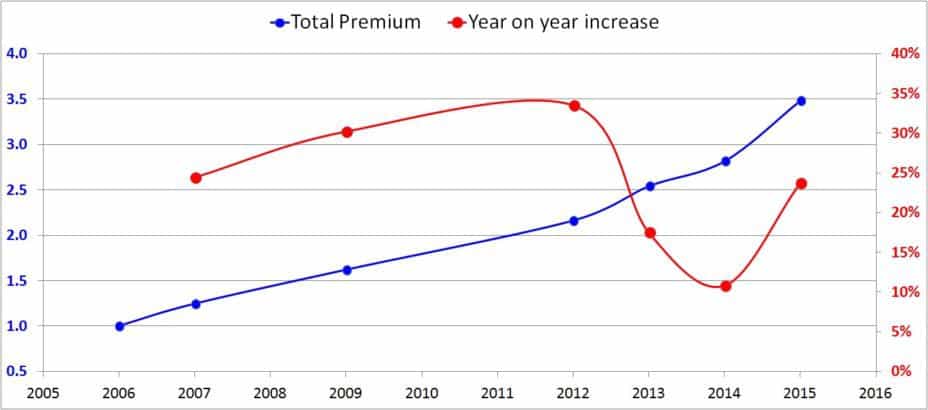
This is the total premium (set as 1 during the start of the policy) and the year on year increase. A value of 1 in 2006 has become 3.5 in 2016.
The overall increase in premium is about 15%!
I think it would be safe to say that regardless of the policy, if the sum insured is increased each year, the premium should at least increase by 10%.
I have been lucky (so far) not to have received a letter from United stating that the policy with the same sum insured will now cost ~ 100% more!!
In Jan 2016, Swapnil Kendhe posted about discontinuation of no claim discount and an increase in Oriental Insurance premium due to
Revision on premium is based on new improved features and claim experience of portfolio including medical inflation. However, we as a responsible Insurer value our relationship with you and have tried our best to keep the premium increase to the minimum.
Since then, a search in FB group Asan Ideas for wealth reveals a premium increase of 90%, 100%, 163% ….
Now that is a blow one cannot prepare for! Will portability help in such cases? Can anybody who went through such an increased and shifted their policy comment on this?
In case you are wondering, “why does he not shift to another policy?”. 1) I have a lot of inertia and 2) I cannot even if I wanted to. Both I and my mom have conditions which a new insurer is unlikely to accept! Thank God we got our policy when we were young and healthy!!