Last Updated on December 29, 2021 at 5:19 pm
Here is an example of how much you lose by choosing the limited premium payment option in term life insurance, also simply known as “limited pay”. It is the oldest trick in the book. Create two pricing options. One with recurring payment for a longer period (say 25 years) and another for a shorter period (say 5 years). The total spend over 5 years is much less than that over 25. It is tempting to assume the shorter option is better. A closer inspection is necessary.
This is a guest post by Ganesh Ranjan who wrote in with this question: Paying my premium in the accelerated plan or limited-term option proves to be 40% cheaper than having to pay the premium for the entire duration of the policy. Which should I choose?
Ganesh then did the analysis himself to recognise that normal annual premium payment is better. He has kindly agreed to share the analysis with freefincal readers.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
I was shopping around for term insurance policies when I came across an option of paying the premium for the insurance in a limited-term (i.e pay the entire premium due in 5 years, 7 years and 10 years) with the ICICI Prudential iProtect term insurance plan.
Here are the basics about the coverage. I am 37 years old and I wish to be covered till the age of 65 with a coverage of 5 crores.
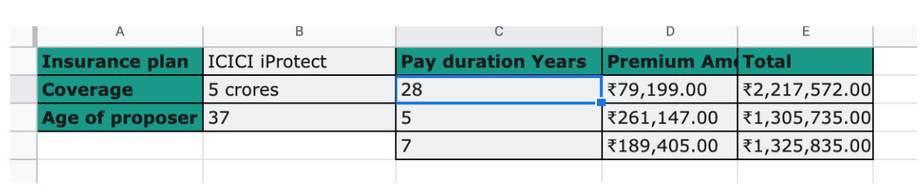
If I pay for 28 years (i.e. annual premium) I would pay Rs.79,199 every year totalling Rs.22.17 lakhs for the entire duration of the policy. Instead, if I chose to pay it in 5 years, the premium per year for the 5 years is Rs.2,61,147 totalling Rs.13,05 lakhs. Thus the option of paying the premium in 5 years is cheaper by Rs.9,11,837 (i.e. 41%). We shall call this Rs. 9.11 lakh as the opportunity cost.
I thought something was amiss in this since it was possible for the insurance company to provide me 41% discount if I pay in 5 years and make a profit in the process, why shouldn’t I be able to do it?
I hence approached Mr.Pattu from freefincal.com who advised me against the limited-term payment option as it was not going to be cheaper in the long run. When I approached him I thought I wasn’t capable of evaluating through excel both the options. But I played around and came up with 2 scenarios.
Scenario 1 – I chose the 5 years limited premium payment option
Scenario 2 – Instead of paying ICICI the higher premium for the 5-year option, I would pay the annual premium and assume that I was paying the higher premium and put the difference in the premiums in an FD during each of the 5 years.
In my calculations, I have assumed 6.5% as the rate of fixed deposit interest.
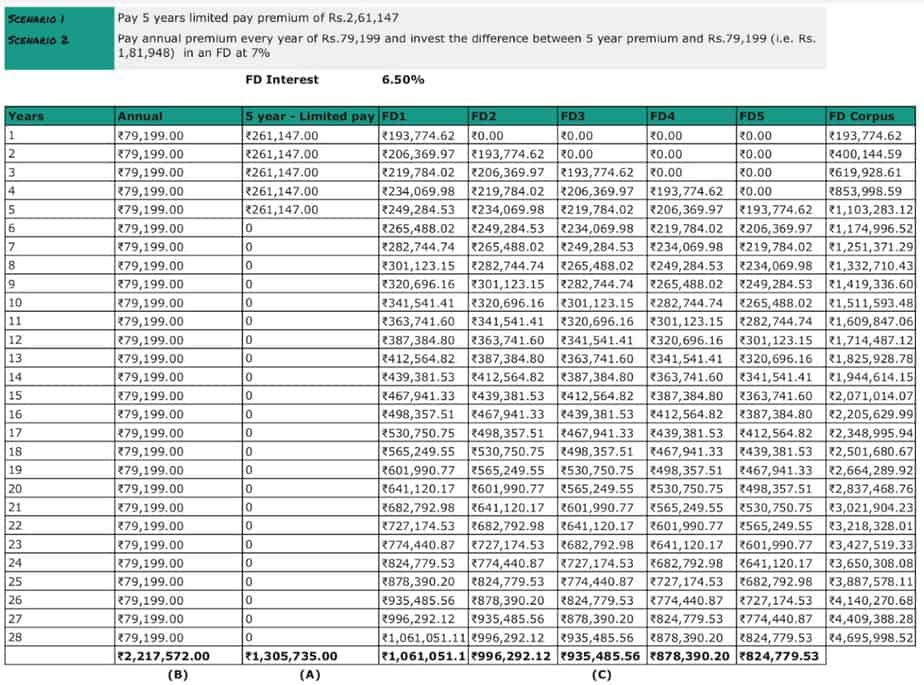
The net result is that we arrive at the net positive cash flow of Rs.15.66 lakhs in scenario 2 as opposed to net negative cash flow of Rs.13.05 lakhs with scenario 1.

Note: I have factored in the reduced premiums if one had chosen the 5-year premium payment option also in scenario 2 as an opportunity cost
Editor’s note: Even if you do not agree with all the assumptions made, clearly paying the premium each year is significantly beneficial even if one leaves the additional amount in a saving bank account instead of choosing the limited pay option.
There is yet another message in this post. Ganesh did not know what to choose. All I gave him was a cryptic, “don’t choose limited pay term insurance”. He decided to dig deeper for his own satisfaction resulting in this helpful post. This is proper DIY at work.