Last Updated on February 12, 2022 at 6:32 pm
The failure of finance companies like DHFL, IL&FS, banks scams like the one involving PMC Bank Fraud (Lessons from Sanjay Gulati’s story), the alarming number of urban co-operative banks placed under directions by the RBI (meaning withdrawal restrictions – imposed on 24 such banks as on Oct 2019) has spooked depositors all around the country. Can the same happen to a mutual fund? Can a mutual fund go bust (become insolvent) like a bank? We find out in this article.
Can Mutual Funds Fail (go bust) Like Banks?
The short answer is: Mutual funds cannot go bust like a bank as they are structurally and operationally different. Fraud can occur in a mutual fund, e.g. run away with unitholder money, but the probability of this happening is comfortably low. Unitholders can suffer from poor fund management practices, as explained below.
To understand better, we must differentiate the objective and organisational structure of a bank and a mutual fund.
The primary or core job of a bank is borrowing and lending. A bank borrows money from its depositors in exchange for fixed interest and lends to individuals or organisations at a higher interest. Although the two activities are connected, there is no direct relationship between the two. That is, the lender (FD or RD holder) cannot track where/how the bank is using her money for profit.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
The mutual funds primary and only job is asset management. They take unitholder money and invest it in a variety of stocks, bonds, gold, REIT etc. The unitholder is aware and can track how her money is invested.
Structure of a bank
As an example, let us consider the top management organisational structure of SBI
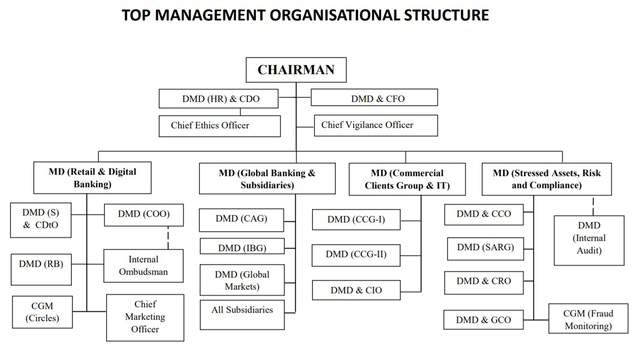
This is often the main reason why banks fail, why they pay out bad loans, why they fudge account details. When we transact with a bank, there is no other independent third-party overseeing the transaction.
Structure of a mutual fund in India
A mutual fund in India is set up like a trust. A trust is an arrangement involving three parties (unlike a bank): the unitholder (or investor), the mutual fund company (AMC) and the mutual fund trustee.
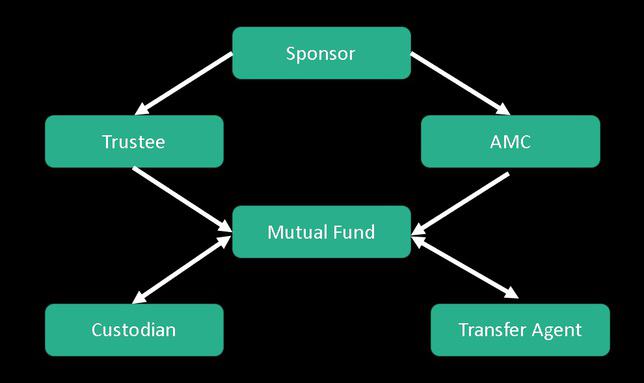
The owner (sponsor) of the mutual fund creates a board of trustees that is responsible for overseeing the operations of the fund. They will have to ensure compliance with SEBI regulations. A custodian registered with SEBI holds the assets in the fund and is answerable to the trustees.
Two-thirds of the trustee board must not be part of the sponsor company. This also applies to half of the AMC directors. This arrangement makes it extremely difficult for the mutual fund to run away with unitholder money or violate SEBI regulations.
The question of a mutual fund not having enough money to pay unitholder does not arise the gains or losses made by the fund manager is directly passed on to the mutual fund. Also, there is monthly portfolio disclosure and periodic audits which have to be submitted to SEBI.
Therefore, a mutual fund cannot fail like a bank. It can, however, get into trouble in other ways.
SEBI does not directly control the choice of investment. These can be within subsidiaries of the sponsor and therefore involve a conflict of interest. Also, as recently witnessed in the Zee-Essel bond case, fund houses could come to an agreement with bond issuers about not devaluing bad bonds: Eroding trust: Are mutual funds really market-linked products? SEBI then issued a show-cause notice in this regard.
A mutual fund can deviate from SEBI regulations and even commit fraud. This will sooner or later reflect in the NAV of a mutual fund. The situation here is quite different from a bank where it can survive for months and even years with bad loans in its book and by just paying out interest as long as there are no mass withdrawals.
A mutual fund can also limit the withdrawal of funds but only for amounts of more than two lakhs and only during a market-wide crisis or exceptional circumstances like flood, earthquakes etc. and only for ten days. These rules (when read in entirety) are quite fair and protects the interest of unitholders. Contrast this to RBI suddenly stopping all withdrawals for an indefinite amount of time and relaxing it in stages in view of protests and political pressure.
Video Version
Summary
In conclusion, due to the very nature of its setup (as a trust) and objective, mutual funds cannot fail like banks or become insolvent. And it is a lot harder for a mutual fund to run away with unitholder money. This does not mean mutual funds are “safe” or fraud-free. There can be other ways by which they can bend the rules or even break them with regard to security selection and expense ratio appropriation, but these will surface a lot quicker than the case of banks.
While investors must appreciate the organisational setup and regulations, there is no need for unfounded, irrational fear or comfort!