Last Updated on December 29, 2021 at 5:26 pm
This is a performance report of my (mandatory) investments in the National Pension Scheme (NPS) Tier 1 (Central Govt) scheme from March 8th 2010.
I have been part of the NPS since 2006. However, the NPS was not ready for investment then. Until it was, the organisations F&A O held the money with 8% annual interest. The first investment into NPS funds was made on 8th March 2010.
We shall track the progress from that date. The money was almost equally divided among the three Tier 1 (central govt) schemes from UTI, LIC and SBI. The asset allocation was 15% equity and rest in bonds (most gilts, see effects of that below).
NPS with employer contribution is one of the best step-up SIPs into a mutual fund. My monthly investment today is 4 times more than what it was ten years ago. That is a 15% year on year increase in investments spanning two pay commissions and promotion.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
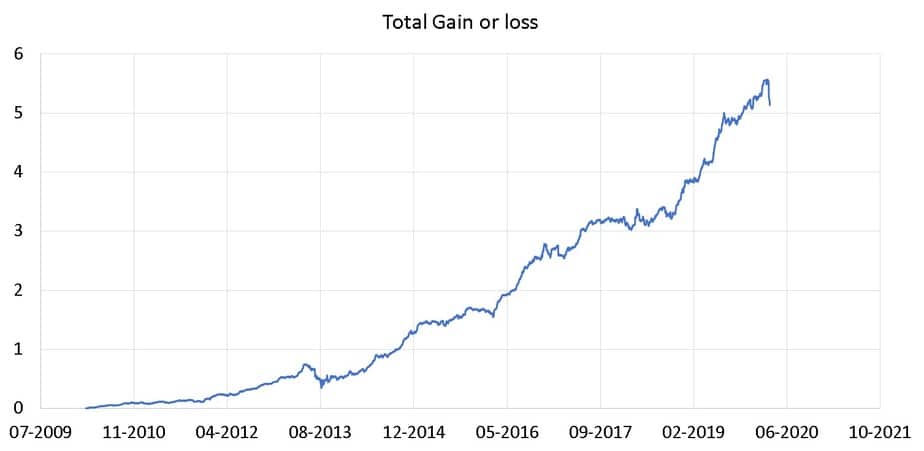
This is the growth of the NPS portfolio along with total investments. The XIRR as on 17th March 2020 is 8.99%.
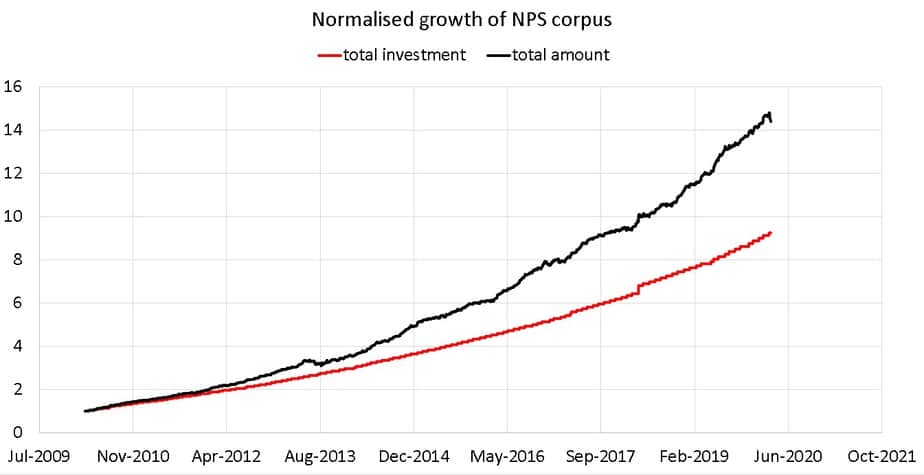
Notice the fall in July 2013. That is when RBI has to increase overnight rates by 2% to stop the fall of the Rupee (same reason why rate cut may not happen now, more on that later). My gilt-heavy NPS portfolio took a mighty tumble.
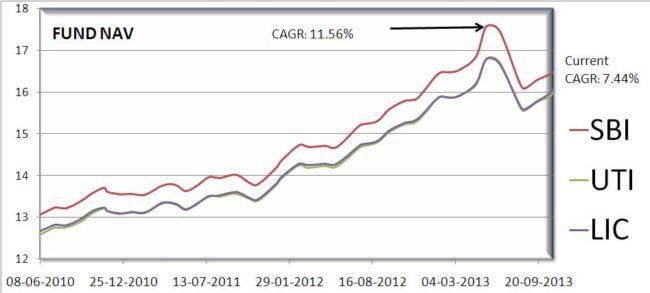
This is how the NAV looked like in Oct 2013. My NPS CAGR just before the fall was 11% ish and overnight it became 6-ish% recovering over the next few months. When this occurred, PFRDA realised “aisa bhi hota hai! What if this happens just before the person retires?!”, and introduced staggered withdrawals.
NPS vs EPF
If I had invested in EPF instead of NPS ten years ago, the NAV evolution (assuming daily growth = annual interest/365) would look like this.
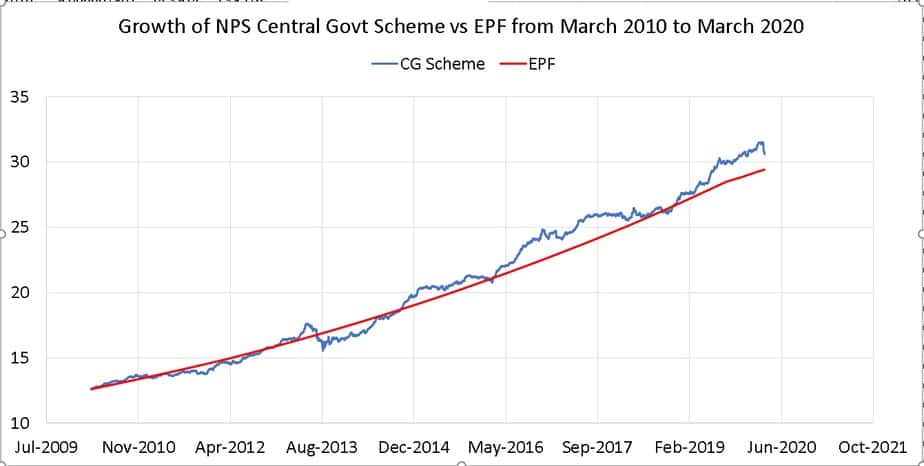
The growth of the investments would look like this. The EPF XIRR would be 8.7%
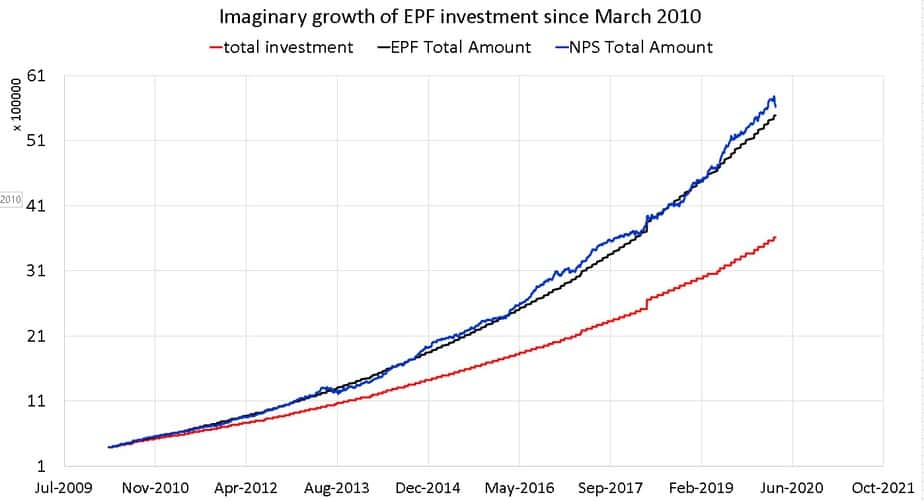
So far so good for mandatory investment! Although the asset allocation of central govt employees can be modified, I have not done it so far (and recommend others not to do it). It is best to use NPS as a pure-debt fund and manage equity separately.
Cautionary note: Kindly do not assume that I am recommending NPS instruments. My situation is quite different than most. If you are in a corporate set up, please recognise that NPS has a lock-in up to 60. Most corporates employees will not work until that age. If you exit before 60, 80% of your corpus will be locked into an annuity. So do not invest in NPS.
NPS resources:
EPF vs NPS: Should you shift to NPS because the govt wants you to?
Do Not Invest Rs. 50,000 in NPS for additional tax saving benefit in 2020! Most of us need to invest an amount = monthly expenses for retirement. So this 50K a year is peanuts you should not fret about.
NPS has EEE (tax-free) Status! Here is why you should still not invest