A reader has multiple questions on goal-based investing, and we address them inline below. “I am 32 years old and have been investing in MF for the past three years, PPF for the past 9 yrs, and SSY for the past 5 yrs. I have two doubts about goal-based investments”.
“1) I have mapped my MFs for retirement goals. For example, if I start another one for kids’ education, there will be an overlap between MFs of goals.
A) How to avoid this or whether this overlap is okay between different goals?”
Answer: The moment you decide that you are going to use different mutual funds for different goals, they become independent portfolios and therefore overlap between such funds has no consequence.
“B) Even if the overlap is within the same goal, how will it affect the assets? If both MFs get profit, both will increase or else both will decrease. It would be the same case even if we invest the same amount in a single MF instead of 2 of the same category. Please write an article on this”
Answer: When you use actively managed mutual funds, overlap in stocks between funds in the same portfolio cannot be avoided (whether the funds are from the same category or not). It is typically neither useful nor harmful and can be ignored. In any case, the effects of such overlap are hard to quantify.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
“2) I have calculated my net worth for the past three years and have doubts about this as my case is a little different or didn’t map it to normal scenarios yet”.
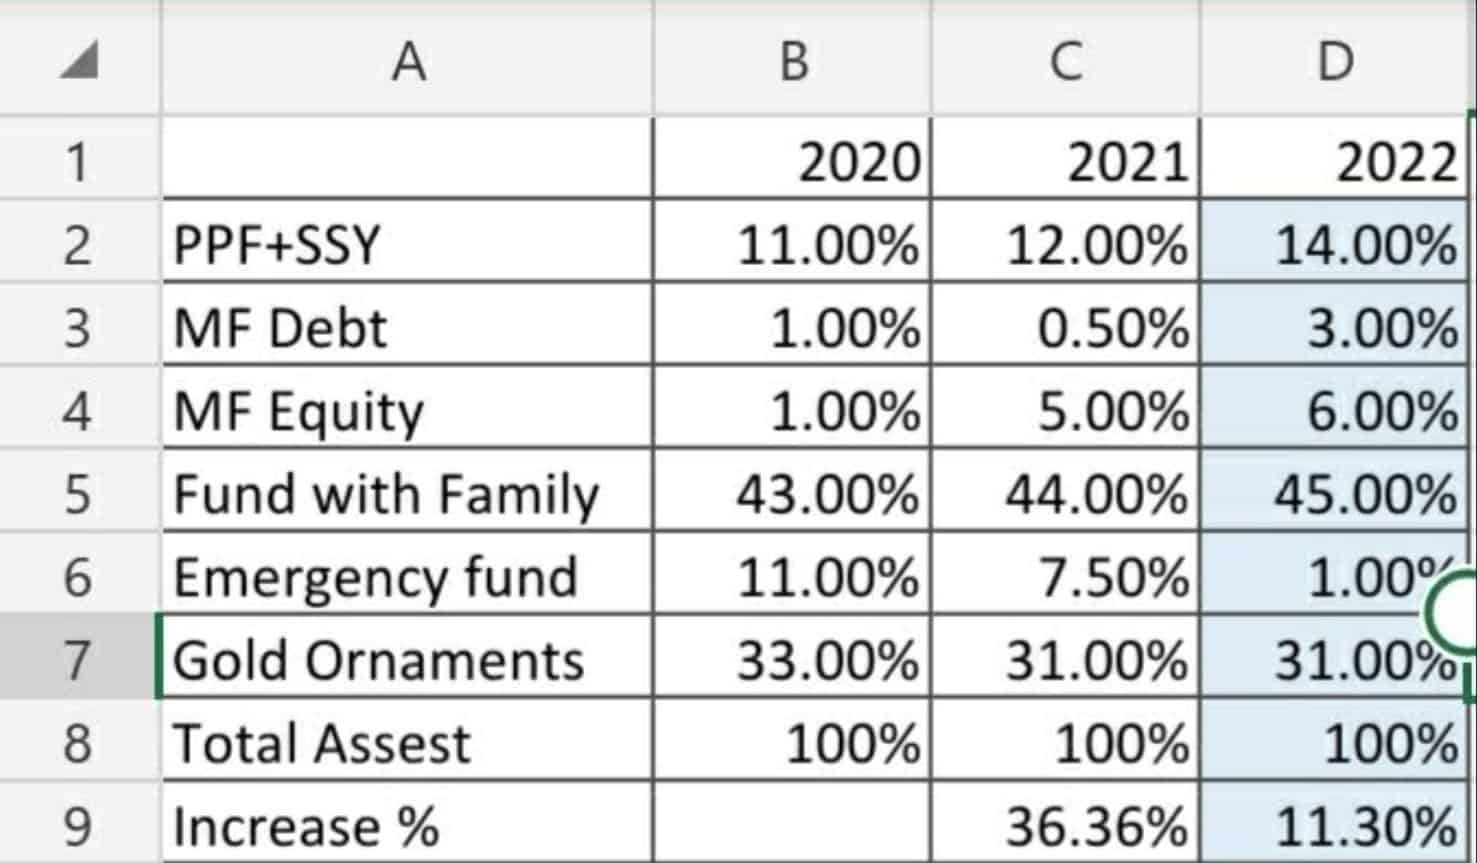
“How do I calculate this overall asset to increase my equity exposure, as this goal is mainly for retirement only? I want to have 60% to 70% in Equity, but how to calculate this?
A) Do I have to calculate this percentage only on the debt and equity of the first three rows?
B) My understanding is all rows need to be counted as my overall Asset”.
“Info: I parked the emergency fund and some of the monthly recurring expenses in Liquid MF, that’s why the debt % is increased for this year. Still, I have to finalize my asset for 2022, but this is the approximate percentage. Do we have to include funds with the family in my name value of Gold Ornaments while calculating the Equity percentage? I cannot take my funds from a joint family as of now. For kids’ education and marriage, I have to map the goals after getting increasing equity, but as of now, in the retirement goal itself, I included all”.
Answer: Gold ornaments, emergency funds, and self-occupied real estate should not be part of your asset allocation for long term goals and net worth.
I don’t know how much of the funds held jointly with other family members you can access for your long-term goals. If you don’t know this already, it is best to ascertain this. However, no part of your income has been invested here, and it is more of an inheritance to be received later, do not count this as part of your net worth for now. You can consider the proportionate amount if you have invested from your income here.
Also, what matters more than the asset allocation of your net worth is the asset allocation of your long-term goals. So list all investments from your income alone (plus a proportionate amount from joint assets). Then tag them to your long term goals like retirement, kid’s future etc.
Look at the investments tagged to retirement alone and find the equity and fixed income (debt) allocations. Repeat for kids’ future and other long term goals. This will tell you where you are wrt equity allocation, and then you can plan how to increase it for each goal.