Last Updated on December 29, 2021 at 11:47 am
As pointed out yesterday, many investors get nervous when the market hits all-time highs on a daily basis and start asking “should I book profits now and re-enter later?”. Sadly, they only talk about the exit mark and have no idea when they would re-enter. It amounts to a random thought often influenced by what they read, with no plan in mind (if they had one, they will not be asking). In this post, I discuss the effect of some market timing strategies based on market all-time highs.
If the market falls as you are reading this, blame it on the commentator’s curse (batsmen getting out when commentators talk about how well they are playing)! First, let us take a look at the Sensex.

So the red dots represent all-time highs. The Sensex is shown here in log scale. To understand the benefit of using log scale is see: Are you ready to climb the Sensex Staircase?! Most all-time highs are followed by further all-time highs. So to assume that the market will crash just because there is an all-time high is plain childish. Of course, one can ask, we find out at which all-time high the market is likely to crash? We will consider that in the next part of this series. Readers may recall that the above graph is part of this study: When the market is at an all-time high, how should a lump sum be invested? One-shot or gradually?
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
In this post, three types of profit booking (remove some equity portion) when the market is at an all-time high. You are likely to dismiss them as silly and involving too much work. I agree, but it is better to counter “should I book profit now since the market is at an all-time high” with data than opinions
Method 1: Invest systematically each month. Observe the value of the index or the NAV of a mutual fund indexed to the market. If current NAV or price is the all-time high, then rebalance the portfolio back to 70% equity and 30% debt (70:30) or to 50% equity and 50 debt (50:50). If the current NAV or price < all-time-high then do nothing.
Method 2: Invest systematically each month. Observe the value of the index or the NAV of a mutual fund indexed to the market. If current NAV or price is the all-time high, then rebalance only if equity is above 70% or 50%. If current NAV or price is < all-time-high, then rebalance only if equity less than 70% or 50%.
That is, when we hold excessive equity when the market is at an all-time, we book profit. If we hold less equity when the market is away from an all-time high, we add more equity.
Method 3: Invest systematically each month. If current NAV or price is the all-time high, then redeem 10% equity if the equity allocation is >40%. If current NAV or price < all-time-high then shift 10% debt to equity if debt allocation is > 20%.
The rules of the game are the same as all other tactical asset allocation posts. You can refer to the latest: Market Timing with the Motilal Oswal Value Index (MOVI) We use Franklin India Blue Chip Fund for the Equity component and
Method 1 (rebalance at each all-time high): Period = 10 years; Equity = 50% Fixed Income = 50%
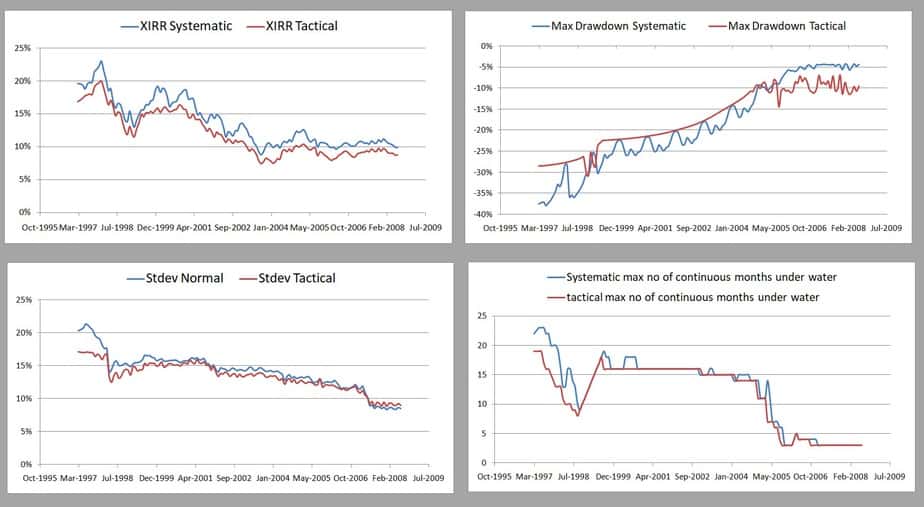
Top Left: The XIRR or returns are compared. Higher the better! XIRR tactical refers to method 1/2/3.
Top Right: The maximum fall of the portfolio from a peak is compared. The vertical axis is negative. So lower the value, the more the fall, the more the risk.
Bottom left: Standard deviation or how much the monthly returns fluctuate is compared. Higher the value, the higher the fluctuation, the higher the risk.
Bottom right: The no of months, the portfolio was continuously lower than a previous peak (underwater) is compared. Higher the no of months, higher the risk.
Method 1 (rebalance at each all-time high): Period = 10 years; Equity = 70% Fixed Income = 30%
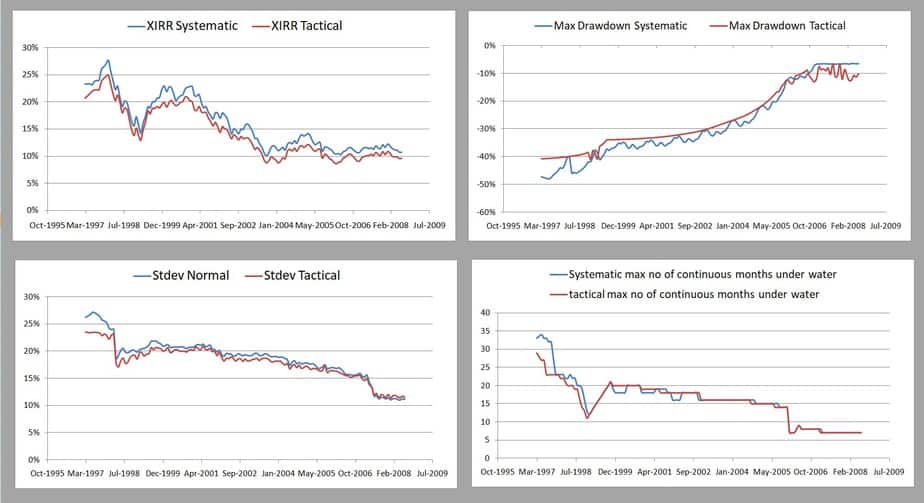
Method 2 (rebalance only excess equity at all-time highs): Period = 10 years; Equity = 50% Fixed Income = 50%

Method 2: Period = 10 years; Equity = 70% Fixed Income = 30%
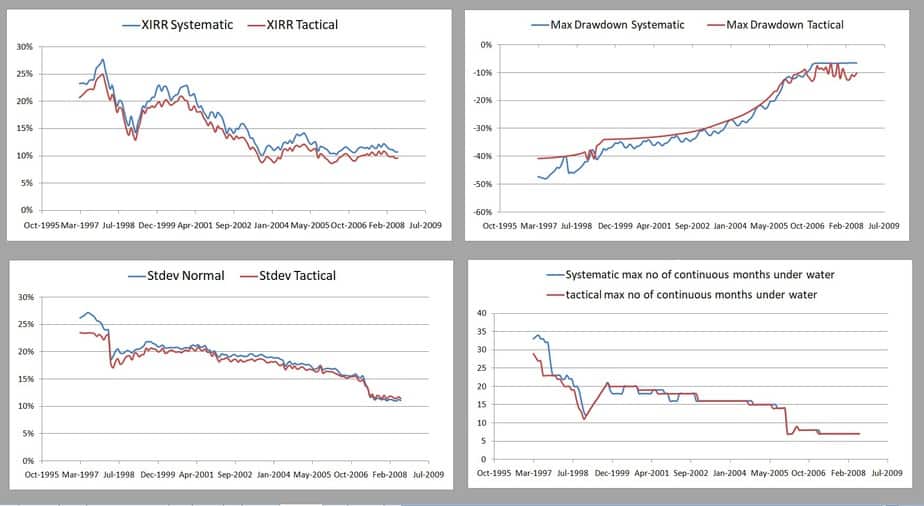
Method 3 (book 10% profit at all-time highs): Period = 10 years; Equity = 50% Fixed Income = 50%
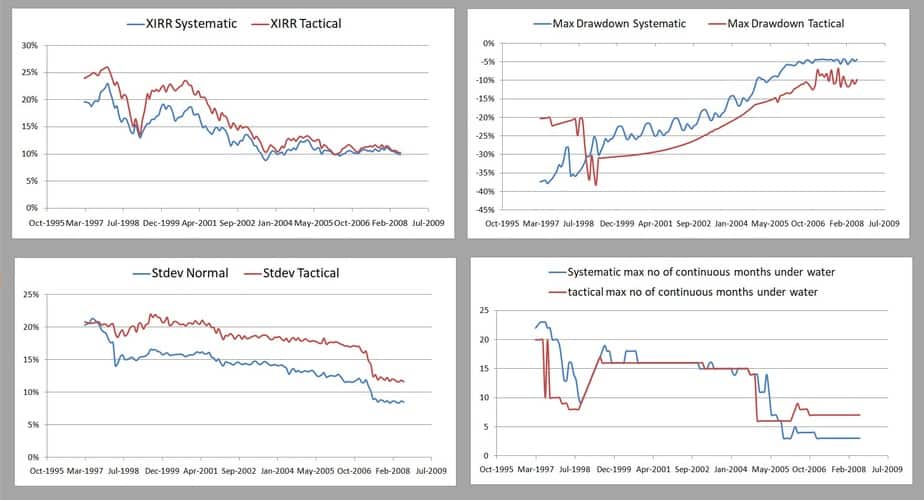
Method 3: Period = 10 years; Equity = 70% Fixed Income = 30%
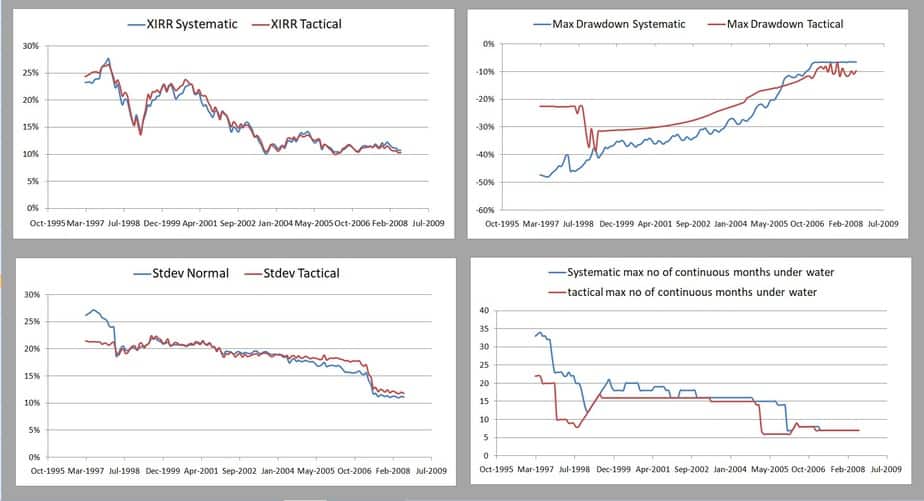
Method 3 (book 10% profit at all-time highs): Period = 5 years; Equity = 50% Fixed Income = 50%
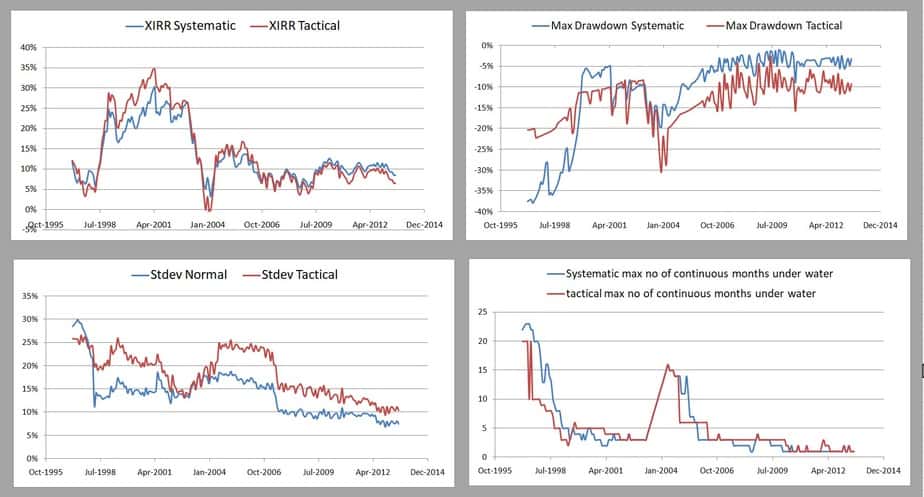
Summary
Wait. Did you scroll down all the way here ignoring the graphs just to see “if there is a clear message about what to do when the market is at an all-time high”? Then shame on you. If you took the time to view the graphs then, thank you.
Out of the methods tested, it should be clear (for those who bothered to stop and stare) that method 3 is relatively the most productive for the 50:50 case. However, are you willing book 10% of your equity or debt portfolio pretty much each month? It is not enough if you are “scared” about “all-time-highs”. Do you have the enterprise to come up with a plan? Do you have the will to execute? Do you the have the discipline to stick to it? If not, invest systematically and rebalance once a year with gradual goal-based equity reduction and forget about market-highs.
For the record, if you wish to time the market, there are many other methods available that involve less activity. Since we cannot say for sure if a timing model will produce higher returns than a systematic approach, two requirements are essential: the number of buy/sells should be minimized else too much will be lost to tax and loads. The volatility or at least the ma fall should be lower in the timing model (unless it designed to be a higher-risk approach). Although the quantum of buying and selling is lower in this all-time approach, the number of such events are too frequent (at least twice each quarter , if not each month).
To get something, you need to either do something or lose something. Random opinions (such as this post) will not help. Sadly most investors neither know what they want to get, let alone doing something or losing something. Sigh!