We explain why “guaranteed income plans” with “assured returns” are inefficient investment avenues for our money and are best avoided.
Benjamin Franklin wrote in 1748 that Time is Money in a note titled “Advice to a Young Tradesman“. Insurers use this idea to their benefit in all traditional insurance policies, including guaranteed income plans.
Consider a typical “guaranteed income plan” offered by many insurers. This promises to pay a “regular income” for Y no of years after the premium is paid for X no of years. This sounds so great on paper. Many people can’t find any “catch” in this illustration.
Say you need to pay a premium of Rs. 100 for ten years. Then over the next ten years, the insurer will pay you double the total amount of total premiums paid. You paid Rs. 100 x 10 = 1000 over ten years. It will pay you 2 x 1000 = 2000 over the next ten. Does it sound like a good deal?
We need to find out the internal rate of return (IRR or XIRR) to find out how good this is. IRR represents the annualised rate of return. Read more: CAGR vs. IRR: Understanding investment growth measures.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
The premium paid is written as a -100 to represent cash leaving your hand. The payout is +100 to represent a receipt. So you can see the cash flow for 20 years below.

Notice that the payout is only Rs. 100 for nine years (from 11 to 19). In year 20, the payout is Rs. 100 + Rs. 1000 = Rs. 1100, making the total payout twice the total premiums paid.
The IRR is 5.84%. Many people fall into the lure of guaranteed income without understanding the idea of IRR and how to calculate it. The formula used in Excel or Google Spreadsheets is indicated at the bottom.
If we had invested the money elsewhere, say in a portfolio of even 20-30% equity and the rest in fixed income, after ten years, buy a government bond or an immediate annuity plan (if we needed the income), we could quite easily beat this IRR post-tax. More importantly, we would have direct access to the entire capital at all times (before the bond purchase), and we would be free to do what we want with it.
The catch here is how cleverly insurers exploit the adage that time is money. What if the insurer paid you twice the amount of premiums in the 11th year?
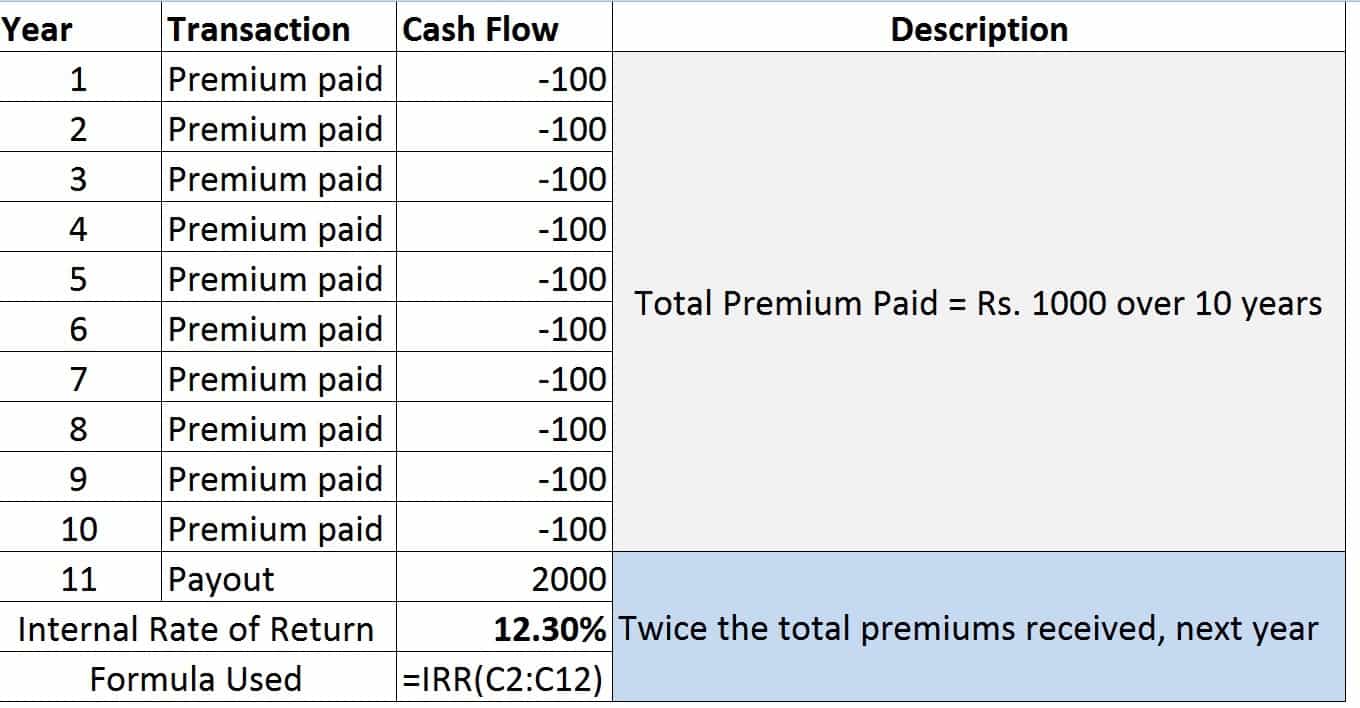
Well, if they did that, they would have to close down! Notice the huge difference in IRR. More than twice. This is the time value of money at work. When the payments are not immediate, you lose immensely, and they gain immensely. And we are not even considering the fact that the insurer can invest the premiums collected and earn a return on it over the many years they hold on to it. Where do you think the bonuses come from?!!
If you receive the payout immediately, not only is the return high, you can use it any way you want. If they delay payouts, they can use the funds in any way they want. That is the catch: Time is money!! This idea is also known as opportunity cost.
In context, it also means that liquidity matters! If the money is locked-in, we lose more than we know. In a sense, this proverb sums it up:
Of course, we do not claim that we can get a 12% return if we reinvest the premiums elsewhere. However, there is a reasonable chance we can beat 6% over the premium paying period.
Many argue that a “6% return is good, and I am fine with it.” A 6% return is good at the income generation stage and not at the wealth accumulation stage. We can invest the money in any way we want with full liquidity and then, as and when we need the income, buy an annuity or a bond, depending on our age and prevailing interest and annuity rates.
Some argue, “but I am locking in on a 6% return. If I buy an annuity after the premium 10Y, I may get a lower annuity rate”. We can easily compensate for this by achieving a higher lump sum. Also, many are not aware that annuity rates increase with age. So we may still get a better deal than prevailing FD rates ten years from now.
In summary, a guaranteed income plan is a bad buy because it unnecessarily combines the investment and income payout stages in life. By deploying our money elsewhere, we have a much better chance of generating higher wealth and income.