Often, readers ask us, “How do we plan for holidays abroad once in 2-3 years?
Our robo-advisor tool has a recurring financial goal calculator module, which you can use to plan for all such goals. This can be used to plan big-ticket annual expenses like school fees(!).
Suppose we wish to go on a holiday every two years. That is in 2026, 2028 and so on. Let us plan for 20 such holidays. Since this is not a mandatory goal, we can afford to take some risks using hybrid funds. Conservatively managed equity savings funds, conservative hybrid funds, balanced advantage funds, and dynamic asset allocation funds can be used.
Please note: Such funds can be used for future holidays. The funds for the immediate holiday can be kept safely in arbitrage funds, money market funds, liquid funds or in a good old bank account (SB account, FD, flexi-deposit account, etc.)
We can reasonably expect a post-tax return of about 7% from the above hybrid funds (all these settings can be changed at will in the back-end, but we recommend using conservative assumptions). Investment can be made via RDs, liquid funds, money market funds, or arbitrage funds for a more critical goal, such as school fees.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
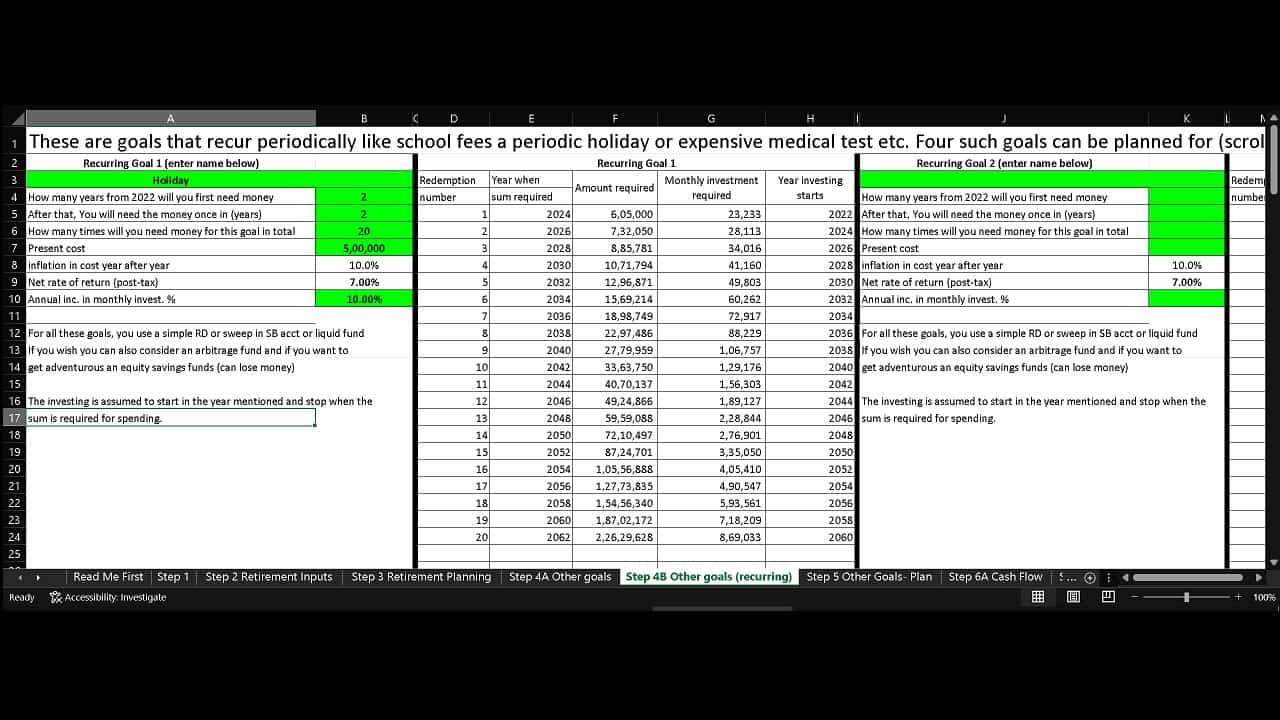
The inflation each year is assumed to be 10%. We shall also assume that the reader can increase his investments for this goal by 10% each year. We assume the current cost is Rs. 5 lakhs. This will change from destination to destination. If the maximum budget increases, the calculation should be redone.
We then get an output such as this. The investing is assumed to start in the year mentioned and stop when the sum is required for spending. Since the goal is recurring, only the investment amount changes! Essentially, you get a step-up SIP schedule that ensures you have enough corpus each time the goal recurs. A screenshot of the recurring goal calculator module is shown below.
| Year investing starts | Monthly investment required |
| 2024 | 28,113 |
| 2026 | 34,016 |
| 2028 | 41,160 |
| 2030 | 49,803 |
| 2032 | 60,262 |
| 2034 | 72,917 |
| 2036 | 88,229 |
| 2038 | 1,06,757 |
| 2040 | 1,29,176 |
| 2042 | 1,56,303 |
| 2044 | 1,89,127 |
| 2046 | 2,28,844 |
| 2048 | 2,76,901 |
| 2050 | 3,35,050 |
| 2052 | 4,05,410 |
| 2054 | 4,90,547 |
| 2056 | 5,93,561 |
| 2058 | 7,18,209 |
| 2060 | 8,69,033 |
This recurring goal calculator module screenshot is from the freefincal robo advisor tool. Four such goals can be accommodated.
While planning for recurring financial goals, investments for other long-term goals mustn’t be disrupted. A balance between the two is essential.