Last Updated on September 6, 2025 at 9:35 am
Everyone associated with a mutual fund says, “the best way to build wealth is via SIP in an equity mutual fund over the long term”. However, where is the proof that a long-term equity mutual fund SIP would work? In this article, we analyse 40+ years of the Sensex and 110 years of the S&P 500 to check if there is any truth to this claim.
To claim whether a long-term SIP in equity ‘works’ or not, we shall first have to define ‘long-term’ and the benchmark for the performance. We shall define ‘long-term’ as 15 years. This is well above what the MF industry defines as long term.
We shall consider a successful long-term equity SIP as one that provides a return well above the consumer price inflation (CPI). All data sources used in this study are linked below.
As we noted before, equity markets have no obligation to give you the return that you expect (most often incorrectly). It is “expected” to only beat inflation. See: Equity may beat inflation, but that doesn’t mean you will!
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
S&P 500 TRI vs Inflation (both in USD)
The 15-year rolling SIP returns for S&P 500 TRI and the corresponding 15-year CPI averages are shown below. All in USD (forex is not relevant here as we are considering a US resident). There are 1329 15-year data points in the graph. DIY investors who would like to create such rolling SIP data for mutual funds and indices can use the tools in the freefincal investor circle.
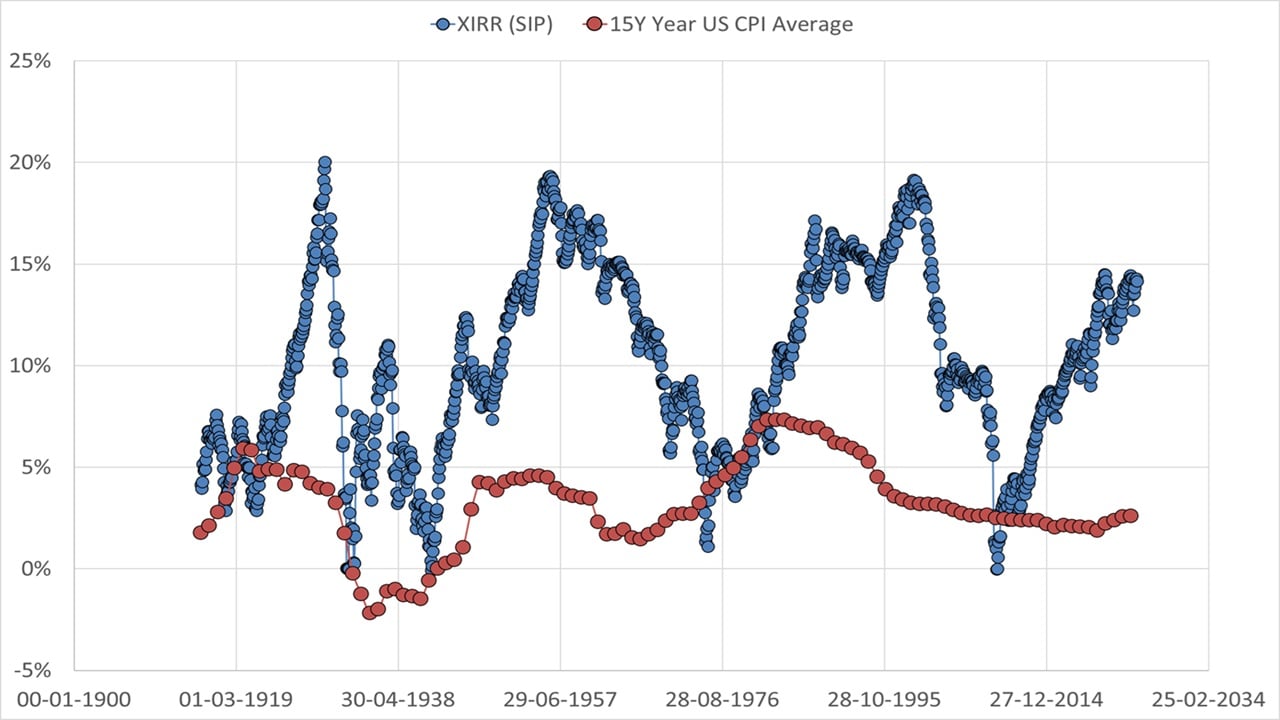
Even if the annual US inflation is about 5%, the SIP has done reasonably well. It has not been able to beat inflation every time, but that is perfectly understandable. Notice how much returns have fluctuated and their cyclic behaviour. Returns over 15 years have even been 0%!
Takeaways
- Long term equity investing has no guarantees of getting “good returns”.
- There is a reasonable chance that long term investing will beat inflation, but if your return expectation is much higher than inflation, then it is still a failure for you!
- A reasonable chance is more than what we get from most things in life, and if there is enough time to manage risk (assuming we know how), equity is a good choice for the long-term. However, do not get carried away with what the MF industry tells you and keep your expectations low.
- Most important! Never take the average of a rolling return curve. It is a curve that shows you risk (via return spreads) and outperformance. Knowledge is knowing the formula for the average. Wisdom is appreciating when not to use it!
Sensex vs PPF vs CPI (all in INR)
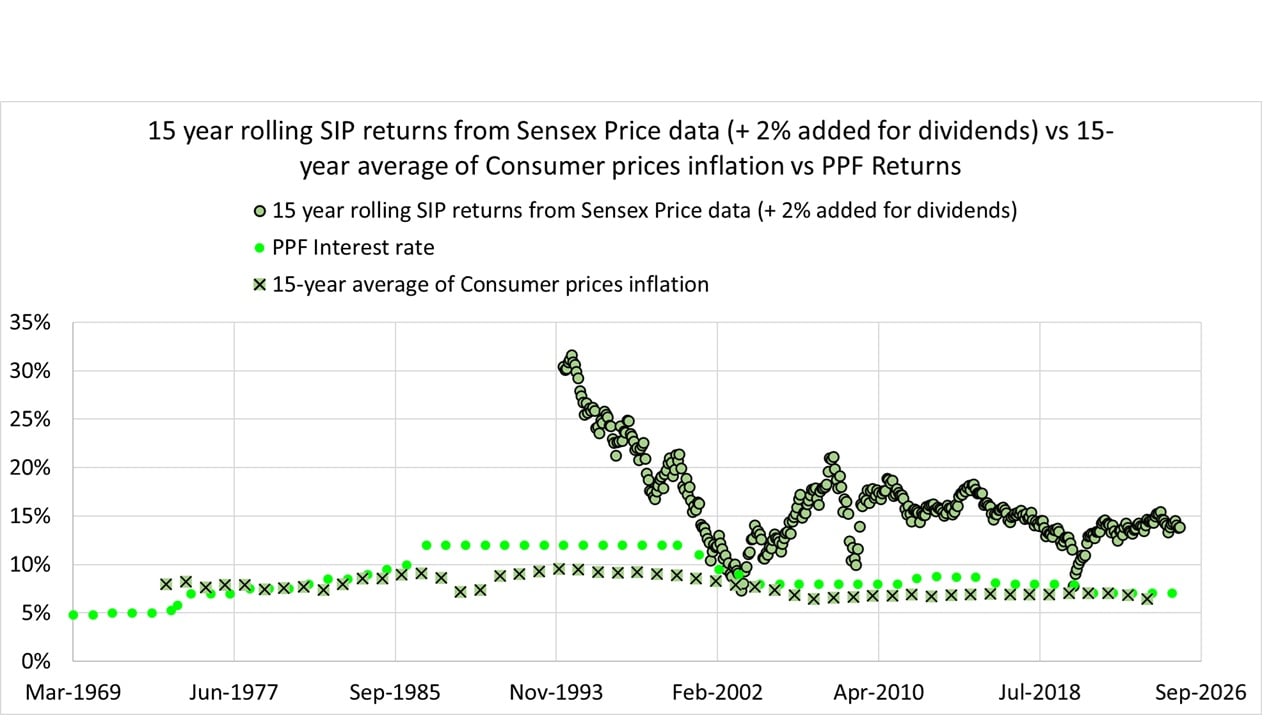
We have Sensex price data from 1979, but TRI data only from 1999. Therefore, we use the price returns and add a (generous) 2% contribution to the returns from dividends. The PPF returns, and the 15-year average of the CPI inflation is also shown.
Notice that the PPF rate has often been higher than the long-term CPI average, particularly in the 90s when the Indian government was on the brink of bankruptcy. If we compare our personal inflation rate, it would be closer to the PPF rate than the CPI!
The 15Y SIP has comfortably beaten the CPI and the PPF, although not always, which is quite acceptable. Notice that the cyclic nature seen in the S&P 500 data is not fully manifest for Indian equity due to the short history.
‘Asset class win’ vs ‘investor win’
The reader should appreciate the difference between an investment in an asset class succeeding and an investor succeeding. We are not referring to behavioural issues.
Suppose the 10-year average CPI is, say, 3% (prices in USD). If the return from a 10-year SIP in S&P 500 (aka dollar-cost averaging) is 4% (in USD, before tax), the asset has ‘won’. That is, the asset class got a positive real return.
(1+ Real return of the asset class) = (1+asset class return)/(1+inflation)
The question is, did the investor who got this 4% return over ten years also win?
We will have to pull out the “it depends” card for this. There are several considerations.
- How much return did the investor expect? If they wanted more than 4%, they would have invested less, which would have led to disappointment.
- Even if they are happy with 4%, taxes will reduce the “real returns” to 0% or negative, which is a disappointment.
(1+ Real return of the investor for an asset class) = (1+post-tax asset class return)/(1+inflation)
- Unfortunately, there is no. No one is going to invest only in equity. So the asset allocation matters. An investor expecting higher returns from an asset class will tend to hold more of it in the portfolio. In other words, if the actual return is lower (before or after-tax), the disappointment will be higher.
This is the reason why an asset class’s success is not the same as an investor’s success. This can be called the “expectation gap” – the difference between what we expected and planned for and what we actually received, despite regular investing. If can reduce the expectation gap from day one, we can simultaneously reduce the behaviour gap. Why? The best way to reduce panic and emotional decisions is to have a solid plan in place.
This differs from the “behaviour gap,” which refers to the difference between what the equity market provides and what the investor receives due to systematic underinvestment, panic selling, and other factors.
The key takeaway is that while equity is the right asset class to fight inflation, there are no guarantees of success. If you blindly invest each month, then you are leaving the fate of your investments to luck. Undoubtedly, your money deserves better treatment, even if you don’t!
The spread of possible returns is too much to expect something comfortable and live in hope. Systematically investing is not enough; systematically managing risk in a goal-based manner is essential.
Conclusions
When we set out to ask, “Does long-term equity-SIP investing work?‘ we have a two-step process to cover. Does the asset class beat inflation more often than not over ten years or 15 years? The answer is ‘yes’. This makes equity the right choice for dollar-cost averaging or SIP investing (this means investing at some comfortable interval and not monthly).
However, we saw that 10Y or 15Y years of systematic investing do not yield a consistently high return. The returns can swing wildly, and where we have a long enough market history, the returns exhibit a wavy/cyclic pattern (up followed by down). This means if the investor makes the mistake of expecting a high return and/or has high exposure in the portfolio, then long-term equity SIP investing will not work!
So the choice of the asset class (equity) is correct, but choosing the right asset allocation that can handle sequences of returns risk remains. If this is not done correctly, an inflation-beating return could still turn out to be a disappointment.
Data Sources
- S&P 500 TRI Data from 1900 (the inflation adjustment was removed for this study)
- US CPI data
- India CPI data
- PPF interest rate history