Last Updated on February 12, 2022 at 6:32 pm
Use this free EMI Moratorium calculator to understand how much you would lose (pay extra interest) if you opt for the three month EMI holiday offered by your bank under the directions of RBI.
We have already discussed why you should not opt for RBI’s EMI moratorium & defer loans by 3 months. Here is how EMI holiday works. First, let us understand how loan amortization works. That is, how a loan gets paid off. Those interested in a flexible loan amortization spreadsheet can get one here: Excel Home Loan Amortization Schedule Template. The EMI Moratorium Calculator in this article is derived from this template.
Once the EMI for a loan is calculated – just like an MF SIP: Understanding Loan EMI Calculation as a Monthly SIP Investment! – it has two components: the interest which is equal to outstanding balance x (loan interest/12) and the rest of the EMI is the principal.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
After each EMI is paid, the principal component is deducted from the loan outstanding. While the EMI is constant each month, the principal and interest components change as shown below.
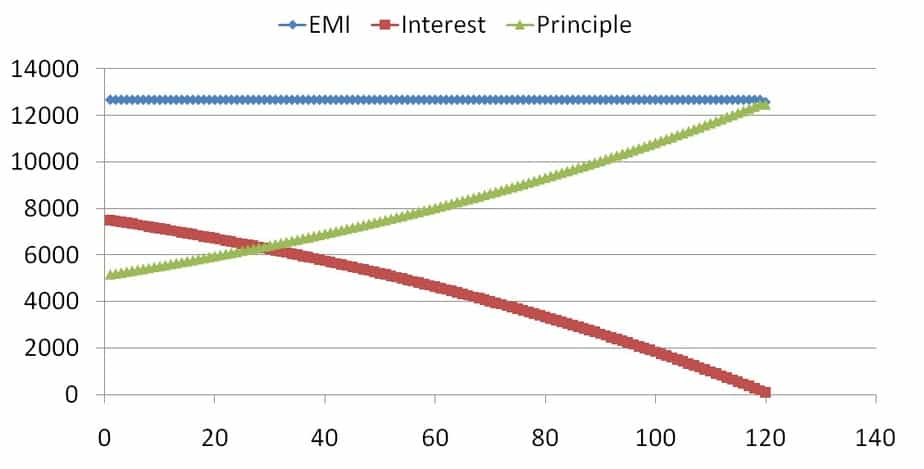
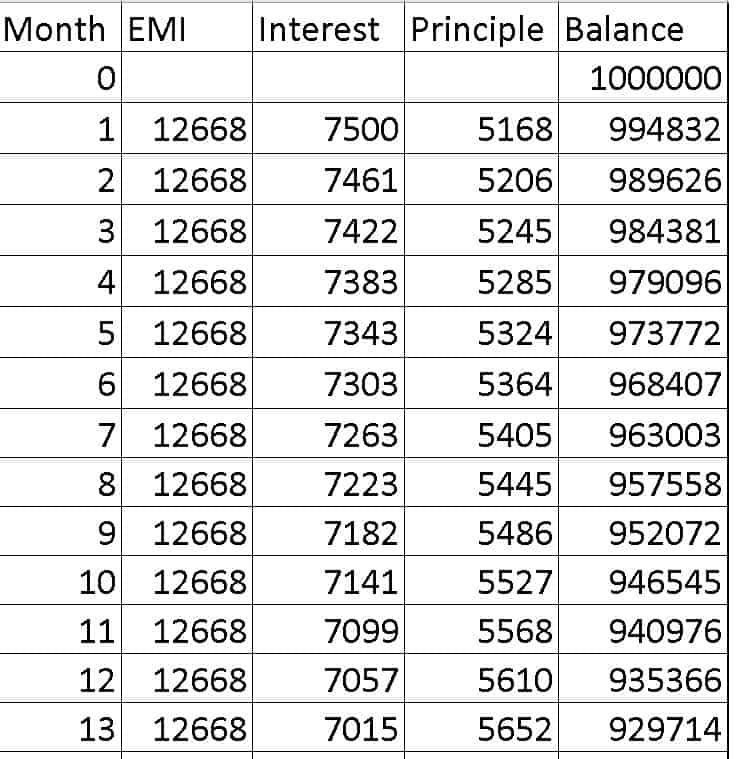
These are the associated numbers. Initially, the EMI is dominated by the interest
How EMI Moratorium Works
Suppose we avail the EMI moratorium offered by the bank for the 7th, 8th and 9th months. That is the EMI for those months is set to zero. However, the interest will accrue.
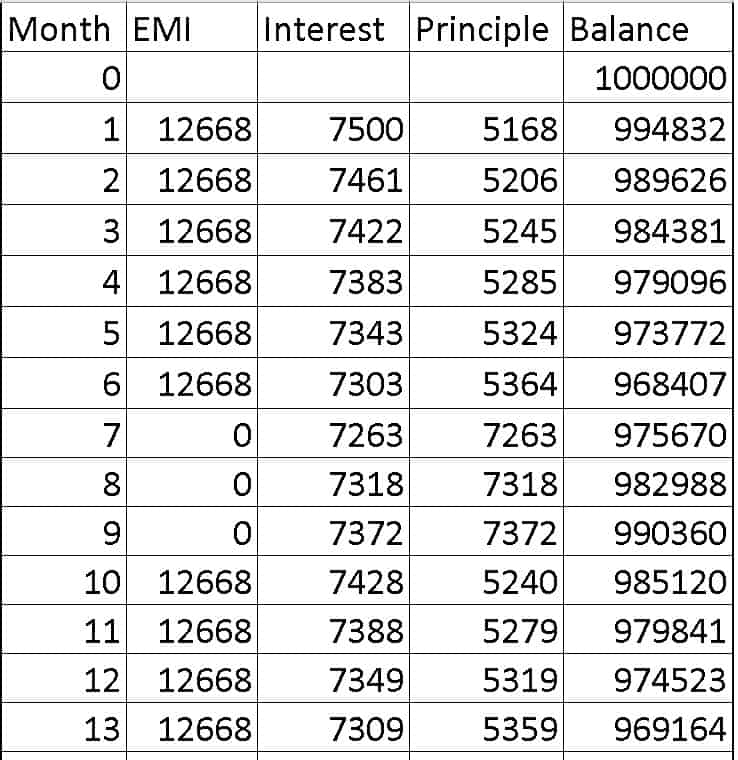
For the 7th month, the interest on the outstanding balance of Rs. 9,68,407 in the 6th month is Rs. 7263. This gets added to the outstanding balance in the 7th month and becomes part of the principal.
For the 8th month, the outstanding balance is Rs. 9,68,407 + Rs. 7263 = Rs. 9,75,670. The interest on this amount is Rs. 7318 which gets added to the balance.
For the 9th month, the outstanding balance is Rs. 9,75,670 + Rs. 7318 = Rs. 982988. The interest on this amount is Rs. 7372 which gets added to the balance.
Now in the 10th month, the EMI resumes. You could ask the bank to increase the EMI and the loan would end as planned or you could pay the same EMI and the loan would get extended. The calculator only considers the latter possibility: same EMI, longer loan tenure. For the numbers shown above, the loan would get extended by 8 months and the excess interest to be paid = 4.14 times the EMI!
This is why banks would happily offer the moratorium or even set it by default! They earn more! This is why you should never accept the moratorium! If your cash flow situation is so bad that you cannot pay the next three EMIs then you may not pay EMIs after the EMI holiday as well! The spirit of the EMI moratorium is lost. Never opt for it!
EMI Moratorium Examples
Example 1
- Loan amount: 10 lakhs
- Loan Tenure: 10 Years
- Interest rate: 9%
- The month when moratorium starts: 7
- Excess interest to be paid if you avail moratorium: Rs. 52,457
- The loan will be extended by (months): 8
- Excess interest divided by EMI: 4.14
Example 2
- Loan amount: 10 lakhs
- Loan Tenure: 10 Years
- Interest rate: 9%
- The month when moratorium starts: 45
- Excess interest to be paid if you avail moratorium: Rs. 29,650
- The loan will be extended by (months): 6
- Excess interest divided by EMI: 2.34
- Since the EMI has lesser interest component in the 45th month than the 7th month, the loss is lower.
Example 3
- Loan amount: 10 lakhs
- Loan Tenure: 5 Years
- Interest rate: 12%
- The month when moratorium starts: 10
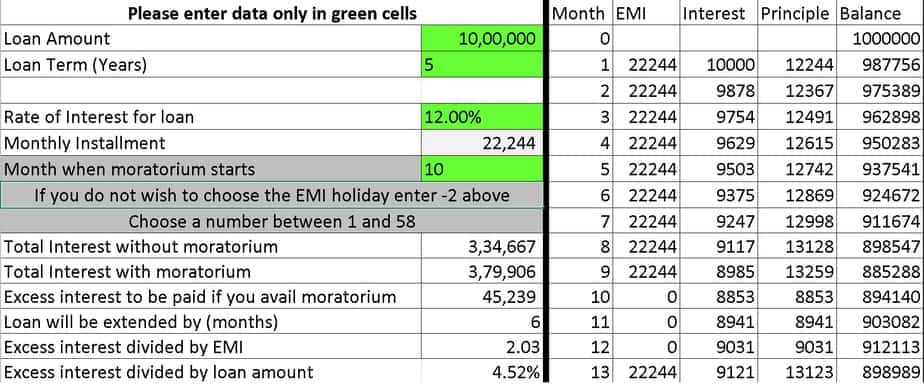
- Excess interest to be paid if you avail moratorium: Rs. 45,239 (4.5% of the loan amount)
- The loan will be extended by (months): 6
- Excess interest divided by EMI: 2.03
Example 4
- Loan amount: 2 lakhs
- Loan Tenure: 2 Years
- Interest rate: 25%
- The month when moratorium starts: 2
- Excess interest to be paid if you avail moratorium: Rs. 20,452 (10.23% of the loan amount)
- The loan will be extended by (months): 5
- Excess interest divided by EMI: 2.03
EMI Moratorium Calculator
This is the screenshot of the calculator with input cells in green.
Download version 2 of the EMI Moratorium calculator (updated 3rd April 2020)
(This is version 1 here you can only set 3 EMI holidays)
References
- Circular from SBI
- Circular from ICICI Bank