Last Updated on March 4, 2023 at 2:54 pm
Apurba and his wife are new parents who would like to know how they should plan and start investing for their daughter’s future. An illustration.
Their daughter is only about a week old. Starting early and starting right is the most important step in securing a future for our child. Some people would say “take it easy and enjoy the newborn”. That is fine but the following planning will take no more than an hour to conceive and another hour or so to execute. There is no need to postpone it any more than necessary. Let us break down the task into steps,
- We need a target corpus to achieve after 17 years (or 18 years depending on when she was born). That is after school graduation.
- Some parents ask, “But what about school fees and other coaching fees?”. This better be funded from monthly income or you are in trouble! When we refer to the child’s future here, it will only refer to the UG fee, PG fee, relocation expenses and if the parents see fit, marriage expenses.
- Let us first set the target corpus = UG fee. The corpus can easily be enhanced to include other expenses. A UG fee of Rs. 1.5 lakh per semester x eight semesters + a joining fee of Rs. 5 lakh + another Rs. 5 lakhs for relocation, travel etc. sounds about right to us. You can make enquiries and set a target too.
- So that is about Rs. 22 lakhs. Make that Rs. 25 lakhs as the current cost. That is if your child were to enter a four year UG program today, that is what it would approximately cost.
- Now, what is the likely cost after 16/17/18 years as the case would be for your child when we start planning?
- We will use inflation of 10%-12%.
- At 10% inflation, the corpus will be about Rs. 1.25 crores after 17 years.
- Suppose the parents can invest Rs. X each month for this goal. About 50-60% of X should be invested in stocks or equity mutual funds assuming a post-tax return of 10% from equity.
- The remaining amount can be invested in debt instruments with a return of about 6% Remember this is not the return you are going to get the next year. This is the return you expect after 17 years.
- But which debt instruments? We recommend PPF and debt funds for the daughter’s education and Sukanya Samriddhi Yojana (SSY) for her marriage (if that is something important to you). Keep in mind that you can withdraw 50% of SSY corpus for education only if the girl has turned 18. Many children get admitted to colleges before that. Also, there is only a 0.5 return difference between PPF and SSY. This is insignificant in an equity-heavy portfolio.
- The above-mentioned future target corpus is only for UG education. If you wish to include her PG education expenses, marriage expenses etc. please modify as required.
- What is more important is asset allocation after we start investing. We cannot hold on to 50% or 60% for most of the journey. A string of poor returns will upset our plans. Entering the above details into our robo advisory tool, we get: 60% equity for 7-8 years and then a gradual tapering down to 0% for the rest of the journey. Many goal calculators use a single future return expectation as input to compute the monthly investment required. This is incorrect as the asset allocation will vary.
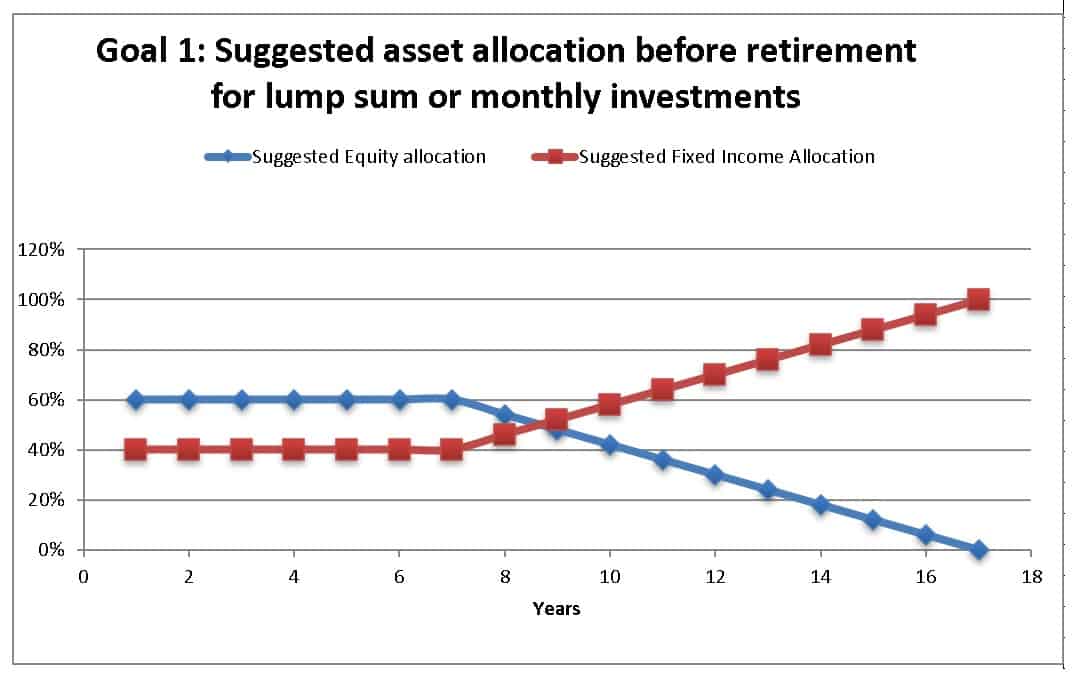
Suggested asset allocation by the freefincal robo advisory template for a child’s college education 17 years away. - With this variable asset allocation, the total monthly investment required in the first year of investing is Rs. 15, 500. Each year after this, the investment should be increased by 10%.
- Do not rush to invest Rs. 1.5L a year in PPF just because it is tax-free with a guaranteed return. In the above plan, the total investment in debt will only be Rs. 74 K. In fact until the equity allocation starts decreasing as mentioned above, the debt investment will not exceed Rs. 1.5 L a year. After this, a debt mutual fund may be added to accommodate the higher debt investment.
- Each year, the above calculation should be repeated with updated inputs and assumptions.
All the best!
For other illustrations see:
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
- I am 30 and wish to retire by 50 how should I plan my investments?
- Retirement plan review: Am I on track to retire by 50?