A reader asks, “Can I add 10% to 20% gold to my investment portfolio? My need is in 15 years? Is it possible to do backtest to find out how a portfolio with gold fares against a portfolio without gold?
The short answer to this question is one can certainly add 10% to 20% of gold to a long-term investment portfolio. However, there are some caveats to be kept in mind. This article will present backtest results, but the backtest itself has an issue.
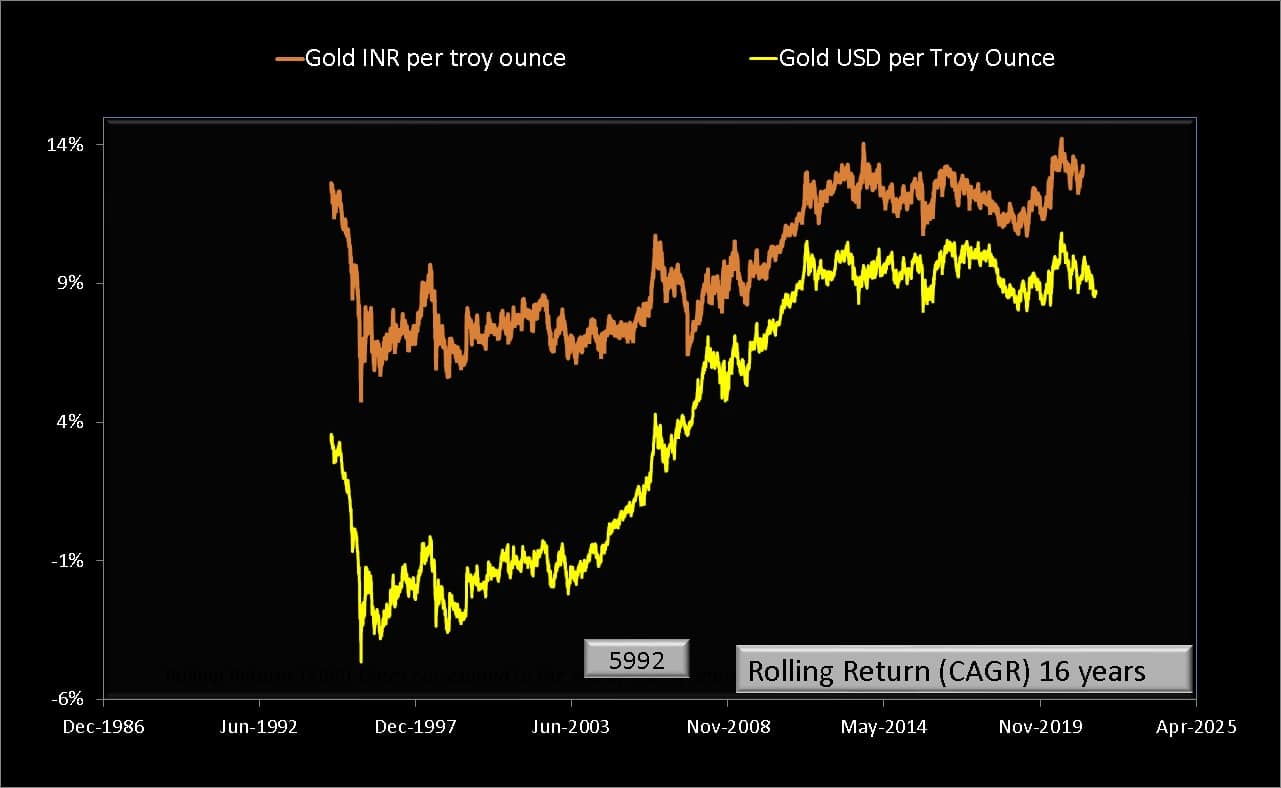
Gold returns in the past are dominated by the USD-INR exchange rate. In particular, the exchange rate zoomed up when the economy opened up in the nineties. Gold INR returns recently have been in step with Gold USD because our currency is more stable now.
This can be seen in the rolling return chart below. So a backtest that shows a with-gold portfolio outperforming should not be taken too seriously as a repetition is unlikely – unless the country is in serious trouble.
For more charts and perspectives, see Gold Price Movement: USD vs INR.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Now, we can run a backtest comparing two portfolios:
- 60% Equity (Sensex TRI) and 40% (long-term) gilts (IBEX I-Sec index)
- 60% Equity, 10% or 20% of gold INR and the rest gilts.
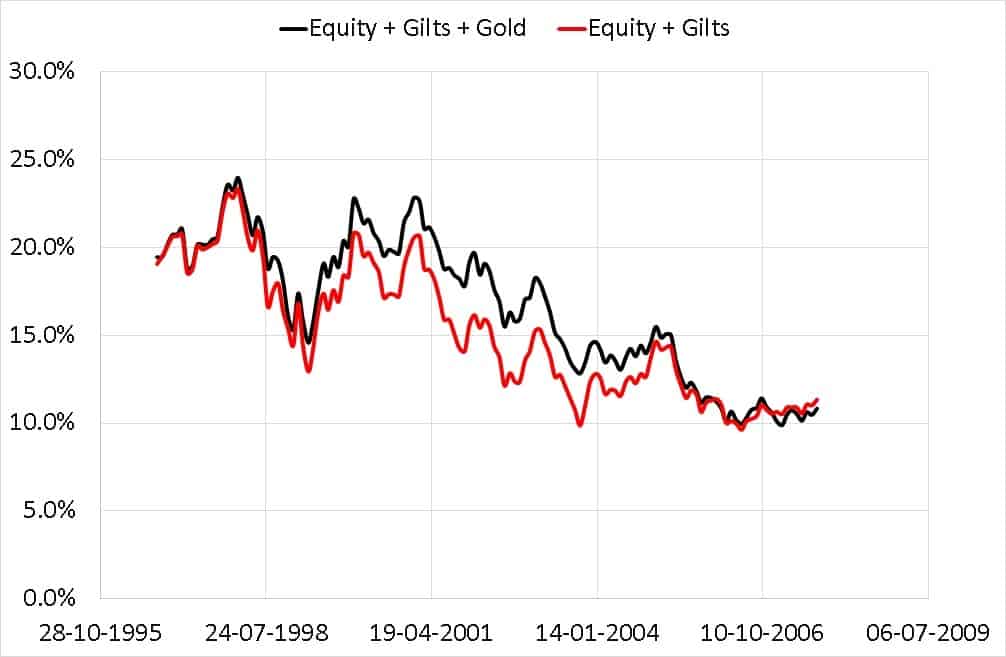
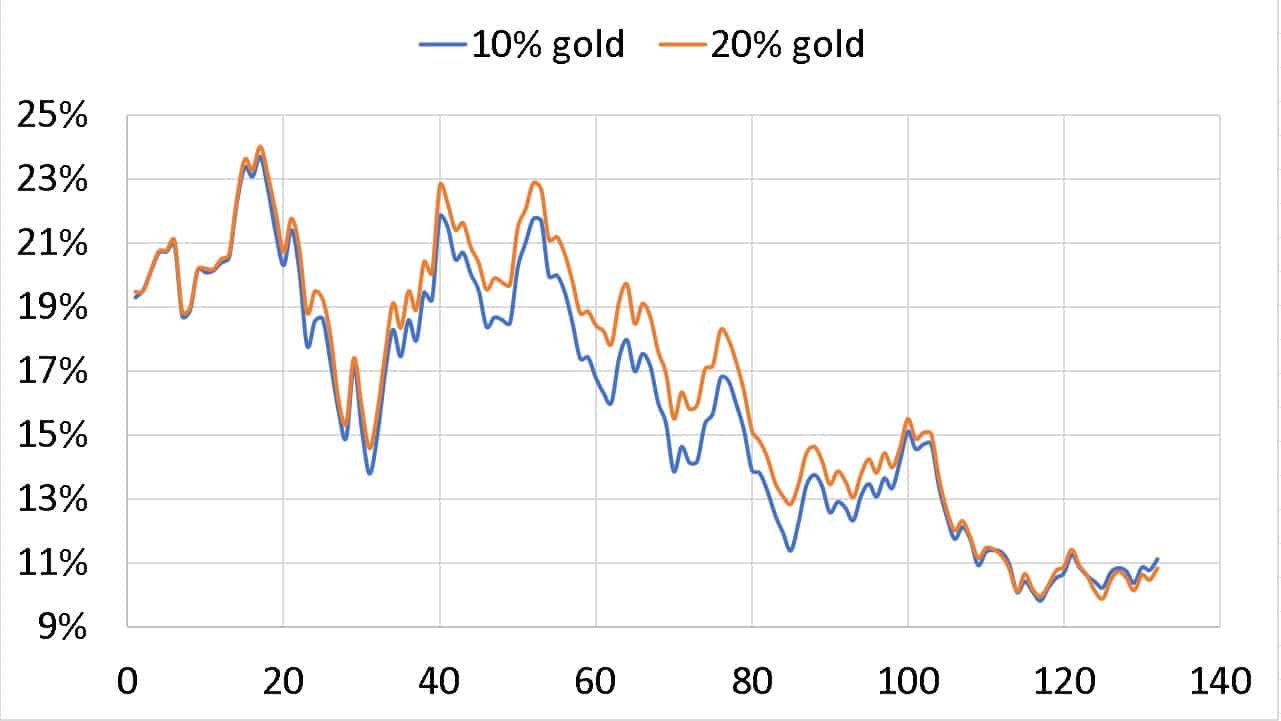
The simulation is from Sep 1996 to Aug 2022; 132 15-year runs are possible. We shall assume both portfolios are rebalanced annually. The XIRRs for each run for both portfolios are shown before.The start date of each run is shown in the X-axis.
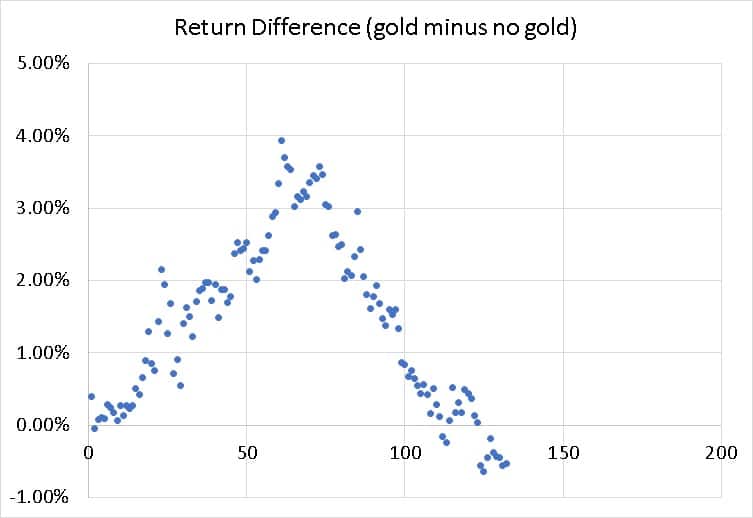
The return difference for each run is shown below; 75 out of 132 runs have a return difference of more than 1%. That is, 75 out of 132 runs, the with-gold portfolio had a return 1% higher than the without-gold portfolio.
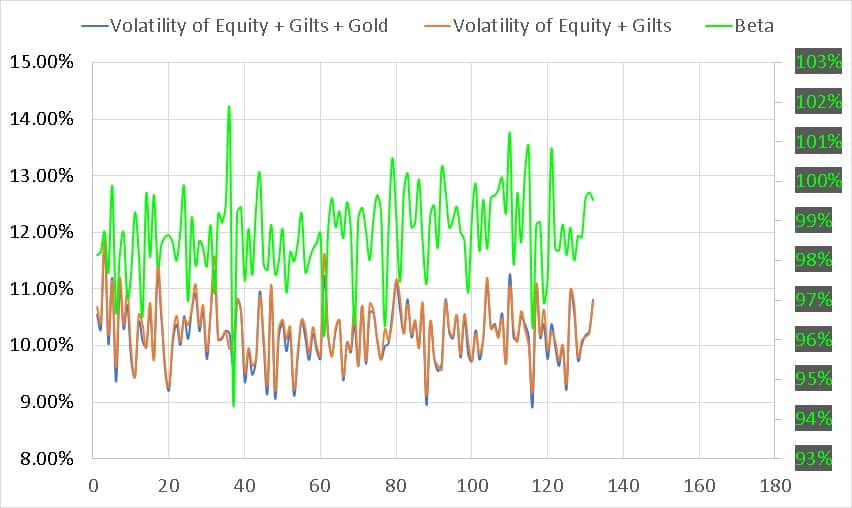
The volatilities of both portfolios and the beta with respect to each other are plotted below.
Impression:
- The with-gold portfolio has typically outperformed the without-gold portfolio.
- However, the margin of outperformance is significant (> 1%) only for about 56% of the runs.
- There is not much difference in the volatilities of both portfolios as measured by the standard deviation. This is also seen in the relative beta.
- The with-gold portfolio has not always outperformed; more importantly, it has not outperformed for the last 17 years! This is most likely due to the stability of the INR, as mentioned above (many believe our currency is a lot weaker than it actually is!)
- Interestingly, there is not much difference between holding 10% gold and 20% gold. Only in 42 out of 132 runs did the 20% holding outperform by more than 10%.
Is it worth investing in 10-20% of gold for a long-term portfolio?
- There is no harm in doing so, but one must not do it under the assumption that they are sure to do better than a without-gold portfolio.
- An equity+ gilt portfolio has often done just as well without higher volatility.
- The annual rebalancing will require more effort in the with-gold portfolio. Although it may not need to lead to higher tax, it is certainly a higher effort. Most investors fear to rebalance, fearing the process and tax with just equity and debt. Three asset classes will only make it harder for most.
- Gold INR is significantly more correlated with gold USD now, and the past high returns of gold are unlikely to be seen again.
- If equity is an asset class driven by optimism, gold is often driven by pessimism and fear. During extended bull markets, gold can go through years of poor returns. So it would be frustrating to hold it.
- Gold does not always offer a reward commensurate with its risk. See: Gold vs Equity (Sensex) 40-year return and risk comparison.
Taking all this into consideration, our recommendation is to avoid gold for long-term goals. There is, however, one proviso. The above results are valid with long-term gilts. If one were to use 1-year gilts (as a proxy for liquid funds or money market funds), then gold’s outperformance (> 1% return difference) becomes significantly more frequent (105 out of 132 times). In our opinion, this should not be interpreted as the suitability of gold with short-term debt. Rather, it suggests that long-term debt (due to its volatility) is better than short-term debt for long-term goals.