Last Updated on December 29, 2021 at 6:32 pm
A reader asks, “how can I regularly withdraw every year, say 7 per cent per year, from the corpus in my 18-year-old PPF account towards my yearly expenses”.
There are two aspects to consider here: technical feasibility and practical feasibility. Once a PPF account has completed 15 years, there are two ways to keep it alive: (1) Without further contributions (interest will be paid) and (2) with contributions.
It must be understood that “extending a PPF account” account implies option 2 with contributions every five years. This option must be exercised within one year of maturity. After this, an “extension” will not be possible.
Option 1 without contribution is not an “extension”, and the subscriber can withdraw any amount once every financial year until the corpus is fully depleted. A new ppf account can be opened only if this is closed.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Since the reader is looking for regular income from PPF to the extent of the interest received, we shall assume he is interested in “extending” the PPF account with contributions (Rs. 500 min per year) for five years periods. This is done via submitting “form H” to the post office or bank.
In this case, yearly withdrawals are possible. However, the total amount withdrawn during the five-year block should be less than or equal to 60% of the balance at the start of this block.
For example, let us assume we have extended a PPF account for five years with a balance of Rs. 40 lakhs. We shall keep it alive with Rs. 500 a year (this is small compared to the balance and shall be ignored in the illustration). We shall assume that the interest during this period is 7% a year (this can change every quarter). We assume a withdrawal equal to 7% of the outstanding balance is made at the start of each financial year.
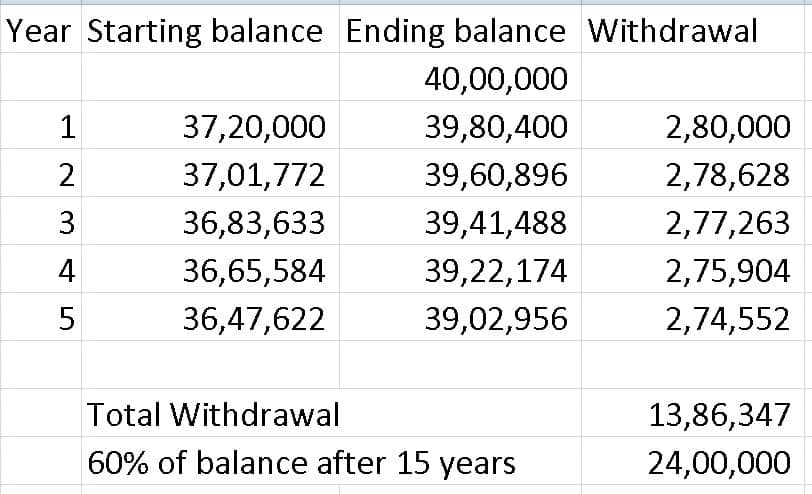
The total withdrawal made in the five-year block is Rs. 13.86 lakhs. The maximum amount that can be withdrawn over the five-year period is Rs. 24 lakhs = 60% of Rs. 40 lakhs the balance at the start of the extension period.
So the 7% withdrawals can easily be pulled off. Even if the PPF interest rate keeps decreasing by 1% every five years, the 7% annual withdrawal can be continued without breaching the maximum allowed limit. Naturally, the PPF corpus will also keep diminishing!
It must be understood that this discussion is only about PPF withdrawals and not about trying to beat inflation after retirement with income from PPF. Since the maximum that one can invest in PPF is only Rs. 1.5 lakh a year, the maximum corpus that can be attained after 15 years is limited (even with a constant interest rate) and therefore the maximum withdrawal is also limited – typically much smaller than a retiree’s annual expenses. PPF can be in principle used as one source of income from a diversified retirement portfolio.
Sadly, there is a catch. The plan may be technically feasible but may not be practically possible. Members from Facebook group Asan Ideas for Wealth point out that many banks do not encourage unlimited five-year extensions although it is legally allowed! The subscriber is often forced to close the PPF account after the second or third five-year extension. The situation with post offices is not known.
Therefore “regular income” from PPF (small as it is) cannot be considered as a reliable source.