Last Updated on July 12, 2017 at 11:24 pm
A friend asked me this question: “I currently have an asset allocation of 60% equity and 40% fixed income. My retirement is many years away. Why can’t I continue to hold 60% equity after retirement too? In fact, all my life?”. Since the answer is not a simple “yes” or “no” and since it can illustrate certain aspects of reviewing the strength of a retirement corpus before or after retirement, let us discuss this with the aid of an example.
Consider a 30-year old whose current average monthly expenses (that will persist after retirement) are about Rs. 30,000.
We will assume that she will invest in 60% equity and 40% fixed income (debt) up to age 60 and retire on her 60th birthday.
Post-tax return expected from equity: 10%
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Post-tax return expected from fixed income: 7%
Each year, her total monthly investment say is, X% of her monthly expenses (X to be varied as below). Sixty percent of this goes to equity and rest to fixed income until she stops earning.
This is only an illustration. Realistic asset allocations should be changed for most people as retirement nears. Hopefully, this post will serve as an example as to how this change has to be made to decide equity exposure post-retirement.
No rebalancing is done and she lets the equity and fixed income corpus grow without interference.
Post-retirement interest rate (post-tax) assumed = 7% (30 years from now, this seems like a safe assumption)
Inflation = 6% (probably an underestimate, but please play along. You can always use different numbers)
Example A She invests 30% of her monthly expenses each year.
This represents an annual increase in monthly investment of 6%.
At the time of retirement, the fixed income corpus is about 29% of the total corpus.
Now she rebalances at sets equity = 60% and fixed income = 40%
Now, at 7% return and 6% inflation, she asks, What is my (rebalanced) fixed income corpus worth?
Or in other words, if she wishes to generate an income to meet monthly expenses that increase each year at the rate of 6% (assumed inflation), while the rest of the corpus grows at 7% p.a. how long will the fixed income corpus last?
Using the Four Simple Retirement Planning Tools, the answer is: approx. 6 years.
Now to put this into context: If she wants to generate safe income from 40% of the total corpus while 60% of it is invested in equity, then after 6 years, she will have to dip into the equity corpus.
Is this a sound strategy? NO in my opinion. That large a corpus is exposed to significant risk with redemptions necessary from the 6th years onwards. If there is a huge crash either within 6 years or even later, her financial security in retirement will be under threat.
So if she invests only 30% of the monthly expenses, she cannot afford to have 60% equity exposure after retirement.
In fact, I don’t think she can have any equity exposure. Her initial withdrawal rate
= annual expenses (first year in retirement)/Total corpus = 7%.
This is extremely high.
Even if she invests the entire corpus at 7% and withdraws money for expenses increasing at 6% a year, it will only last her up to age 75 (15 years) – not bad, but not great either.
This is the classic catch-22 situation in retirement planning:
Take some risk (equity exposure) and stand of chance of becoming financially insecure sooner vs Take no risk (buy an annuity) and lose the battle of managing inflation and lifestyle creep.
In my opinion, many financial advisors in India are not qualified to handle this kind of situations and tend to offer crappy solutions like SWP from balanced funds or monthly dividend options without recognising risks.
Example A She invests 50% of her monthly expenses each year.
All other parameters and actions being the same, 40% of the final retirement corpus will last close to 10 years if an inflation-protected income is drawn from it.
Now, can the rest of the corpus (60%) be exposure to equity after retirement? It now has about 10 years to grow (hopefully untouched).
Question is, is there a need for any equity exposure?! Even if the entire corpus earned 7% return with withdrawals increasing at 6% p.a. it would last for 26 years.
So the equity exposure necessary is only about 10-25%. This is a fantastic place to be in and is the result of systematic investing for 30 years before retirement.
High(er) equity exposure (not necessarily 60%, but even 40%) is a cat-on-the-wall kind of situation and requires active management to reduce risk.
Example C She invests 100% of her monthly expenses each year.
No prizes for guessing the results here. If she invests as much as she spends (I strongly recommend this and practice 2 to 2.5X expenses), then she needs no equity exposure at all after retirement and therefore can afford to hold 60% equity after retirement (Does that make sense?)
If she invests 100% of the corpus at 7% and draws income increasing at 7% p.a. it would last her 62 years!!!
If she invests 40% of the corpus at 7% and draws income increasing at 7% p.a. it would last her almost 21 years!!!
So now she has the luxury to invest the rest in equity. With minimal risk management, she can happily grow that part of the corpus and leave behind a sizeable estate to her loved ones.
Please note: The scenarios depicted here are simplistic and only try to answer “how much equity exposure can I have after retirement?”.
You can use this calculator to punch in your own numbers.
Download the how much equity can I have after retirement calculator
Note: The sheet does not exactly answer this question. It only tells you the number of years one can be drawn an inflation-protected income from the fixed income portion of the corpus. From this, it is up to the user to draw inferences about equity exposure based on the risk profile of the corpus and their risk appetite. It is not an easy question to answer.
Download free E-book: Post-retirement income generation strategies
We are on Google News
Use this button to add freefincal.com as a preferred personal finance source on Google News.
Explore 1,400+ videos on YouTube!
Subscribe to get posts via email!
Join 32,000+ readers and get free money management solutions delivered to your inbox! (Link takes you to our email sign-up form)Join our WhatsApp Channel
Explore our products
🔥Join our community of 9000+ users! 🔥- Use our Robo-advisory Tool to create a complete financial plan! More than 3,500 investors and advisors use this! Use the discount code robo25 for 20% off. Plan your retirement (early, normal, before, and after), plus non-recurring financial goals (such as child education) and recurring financial goals (such as holidays and appliance purchases). The tool helps anyone aged 18 to 80 plan for retirement, plus six non-recurring and four recurring financial goals, with a detailed cash flow summary.
- Our Flagship Course! Learn to manage your portfolio like a pro to achieve your goals regardless of market conditions! More than 3,500 investors and advisors are part of our exclusive community! Get clarity on how to plan for your goals and achieve the necessary corpus no matter the market conditions! Watch the first lecture for free! One-time payment! No recurring fees! Lifelong access to videos! Reduce fear, uncertainty and doubt while investing! Learn how to plan for your goals before and after retirement with confidence.
- Join the freefincal investor circle! An exclusive space for investors, advisors, fintech employees and students to access financial planning and insurance tools, mutual fund and stock analysis tools, coding strategies and Excel macros for data extraction. 750+ members are now part of our investor circle.
- Increase your income by getting people to pay for your skills! More than 900 salaried employees, entrepreneurs and financial advisors are part of our exclusive community! Learn how to get people to pay for your skills! Whether you are a professional or small business owner seeking more clients through online visibility, or a salaried individual looking for side or passive income, we will show you how to do it by showcasing your skills and building a community that trusts and pays you. (Watch the 1st lecture for free). One-time payment! No recurring fees! Lifelong access to videos!
- Portfolio Tracker! Track your mutual funds and stock investments with our Google Sheet!
- We also publish monthly screeners for
Our Podcast: Let's Get Rich With Pattu
On Spotify: Let's Get RICH With PATTU! Every single Indian CAN grow their wealth! On Audible: Listen to the Let's Get Rich with Pattu Podcast
Listen to the Let's Get Rich With Pattu podcast on YouTube.
Now watch Let's Get Rich With Pattu தமிழில் (in Tamil)!About The Author
Dr M Pattabiraman giving a lecture
- Dr M. Pattabiraman (PhD) is the founder, managing editor and primary author of freefincal. He is an associate professor at the Indian Institute of Technology, Madras.
- He has over 14 years of experience publishing news analysis, research and financial product development. He has over 28 years of teaching and research experience. He is also a public speaker and keynote presenter.
- He is a patron and co-founder of “Fee-only India,” an organisation promoting unbiased, commission-free, AUM-independent investment advice.
- Connect with him via @pattufreefincal on X LinkedIn YouTube
- Pattabiraman has co-authored three print books.
This book helps you ask the right questions and find the right answers. It also includes nine online calculators to create custom solutions.
(2) Gamechanger: Forget Startups, Join Corporate & Still Live the Rich Life You Want. 
Both the boy and girl versions of "Chinchu Gets a Superpower".
Most investor problems stem from a lack of poor decision-making. We made bad decisions and money mistakes when we started earning, and we spent years undoing them. Why should our children go through the same pain? What is this book about? As parents, what if we had to groom one ability in our children that matters not only for money management and investing but for every aspect of life? My answer: Sound decision-making. So, in this book, we meet Chinchu, who is about to turn 10. The story follows what he wants for his birthday and how his parents plan it, while also teaching him key ideas about decision-making and money management. What readers say! 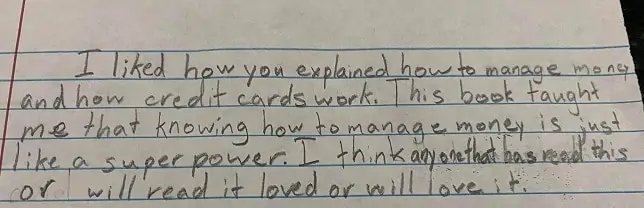
Feedback from a young reader after reading Chinchu Gets a Superpower!
Must-read book even for adults! This is something that every parent should teach their kids right from a young age. The importance of money management and decision-making based on their wants and needs. Very nicely written in simple terms. - Arun.
About freefincal & its content policy
Freefincal is a News Media organisation dedicated to providing original analysis, reports, reviews and insights on mutual funds, stocks, investing, retirement and personal finance developments. We do so without conflict of interest and bias. Follow us on Google News. Freefincal serves more than three million readers a year (5 million page views) with articles based only on factual information and detailed analysis by its authors. All statements made will be verified with credible and knowledgeable sources before publication. Freefincal does not publish paid articles, promotions, PR, satire or opinions without data. All opinions will be inferences backed by verifiable, reproducible evidence/data. Contact Information: To get in touch, please use our contact form. (Sponsored posts or paid collaborations will not be entertained.)Our publications
- Your Ultimate Guide to Travel. This is an in-depth exploration of vacation planning, including how to find affordable flights, budget accommodations, and practical travel tips. It also examines the benefits of travelling slowly, both financially and psychologically, with links to relevant web pages and guidance at every step. Get the PDF for Rs 300 (instant download)
- How to profit from content writing: Our ebook is for those interested in getting a side income via content writing. It is available at a 50% discount for Rs. 500 only!