Last Updated on February 12, 2022 at 6:16 pm
Last week I had reported that the annualized return (XIRR) of all my equity MF transactions tagged to retirement planning goal (or financial freedom) dropped from 11.6% in Dec 2019 to 2.75% after the crash. Some readers were either disheartened about this or twisted the result to point out equity investing is risky. In this article, I trace the growth of my MF retirement portfolio along with an imaginary investment in Nifty to point out why this is the time to be investing in equity although most of my gains were wiped out by the crash.
Context is key. Like we have seen several times before, equity will always be volatile no matter how long we stay invested (the AMCs and even the NSE wants us to think otherwise, but we know why.
So returns will be volatile too with huge swings. This will never change. What can change is our plan to handle this. My point in articles such as these – 15-year Nifty SIP returns crash to 8% (51% reduction since 2014) – has always been the same.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
An unmanaged equity investment will just go where the market takes it and our fate depends on luck. Proper financial goal planning with a clear risk reduction strategy before and after retirement is essential.
I had mentioned in the 2.75% post that I have been able to cling on to my financially independent status thanks to a cash component and that annualised return does not matter much – only what the portfolio is worth. That is, how long one can live off off it with a reasonable return and inflation assumption.
Many readers/viewers (on Youtube) were appalled about the low return. Some claimed I had made a mistake, some claimed I did not account for rebalancing. In fact, if you see the graphs below, you might ask, “it seems like you have left the portfolio to luck. Where is the plan and active management you keep talking about?”
Again context matters. With great difficulty, I managed to keep my equity portfolio close to 60%. My NPS works like a massive step-up SIP increasing with every DA, every increment, pay commission, promotion etc.
I have never seen (in spite of the big gains seen below), the equity portion go beyond 60%. So I never had to rebalance so far. Besides, my retirement is still 19 years away so I have never had the need to vary asset allocation as well. So yes, so far the portfolio has just swayed with the market.
In hindsight, you might think, “if only you had booked profit when you had 60%-80% gains (see below)”. That would have destroyed my portfolio.
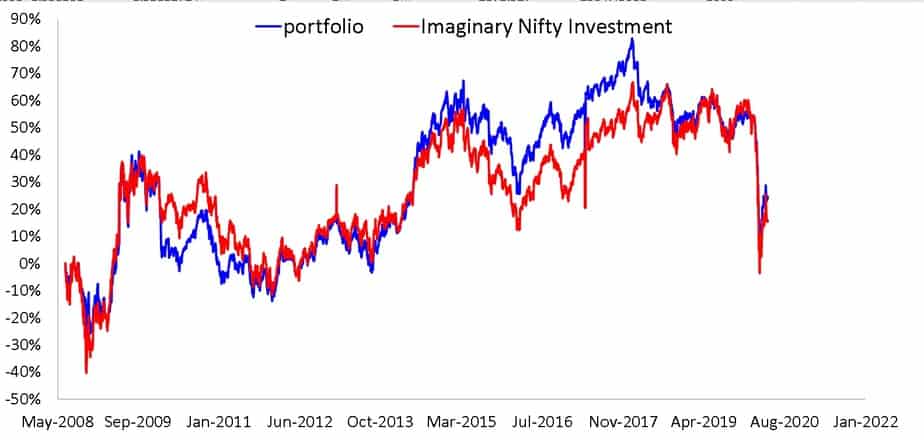
This is the normalised growth of the equity MF retirement portfolio (direct equity and NPS not included) with the total investment and an imaginary investment in Nifty 50 – same dates, same amounts since June 2008.

Note, an expense ratio is not included for the Nifty portfolio. Notice the crash nearly wiped out all my gains. This is a close-up since Jan 2020.

It is both immature and childish to argue if active funds (my portfolio) or Nifty 50 investment is better. This kind of past performance is not relevant to whether you choose active funds or passive funds. This should be the only reason:
Finally, the absolute gain or loss is shown below. The crash has pushed me back top Aug 2013 in terms of gains.
I had increased my investment significantly during 2011-13 (accidentally) and it changed my life when the gain finally came. Now I am almost back to that stage. We are on the threshold of another prolonged sideways market.
This is not the time to be disillusioned and run away from equity. This is the time for the big push into equity (with plan limits, assuming there is one!). The cycle will reverse and the gains will be back again. It will not take long for that 2.75% to go back to double-digits.
That is optimism or hope, yes, but only after all the personal considerations are addressed and factored in the investment plan. Please create a custom plan for yourself and start investing in the right asset classes, the right asset allocation at the right time.