Last Updated on September 4, 2018 at 10:57 am
A look at ‘how much’ or ‘what is the corpus required for early retirement in India?’. I had earlier written a detailed post on this subject and the common misconceptions youngsters seeking financial freedom form after reading blogs like ERE and MMM.
The central message of that post was, early retirement is possible, but one must have a comfortable corpus taking into account the high inflation levels in India. Unfortunately, many people misunderstood it and assumed that I meant early retirement is not possible. Either before or after reading this post, I strongly suggest you read that one as well: Is it possible to retire early in India?
Over the past few years, I have reviewed 5/6 portfolios of early retirees and discussed their views of risk and reward. All of them, have huge margins of safety when it comes to estimating the retirement corpus (which is an annual exercise before and after retirement. See why here)
Personally I have similar if not higher margins of safety. I am not desperate for financial independence but do seek it aggressively. With a simple MDBSC approach in mutual funds, and with copious amount of luck, I might get there before I turn 50: Retirement Planning: My Story So Far
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
The reason I state the above is, “margin of safety” depends on the age of the person. It is hard to convince a 25-year-old kid who has not seen the vicissitudes that assuming a 4% alpha after retirement like Mr. MMM advocates, can be suicidal or having 80% equity after retirement to compensate for a low corpus, completely ignores the importance of sequence of returns.
It is obvious that bad experience is a great teacher. Almost a decade ago, while I was waiting to be interviewed for my current job, I met my teacher and told him about my hardship after my father took ill. He said, “you should be happy that you are going through this when young. Will give you a lot of strength”. I was 31 then and thought it was bollocks. At 40, considering what I experienced afterward, I believe those are golden words.
My point is, while retiring early it is extremely important to account extreme situations and that comes with age and/or experience.
Let us go through an early retirement planning calculation to illustrate my point.
Consider an individual (or couple) who is(are) planning for 40 years in retirement.
Zero real return
If their current expenses are say, Rs. 3,60,000, then, for an assumed 7% yearly increase in pension (due to inflation) and for a conservative (but safe) post-tax return of 7% from the entire portfolio (zero real return), the corpus required is 1.44 Crores (40 times annual expenses at retirement)
1% real return
Same assumptions as above, but now with 8% post-tax return from entire portfolio (~ 1% real return), the corpus required is 1.20 Crores (33 times annual expenses at retirement)
2% real return
Same assumptions as above, but now with 9% post-tax return from entire portfolio (~ 2% real return), the corpus required is 1.02 Crores (28 times annual expenses at retirement)
3% real return –> 88 Lakhs (24 times annual expenses at retirement)
4% real return –> 76 Lakhs (21 times annual expenses at retirement)
What would you do if these were your numbers?
My view of early retirement is simple: I should have enough so that I don’t have to work again. I might take up part-time assignments, but I should not be dependent on this income.
I will sleep peacefully if I can retire with 1.44 Crores. If I hate my current job, I will probably retire with 1 crore (2% real return). Dangerous to assume a real return above that.
Let us see how one can pull off early retirement with 2% real return (some luck is necessary in this case though).
Suppose my retirement corpus is X. I divide the corpus into 4 parts.
X = A + B+ C+ D
A –> invested in fixed income assets (7% post-tax) and used to generate income increasing at 7% a year.
A = 10 times the annual expenses in 1st year.
B, C and D are invested in a portfolio with 60% equity (12% return) and 40% debt (7% post-tax)
B is invested for 10 years. After which it is taken out and used to generate income for years 11 to 20 in the same manner as A.
C is invested for 20 years. After which it is taken out and used to generate income for years 21 to 30 in the same manner as A.
D is invested for 30 years. After which it is taken out and used to generate income for years 31 to 40 in the same manner as A.
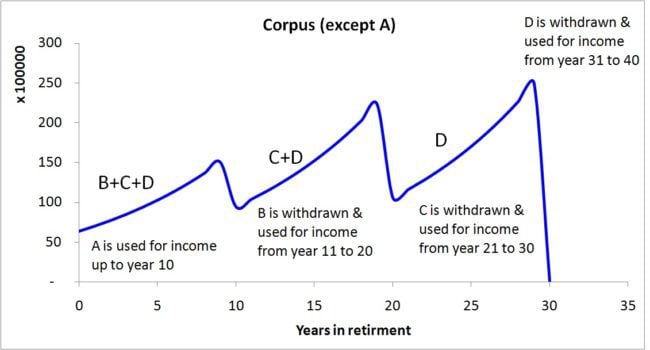
Note: return assumptions are invalid over a 40-year period, but since they are reasonable wrt initial years, I think it is not terrible. In any case, one can easily rework with lower returns from both equity and debt down the line.
This strategy is equivalent to an overall real return of about 2%. So if the couple has a corpus which is more than 28 times (preferably 30) current annual expenses, it is reasonably safe for them to retire.
What can go wrong with this plan?
1) Extended sideways market (bad sequence of returns)
2) unexpected recurring expenses
3) inflation higher than expected.
How do you safeguard yourself against such circumstances? With age, we realize that the best way to handle this is to have a slightly larger corpus to begin with.
My take: Work with min 7-8% inflation (I work with 9%) and not more than 2% real return (I work with zero real return). Do not decide to retire unless you have a corpus that is at least 30 times your current annual expenses.
This early retiree checks each year if his corpus is 35 times annual expenses: Achieving Financial Independence: A Forthright Interview
The above illustration can be downloaded from here: Early retirement illustration
This is only an illustration and not a calculator. If you want to make changes, you need to know how the sheet is written.
If you want a calculator, try this: Inflation-protected Income Simulator
You can also consider checking out these posts:
Generating an inflation-protected income with a lump sum
Illustration: Generating inflation-protected post-retirement income