Last Updated on December 29, 2021 at 5:55 pm
As regular readers may be aware, we publish a personal financial audit each December. This time, we asked regular readers to share how they review their investments and track financial goals. Suhas kindly agreed to share his method. You can also follow his regular reviews in his blog linked below.
About the author: Suhas Bharadwaj is a Software Engineer by profession. He is interested in sports and personal finance. Follow his portfolio updates in his blog DudduKaasu. Editor’s note: If you are interested in sharing your audit with freefincal readers, let me know by email. These audits are meant to inspire and aid the DIY community.
audit noun
an official examination of a business and financial records to see that they are true and correct
For me personal finance audit is more of a review rather than an audit, it helps to gauge how you are currently doing financially and if the path you are on is right or needs any course correction. I generally do a review/update every quarter on my blog, but thanks to Pattu sir for giving me an opportunity to write an annual review of my finances, hopefully, it’s helpful to others in some way.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
First the big picture, how has the net-worth progressed from December 2019 to December 2020?
| DEC-2019 | DEC-2020 | |
| Net-worth | 100 | 150 |
| Equity | 44% | 50% |
| Locked Fixed Income | 31% | 24% |
| Liquid Fixed Income | 25% | 26% |
Equity consists of equity mutual funds, direct equity(small portion, started recently) and RSUs.
Locked Fixed Income is debt with long term lock-in, it consists of EPF and PPF.
Liquid Fixed Income is basically debt which is liquid and can be accessed quickly it consists of liquid funds, arbitrage funds, savings accounts, bank deposits etc.

The increase in net-worth is mostly due to two reasons, one – compared to last year this year I saved almost 23% more, two – some good gains, this is easily the best year for me (and I guess for others too) in terms of returns since the time I have been investing(2012/13) – all thanks to the current bull run (or is it still a recovery? J). I majorly track and aim for 3 goals… Emergency corpus, Kid’s education corpus, Retirement or financial independence corpus.
Emergency Corpus
This is basically the entire liquid fixed income, this is my go-to place for any kind of emergencies or tactical reallocation(if any),
Back in 2019 I had Ultra short term funds, after the Franklin fiasco I moved completely to liquid funds, it was mistake to keep in Ultra short term funds, fortunately I pulled out before they locked the funds.
I have increased my savings over the last couple of months because sometime this month or next month I will have a few big-ticket expenses (split between me and my wife), so accumulating for that purchase as and when it happens.
What is the emergency fund worth today? It consists of slightly more than one year’s worth of my gross salary; aim is to keep it around one year’s worth of my gross salary. Some numbers of this goal
| DEC-2019 | DEC-2020 | |
| Emergency Corpus | 100 | 132 |
| Liquid funds | 10% | 55% |
| Arbitrage funds | 9% | 24% |
| Bank account | 3% | 21% |
| Ultra Short Term Funds | 59% | 0% |
Kid’s Education Corpus
I have a three-year-old, started saving for him as soon as we knew we were becoming parents, the corpus for this is currently present in a single aggressive hybrid fund and PPF.
Current XIRR of the hybrid fund is around 16.83%, it’s only a two-year-old fund.
Even though the equity has run up big time, I would like to wait till April first week to rebalance, which is actually my usual time for rebalancing. Expected allocation at this time is around 71% and currently, it’s at 78%, but corpus wise it’s only a few lacs high, so I’m ok to have this allocation imbalance for now. Equity may tank by the time we reach April, but that’s okay, the goal is almost 14 years away.
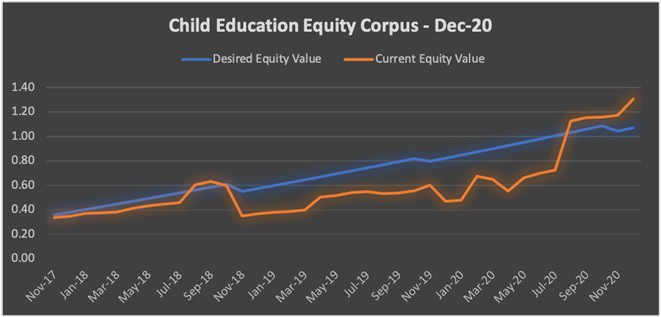
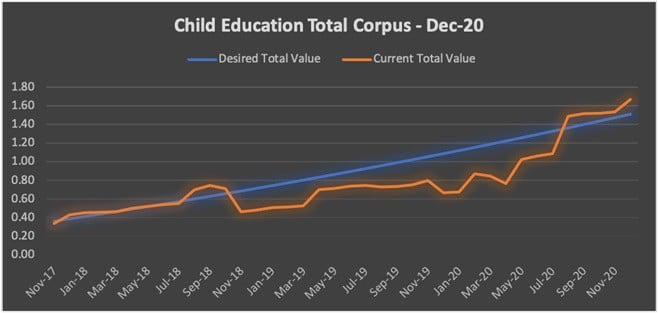
What is the kid’s fund worth today? The current corpus should cover for around 3 years of education in a private engineering college today, aim to accumulate enough for a UG and PG if possible.
Some numbers and charts of this goal
| DEC-2019 | DEC-2020 | |
| Kids Education Corpus | 100 | 249 |
| Equity | 70% | 78% |
| PPF | 30% | 22% |

Retirement Corpus
The debt portion for this goal is EPF and the equity portion of this has a basket of equity mutual funds and RSUs, recently started dabbling into direct equity.
Back in March 2020, I took advantage of EPF withdrawal for Covid-19 and moved that money to equity mutual funds.
Current XIRR of the entire basket of equity mutual funds is 13.2%
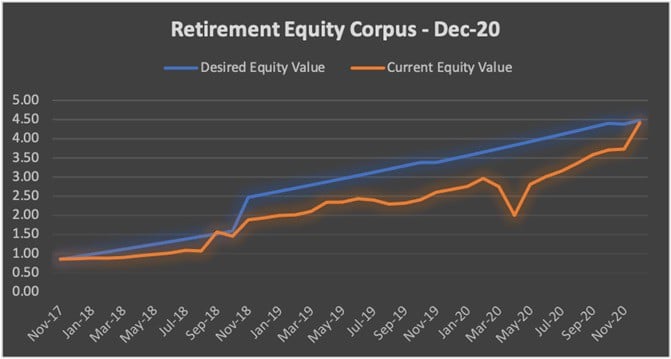
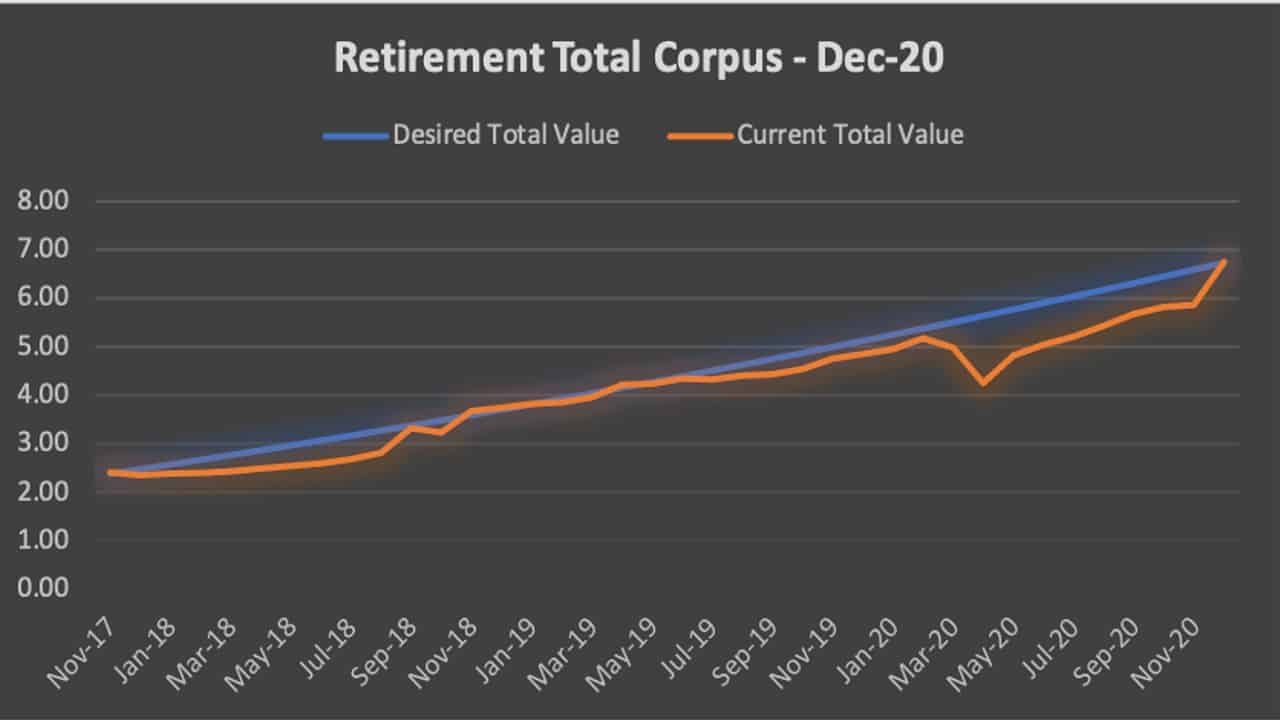
What is the retirement corpus worth today? The current corpus is around 11 times my current annual expenses, the aim is to reach 35-40 times current expenses, but personally, kid’s education is a higher priority for me, so I’m ok to delay this goal if required.
Some numbers and charts of this goal
| DEC-2019 | DEC-2020 | |
| Retirement Corpus | 100 | 138 |
| Equity | 55% | 65% |
| EPF | 45% | 35% |
| DEC-2019 | DEC-2020 | |
| Equity part of Retirement Corpus | 100 | 165 |
| Equity Mutual Funds | 95% | 93% |
| Direct Equity + RSUs | 5% | 6% |

Note: Many people ask me how I generate the charts and how do I check the XIRR etc, I have written a separate post on it, please check it.
Github link if you want to directly check out the tool
How about 2021?
As like previous years I will try to see if I can increase my savings compared to 2020, a salary hike will definitely help J, but I’m not counting on it. I will aim to keep the required corpus as close to the expected corpus as much as possible.