Last Updated on March 19, 2016 at 11:26 am
Many people ask, “how much should I save each month from my salary?”. They are not looking for ‘dumb’ answers like, “invest as much as possible”;”use a retirement calculator and goal calculator to find out”; “have you thought about financial freedom in future?”
They are looking for a nice low percentage like 10%, preferably 5%, so that they can blow the rest free of guilt – ‘I asked in XYZ forum and they said 10% is good enough for start. I can’t do 10% right now. Right now, I am out of money by the middle of the month, but I will get around to 10% soon. I have time!’.
This the familiar refrain of so many young earners today. Perhaps it was always the refrain of young earners. Perhaps that is how it should be!
For many young earners it is a phase. Perhaps it is a necessary phase, perhaps not. Who can tell.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
The trouble is, an expensive lifestyle is hard to cast aside. Especially when there are so many choices and so easy to spend.
I can think of two kinds of expensive lifestyles:
Type I Dominated by peer pressure; impulse buying; unhealthy socializing; habits that can not only kill, but also destroy a household etc.
Type II Dominated by passion, an inner urge. A hobby, a pastime that is more fruitful than work or ordinary forms of leisure.
Type I requires curtailing. There is no question about it. An unhealthy lifestyle today, pretty much guarantees an unhealthy lifestyle tomorrow, one way or another (assuming the person survives!).
Preaching will not work. All we can do is to propose an alternative pursuit: watching money grow productively
Perhaps if they see this happen, they might take to it and invest more. I cannot think of any other way such a lifestyle can be altered. We can give lofty presentations about power of compounding, cost of postponement, real return etc. but unless they realize the importance of disciplined investing, not much will work.
Type II is tricky. There is no question of curtailing it, unless the person has huge debts because of the hobby. What has got to be done. has got to be done and best done when young. Trouble is, many of these activities are quite expensive. Be it adventure sports, astronomy or photography, the equipment is do darn expensive. There can also be recurring expenses like travel, maintenance etc.
Perhaps a gear related EMI is inevitable for an young earner, but as long as it can be paid each month, it should be okay.
The trouble with this group is that they are always hungry for more! They have one piece of expensive equipment, soon get the hang of it and long for something more expensive!
If upgrading is done frequently, they will be no different from the type I guys.
Striking a balance is crucial. Yes, there are certain things that are best done when young – investing is also one of them!
For example, if you have an expensive hobby, consider investing for 10 months a years, spending the rest as desired. Some such arrangement in which investing is not left out of the equation.
It will take a couple of years to establish this balance, and that is fine. The desire to create such a balance should take us there.
When my wife wanted to take up astronomy and photography, we had to briefly interrupt our investment schedule. To ensure that we did not feel guilty about it, we researched about telescopes, binoculars, tripods and cameras for about 6 months before making the purchase.
They say postponement is one way of curing impulse buying. I agree, but I recommend productive postponement with a survey and comparison of product features. This way we can understand fine print, arrive at a good fit and get bang for the buck.
Many unmarried youngsters state that they have no investment objective. Although incorrect, it is understandable. If only they get to invest that 5% or 10% each month in a productive asset, they will watch it grow and gradually recognize the importance of watching it grow. If only.
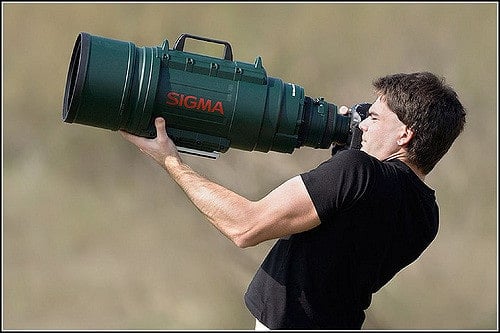
A telezoom lens. We dont have one this big, but what we have is heavy enough for me! Photo credit: Ben Salter