Last Updated on December 29, 2021 at 5:21 pm
Finance Bill 2020 has proposed that Individuals will have to pay Tax on Dividends from Shares and Mutual Funds as per slab from 1st April 2020. We discuss when and how to use mutual fund dividends in this new tax regime.
What are mutual fund dividends? A lack of understanding of what dividends are is the primary reason why investors mis-buy dividend option mutual funds. When a fund declares a dividend it refers to the fund manager selling some stocks or bonds or gold to distribute this income to unitholders proportional to the units that they hold. For a simple explanation with numbers see: When do mutual funds declare dividends.
In a growth option, periodic profit booking is not done by the fund manager. There is no difference in returns (CAGR for a lump sum investment and XIRR for multiple investments) between a dividend option and growth option.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
When we redeem from a fund, the units decrease. When a fund declares a dividend, the NAV decreases by the amount of dividend offered but the units remain the same. Both methods result in a reduction of market-linked value.
It is a pity that dividends from hybrid funds were sold as a source of regular income to retirees. The introduction of DDT in equity mutual funds at the rate of 10% with 12% surcharge and 4% cess was the first blow to such investors (and such selling). This effective tax rate (DDT) of 10% x (1+12%) x (1+4%) = 11.648% is the present rule (valid up to 31st March 2020). Taxing these as per slab (from 1st April) is the second blow.
Do we even need mutual fund dividends? It depends on our understanding of the option and how to use it. Regardless of tax, it was an unnecessary overkill to receive monthly dividends as “income”. Also, regular dividends from a volatile asset can be disastrous
Usage 1: (A) Dividends offer a way to take some ‘heat’ off the table or now and then book some profit (say once or twice a year). It would be ideal if these dividends were tax-free or taxed at a low rate. However, even at the slab rate tax, the primary purpose of risk management could be served.
This is quite unappealing in the wealth accumulation stage. After retirement, if one has a bucket strategy created from a basket of retirement products then risk from the equity bucket could be reduced with dividends (not monthly dividends but the normal dividend options where the payout is only once or twice a year).
This is an automated profit-booking system and the money could be shifted to less-risky buckets. Of course one will have to pay tax as per slab on these dividends and the argument against this would be: LTCG has a one lakh tax-free limit and is more tax-efficient.
Tax-efficient yes, but not risk-efficient as it would be subject to emotions and biases, unlike periodic dividends. Since risk-efficiency takes precedence over tax-efficiency, dividends can still be used as part of a bucket strategy regardless of the tax slab.
Those who do not appreciate paying tax as slab must ask themselves what is the alternative risk strategy that they have in place. An entirely surprising and counterintuitive asset-allocation strategy pre- and post-retirement is discussed in the lectures in the goal-based portfolio management course.
Usage 2: Reduce (ideally eliminate) capital gains tax if the risk between growth and dividend option is similar.
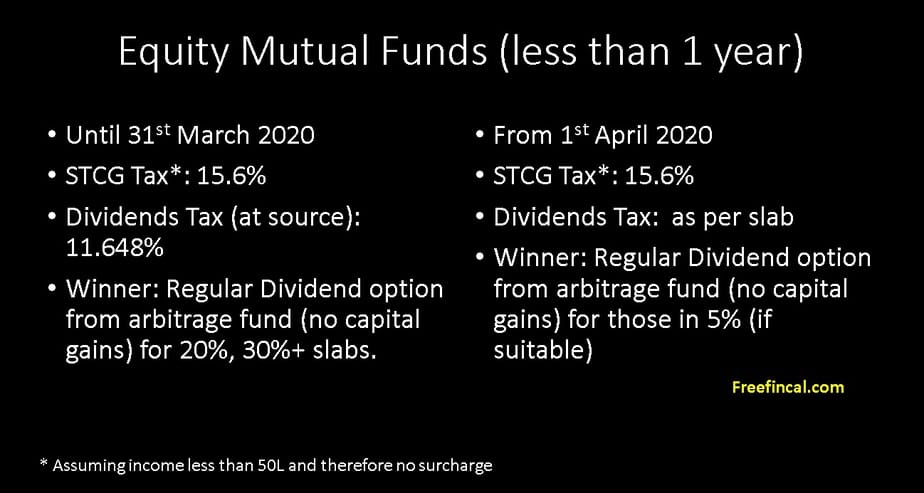
Suppose you wish to invest for say, 10 months and choose an arbitrage mutual fund. With the growth option, you pay 15.6% tax (assuming income less than 50L and therefore no surcharge).
If you choose the weekly or monthly dividend option, the NAV will remain more or less at the same value (because the gains are completely paid out). So there would be no short term capital gains tax.
Earlier dividends were free of tax! Even at the current 11.648% DDT, the dividend option is better than the growth option for this duration for those in 20% and 30%+ slabs.
For dividends taxed as per slab, dividends are beneficial only for those in the 5% slab(which is significant).
Note, we can compare growth and dividend option taxation only if the risk is similar. In the earlier use-case, money invested in a growth option in an equity fund after-retirement is riskier than the dividend option.
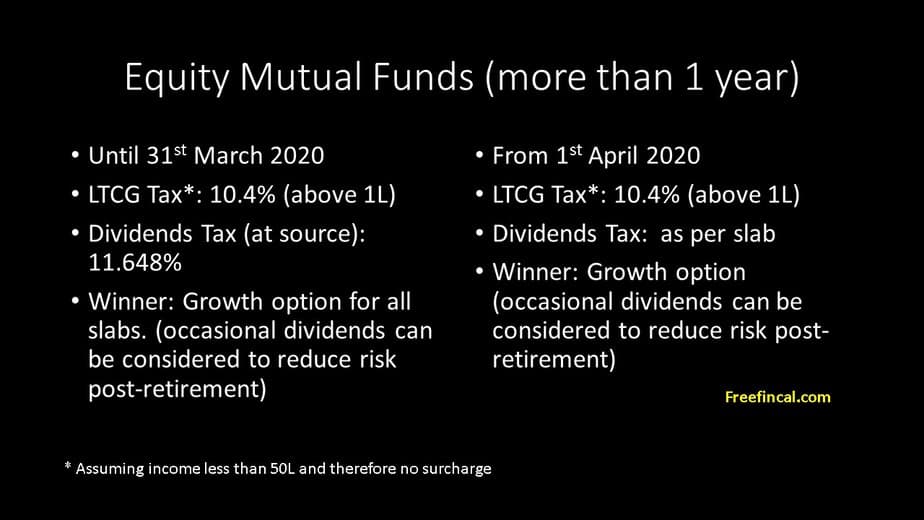
Now let us extend the investment in an arbitrage fund for more than a year. The growth option will be taxed at 10.4% (assuming income less than 50L and therefore no surcharge) if the capital gains for that financial year are more than a lakh.
Dividends will still be taxed as per slab. Assuming no capital gains, dividend option is not useful at any slab rate.
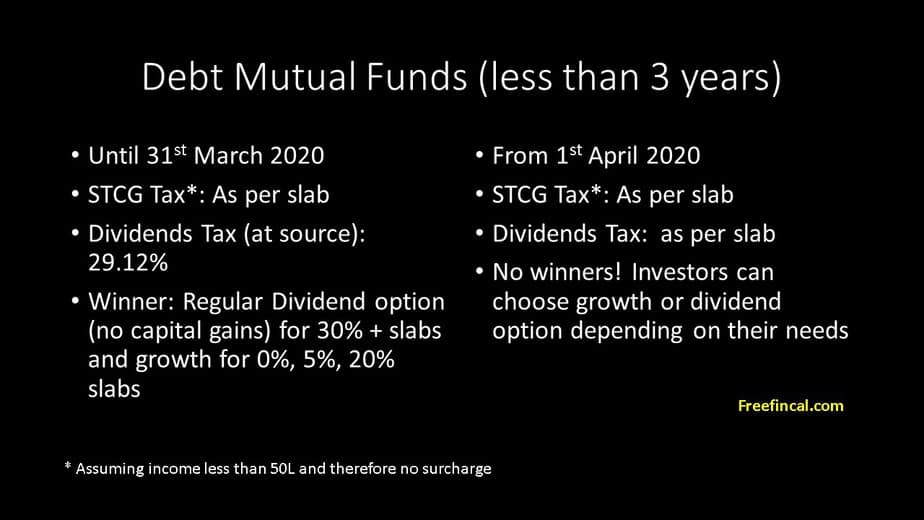
Let us now look at the same situation for a debt fund. For an investment made for less than 36 months, the capital gains tax is as per slab. The dividends are also as per slab. This puts both growth and dividend option on the same level.
The current DDT is 29.12% (25% + 12% Surcharge + 4% Cess). So from April 1st 2020, all investor can consider the dividend option in debt funds at least for duration less than or equal to 36 months.
If I wanted regular income for less than three years, the monthly or weekly dividend from a liquid fund or overnight fund will do the job just as efficiently as an SWP.
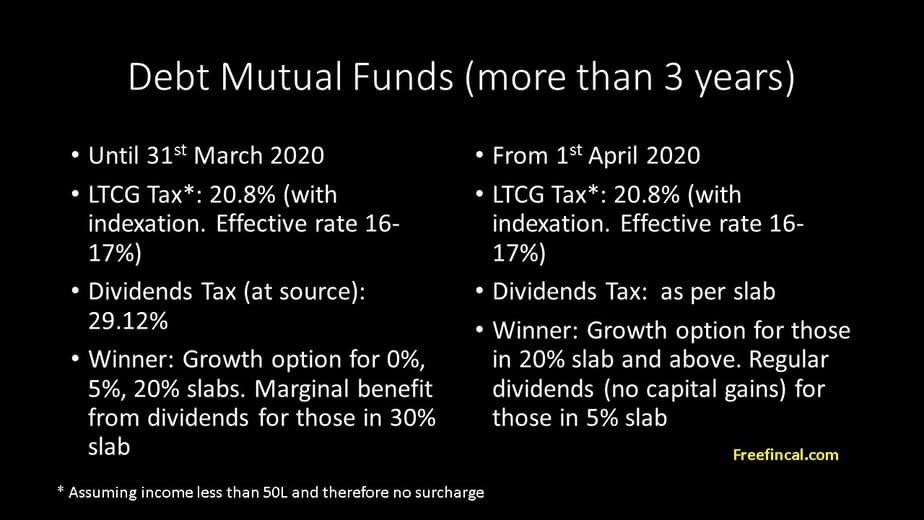
What about more than 3 years? In this case, the long-term capital gains tax is 20.8% (assuming income less than 50L and therefore no surcharge). This is on the indexed capital gain. That is after accounting for the cost inflation in the purchase price. The effective tax rate would be about 16-17% and this is the same for all tax slabs.
Now dividends would be taxable as per slab. So this is favourable only for those in the 5% slab. Again a comparison is possible because the risk is the same.
Summary
Mutual fund dividend taxation as per slab can be beneficial for those in the 5% slab (as long as they remain there!). This applies to equity funds and less than one-year duration and debt funds above three years (no disadvantage below 3Y).
Retirees can use this intelligently, choose debt funds best suited for their needs and pay significantly lower tax than fixed deposits (on a small portion of their portfolio). The only practical problem is, retirees in the 5% slab would not have much of a surplus corpus or income to play around. So not many will actually benefit from these changes even if they are willing to experiment with arbitrage and debt funds.
For those in 20% slab, debt fund dividends up to three years is a new option, although not a superior one. Those in the 30% slab or higher are the worst affected. They will have to consider dividends only if the benefits outweigh the tax (bucket strategy after retirement).
Do you use mutual fund dividends? How are you going to change your strategy from April 2020? Please comment below.