Last Updated on December 14, 2025 at 3:12 pm
Every December I take stock of my financial goals and evaluate where I stand. I have been publishing this since 2013 and this is the 6th edition and 1st video version. My goal is only to point out the benefits of goal-based investing and have no intentions to brag.My success so far (if it can be called that) is simply due to discipline and luck.
This is the archive of personal finance audits published before:
Developments this year
I made no changes to fund holdings and unlike last years when I rebalanced twice, there was no opportunity to do so this time. I have been following goal based investing for about 8Y now and try to increase the investment amount by 10% but due to the effect of (true) compounding the amount had become quite big for retirement goal. So the last couple of years I barely managed to invest the same amount.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
The 7th pay commission finally changed that, again due to inflation in expenses and new expenses that, that 10% increase is under threat. Let us see how it goes.
Since I have been talking about picking stocks without effort and lazy investing, I thought it is appropriate to have some skin in the game. So currently my direct equity exposure is a minuscule 2% compared to the equity mf exposure. I hope to increase it with time. This is the strategy I use (the strategic index may vary)
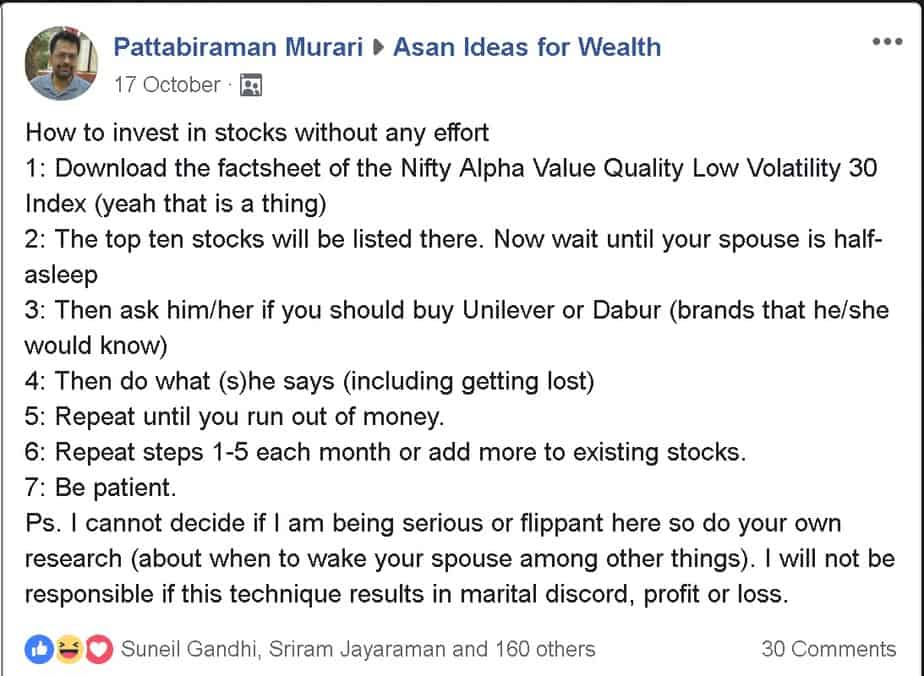
Screenshot of my OCt 17th post on Facebook group, Asan Ideas for Wealth.
My retirement
Equity portion (equal proportions):
- HDFC Balanced. XIRR: 12.8% (consolidated after the merger, using my tracker)
- Parag Parikh Long Term Equity Fund XIRR: 13%
- Quantum Long Term Equity: XIRR 11.6%
- Overall XIRR since inception: 11.2%
It should be obvious that I prefer low volatility funds. The overall XIRR has improved from 10% a couple of months ago: After 10 years my equity return is 9% – Yay! Here is why I am not worried Here are a couple of graphs from that post:


Debt portion:
- NPS (Central govt, mandatory): XIRR since May 2010: 9.3%
- My PPF and my wife’s PPF (small exposure, we only keep these accounts alive)
Asset allocation
- Equity 55%
- Fixed income: 45%
I would prefer 60% equity portfolio. I could withdraw from my PPF and rebalance this but so far I have been lazy to do this. If the market falls further, I might be tempted.
Analysis: retirement
I keep pointing out that “returns do not matter”. We need to evaluate what is the corpus actually worth.
- If I stop investing for retirement (incl mandatory NPS contributions), I can still retirement by age 50 (assuming 40 years in retirement inflation of 8%)
- If I quit my job now, I can generate an inflation-protected income for about 33-35 years with a bucket strategy (depending on market conditions)
- If I retire normally at 65, again the same as above applies.
- If X is my annual expense, my retirement corpus is about 30-31X. This means that I can beat inflation for 30-31 years if my retirement corpus earns a post-tax return equal to inflation. See this video for details
Resources to generate the same insights:
- E-book: How to retire early in India
- Review Your Financial Freedom Portfolio in Seven Easy Steps
- Key features of the freefincal robo advisory software template
My son’s education and marriage
These were separate goals but merged a couple of years ago.
Equity portion (not so equal proportions):
- HDFC Prudence. XIRR 14.4% (don’t know why I still hold on to this, inertia I guess!)
- Mirae India Opportunities (Mirae India Equity fund) XIRR 11.9%. This fund is probably feeling the heat of the market for the first time?
- ICICI Dynamic (ICICI Multi-asset fund) XIRR 13% (likely to decrease going forward)
Amusing how this portfolio is more volatile than my retirement!
Debt portion:
- PPF (in his name) + I also use y mothers PPF (which doubles as her tax planning instrument). However, none of the PPF accounts is maxed out. I prefer to pay a little exta tax for my mother than lock money up in PPF
- ICIC Equity arbitrage XIRR 6.9%. This is meant to rebalance and gradually accumulate the corpus as the goal nears
Asset allocation
- Equity 60% (exact!)
- Fixed income 40%
Analysis: my son’s future needs
The 40% fixed income allocation is now enough to fund a UG degree comfortably. My son is not yet 9. Going forward, my goal is to increase the fixed income allocation so that the cost of UG + PG degree is taken care as per current expenses. If I can manage this for as long as possible, there is no reason to worry about a market crash close to the goal deadline.
I have shown that a step-wise reduction in equity well before the goal deadline is a simple way to reduce risk and achieve a target corpus, but you can also play it by the ear if you have some confidence
Video version of the audit
What do I expect in 2019?
Why think 9 days ahead?! It is quite possible that the market could dive south next week and stay there at least until the 2019 elections! A year ago, the Congress did not seem as strong as it is today. If they do not win by a slender majority it will be a tight race and hung parliament. Such things will spook the market. So it is going to be rough first half and that should be obvious. However, if you get your basics right, there is no need to worry if the market crashes tomorrow. Watch out for this video to be published on freefincal @Youtube today evening.
If the market crashes tomorrow, there is no reason for me to react, that is the whole point of this post!!
Also, check out: