Last Updated on December 19, 2021 at 11:42 am
“How can I fund my goal if the market crashes a few years before I need the money?” is a question that I have often encountered. In this post (and the next), I address this issue with some specific examples.
An exit strategy is more important than an entry strategy
Suppose I can invest Rs. 1,000 a month and after a few years, the money has grown to Rs. 1,00,000 (more than possible seen it happen with a Rs. 500 SIP). Should I worry about when to invest 1,000 looking at market levels (aka dip buying) or should I be worried about the risk associated with the 1,00,000?
The point is, no matter when you buy, if the market crashes, the corpus will fall in value. Therefore, I would rather focus my time and energy on the managing the risk associated with the corpus while systematically investing each month. Read more: Managing Risk Without Stopping Mutual Fund SIPs.
Multiple solutions to every problem
Every problem has multiple solutions and it is immature to claim one is better than the other. Just a matter of choosing a strategy that we are comfortable with. Reducing corpus risk (aka de-risking) is no different.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
For example, I can continue to invest systematically and
- Change the asset allocation of my portfolio (equity:fixed income ratio) as per market conditions (aka dynamic asset allocation)
- Using index PE
- Using index moving averages
- A combination of both, using other methods etc.
- Change the asset allocation with a set plan (aka strategic asset allocation)
- Reset the asset allocation once a year (aka rebalancing)
- Reset the asset allocation once it deviations by a set amount (5,10%) (aka threshold rebalancing)
- Use a combination of (1) and (2) above.
In addition to the above, I must also have a de-risking strategy in mind.
De-risking strategies
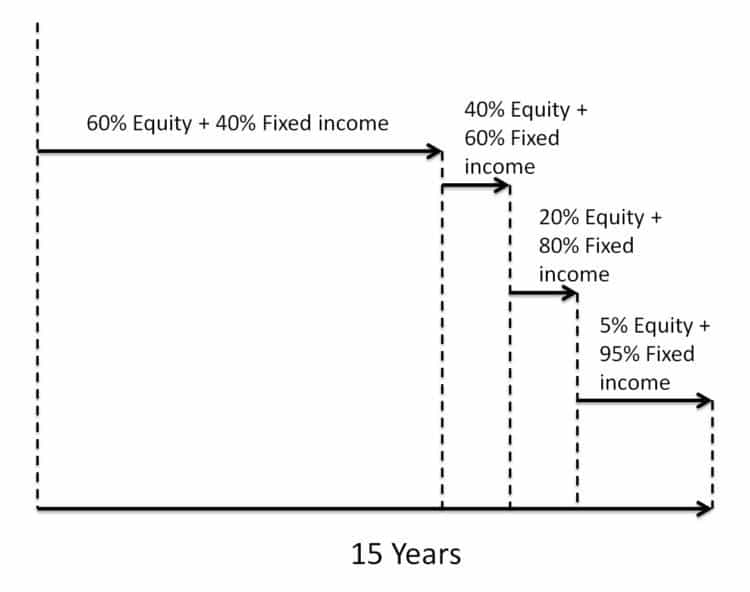
This post is about de-risking strategies. Consider that my asset allocation is 60% equity and 40% fixed income for a financial goal that is 15 years away. To understand how this is chosen in the first place, see deciding on asset allocation for a financial goal.
I cannot afford to maintain this asset allocation for the entire 15 years. As the goal approaches, I must have a strategy in place to reduce equity allocation. This is what the title refers.

Again there are multiple de-risking strategies and I will refer to two that appeal to me.
Returns do not matter
Surprising as it seems, investment returns do not say much about our ability to finance the future. A guy with an LIC policy can end up with more money than an equity guy. Not just because of the risk associated with the latter, but because of the amount invested.
When I perform a financial audit, the only question matters to me is, “what is the corpus worth?”.
If it is retirement, I ask :”If I retire with it today, how long can I be financially independent”.
Or to be more specific, “Is my fixed income asset allocation enough to guarantee me an inflation-protected income for the first 10-15 years in retirement” and the equity allocation enough to grow undisturbed for that amount of time to serve me later.
If it is my son’s education, I ask “What kind of education can I afford today?”.
My son is only about 7 years old and in the 1st standard. By the time he goes to 8th or 9th standard I will have a better idea of how much I will need to pay for his education. So I then starting ensuring that my fixed income assets have an amount close to that. So in the next 3-4 years, before he goes to college, the corpus is reasonably protected from market volatility.
The idea behind this strategy is to shift from equity to fixed income assets such that you ensure things go to plan. I like this because there is nothing technical about this. Just simple common sense.
This idea might seem impossible to you if you have just started out. Trust me, I would have felt the same 3-4 years ago. Give it a little time and you will see what I mean. December is personal financial audit month. So I will give more concrete examples.
Changing Asset Allocation in Stages
The second method is to change asset allocation with time. Or in particular decrease equity allocation gradually. An illustration is shown below. I will post back-testing results with S&P 500 based on this strategy tomorrow.
Other de-risking strategies based on market timing, fear of impending events, Lok Sabha elections etc. can easily be formulated.
Check out reviews for You can be rich too
If you have not purchased it, you can do via Amazon.in. Please consider writing a review either at Amazon.in
Part II
The second part of this study is here: How to systematically reduce the risk associated with a SIP