Last Updated on August 30, 2021 at 3:50 pm
A little too much is made of the importance of investing in PPF before the 5th of the month. How important is this? What if I fail to invest before 5th for a few months? Should I beat myself up about it?
Let us find out using the PPF tracker/calculator.
Assumptions:
Annual investment limit: Rs. 1,50,000
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Interest rate fixed for the entire tenure: 8.7%
Fixed Monthly Investment: Rs. 12,500 or
Fixed Annual Investment: Rs. 1,50,000
Investing each month
Final Maturity value if all the monthly investments are made before the 5th of the month: Rs. 45, 04, 384
Final Maturity value if all the monthly investments are made after the 5th of the month: Rs. 44, 73, 197
Difference: Rs. 31, 187
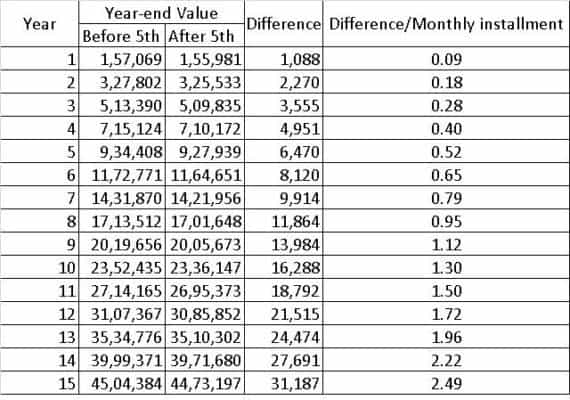
It hardly matters when you pay the subscription.
Of course, if you choose not to invest the maximum Rs. 1.5 Lakh in PPF and had invested the money if equity, you will, after a few years of investing, gain or lose Rs. 30,000 (or more!) in a single day!
Of course, 44-45 Lakhs after 15 years is not a great achievement either, even if it is tax-free.
But then again, PPF fans are oblivious to such realities.
Investing once a year
There are those who believe that it is best to make PPF investments between April 1st -5th of each financial year. Let us find out how beneficial this is.
Maturity value if yearly investment of Rs. 1.5L is made before April 5th for 15 years: Rs. 46,75, 914
If monthly investments of Rs. 12,500 are made before the 5th of the month for 15 years, the maturity value (as seen above) is: Rs. 45, 04, 384
The difference is 1,71, 529 . This is indeed significant.
However, how many members of the PPF fan club can afford to shell out Rs. 1.5 Lakhs in one shot?
They can always delay the opening of the account by a year, until they have enough to make annual investments and then ensure they invest once a year before April 5th. How practical would that be (wrt to the financial goal), is something that each person will have to decide.
Also, the delay of a year should be taken into account if someone wants to compare ‘benefits’.
Now,
Maturity value if yearly investment of Rs. 1.5L is made after April 5th for 15 years: Rs. 46,44, 726
Again, the difference between ‘before 5th’ and ‘after 5th’ yearly investments is only Rs. 31, 187
Bottom Line (for PPF fans)
Forget about the ‘before 5th’ vs. ‘after 5th’ nonsense. Invest what you can, when you can.
Bottom Line (for investors)
There is more to investing than tax-saving and EEE instruments. Invest according to an asset allocation suitable for financial goals. PPF can certainly be part of a portfolio with investments in line with the asset allocation.
Let us not forget that securing 8-9% growth over 15 years could well result in a negative real return!