Last Updated on October 8, 2023 at 1:33 pm
Anyone who has used a retirement calculator would tell you the primary input is current expenses that are likely to persist in retirement. I have always maintained that one should not assume expenses will decrease after retirement! Therefore, I will only exclude cash outgo like EMI and expenses related to children from current expenses. This is all that one can do for now (besides of courses investing). The real reason we need money after retirement is not for ‘maintaining our present lifestyle’ – the aim of any retirement calculation.
The more I look at retired people, the more scared I get. The main reason for this is life is not an Excel sheet! Life does not pan out as projected on a spreadsheet. Unknown events are beyond our control and it is a bridge that we can cross only when we get to it. However, it probably helps to know that there are bound to be obstacles ahead even if we do our best to plan for retirement.
Health rather than wealth is key to peace and tranquillity in the evening of out lives. If God could guarantee our health after retirement and an instant death, there would no need to plan for retirement! We could be gainfully employed for as long as wanted to.
Even with reasonable health (which is not uncommon), a senior citizen could ‘get by’ with lifestyle downgrades if there is not enough corpus to spend.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
We are living in an age where the concept of family support is rapidly becoming non-existent in India. Forget about brothers and sisters or other relatives taking care of each other. The children are not present when the parents fall sick!
Young parents today have only 1/2 children. When they finish college and are ready to work, they will probably do so in another city or even country. Many of these who study abroad become unemployable in India because of the ‘field’ they work in. They set up roots in another country, get a mortgage and find it impossible to come back even if they wanted to. We see so many aged parents living alone. Imagine what would be the situation after 2-3 decades when young earners today start retiring!
My point is, not having enough money for day to day expenses after retirement is not a major problem at all. Someone used to Apple products today can choose to live without them after retirement (assuming they are still available!). Someone used to eating out once a week can survive on curd rice thrice twice a day as my cousin often warns me. Such kind of adjustments come naturally to humans if they are forced into a corner. After all, life always finds a way.
My father got a reasonable pension. Before he passed, he was bed-ridden for about 1.5 years. The total monthly treatment cost was about 5 times his monthly pension (he had no other corpus to speak of). We were driven to debt and found it difficult to meet ends trying to manage medical costs.
Today my mother receives a pretty decent pension (both hers and family pension). However, all of it gets spent in paying for an attendant and the medicines that she takes.
These are totally unexpected expenses, even for someone who has used a retirement calculator and systematically invested as required to beat inflation and all that sort of thing.
If you think I am paranoid, think again. How many people are likely to be blessed with the gift of manageable health post-retirement and an instant death? Most of us are likely to spend a considerable amount of money for healthcare. A good chunk of this would be towards assisted living. Already this is expensive even for attendants who have no training and basically learn on the job. If the attendant assigned to you has an iota of common sense, you should thank your stars. Else it is your job – that is the clients job – to train her on the ‘field’.
Hospice care/old age homes in India are in its infancy. Even those which are expensive comes with no guarantee of proper care. There is not much of a problem if the inmate is mobile and in good cheer. For bed-ridden patients, it could be a living hell.
The real reason we need money after retirement is to pay for such assisted living and medical expenses. They say death and taxes are the only certainties in life. Assisted living and taxes are the only certainties in retirement for most of us.
So the corpus that a retirement calculator coughs up is the bare minimum necessary after retirement assuming we have reasonable health. The point of this post is to emphasise that this a weak assumption.
This means that even a decent nest egg does not guarantee that we can be financially independent of our children. More importantly, we cannot afford to antagonize them! The way we deal with our children when we are young and fit, could well determine the way they deal with us when we are retired! That is scary!
So can anything be done about it? First, I will not assume expenses will decrease after retirement. Life will find a way to screw me and even things out. Second, I will do my best to invest as much as possible, higher than what a calculator says (if possible). Third, I will never forget the real reason I need money after retirement.
_____________
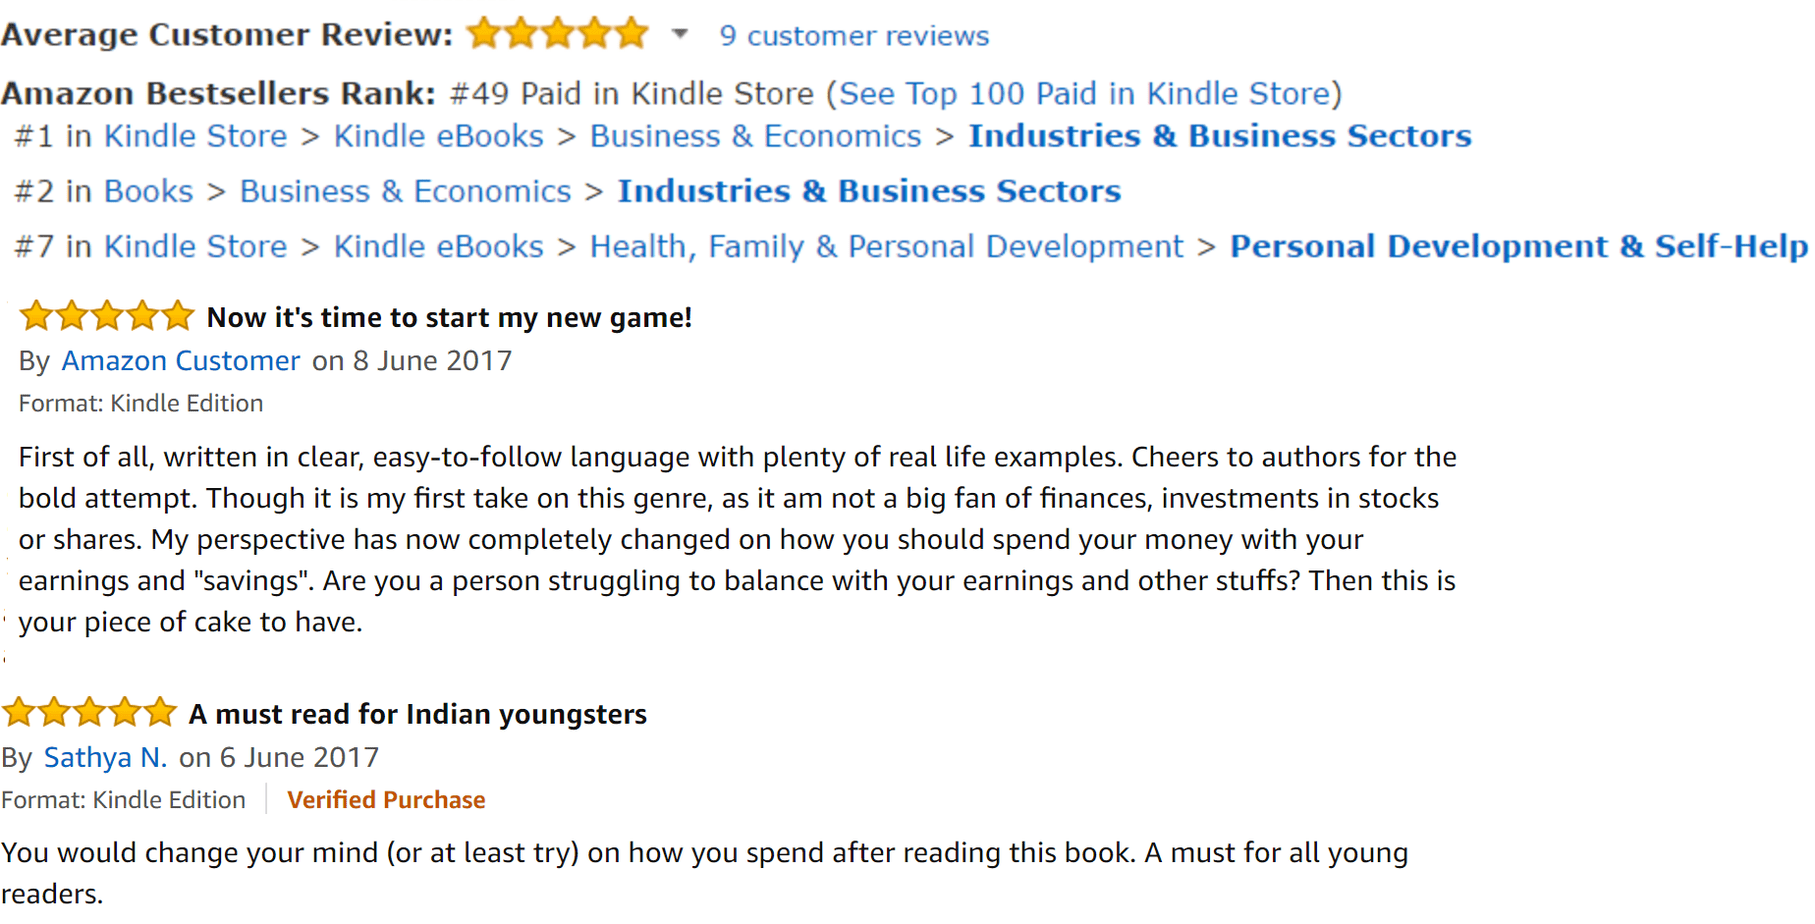
Thank you for the wonderful reviews of GameChanger!
Thanks to your support, the book hit #49 in the Kindle bestsellers last afternoon. You can check out the review via this link
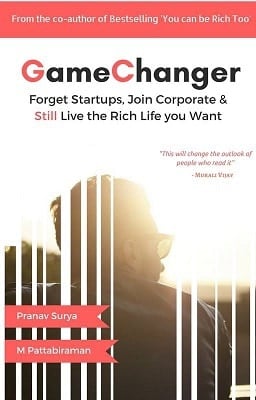
My second book, Gamechanger: Forget Start-ups, Join Corporate and Still Live the Rich Life you want, co-authored with Pranav Surya is now available at Amazon as paperback (₹ 199) and Kindle (free in unlimited or ₹ 99 – you could read with their free app on PC/tablet/mobile, no kindle necessary).
You can Be Rich Too with Goal Based Investing
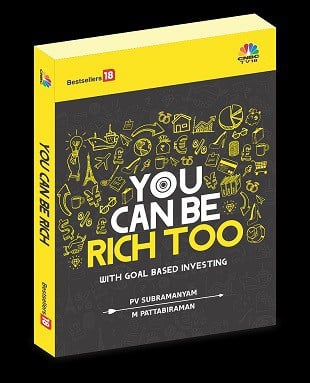
The book is available at:
Infibeam Now just Rs. 270 32% OFF. If you use a mobikwik wallet, and purchase via infibeam, you can get up to 100% cashback!!
Flipkart Rs. 279. 30% off
Amazon Hardcover Rs. 279. 30% OFF
Kindle at Amazon.in (Rs. 90.74 74% OFF) Read with free app
Google PlayRs. 90.74 Read on your PC/Tablet/Mobile
Now in Hindi!
Pre-order the Hindi version via this link