Last Updated on September 15, 2021 at 7:31 am
Here is a set of slides on retirement planning that I have used at the investor workshops. The aim is to convey the importance of retirement planning in a few slides to young earners.
1. Imagine how your monthly income will evolve in the future
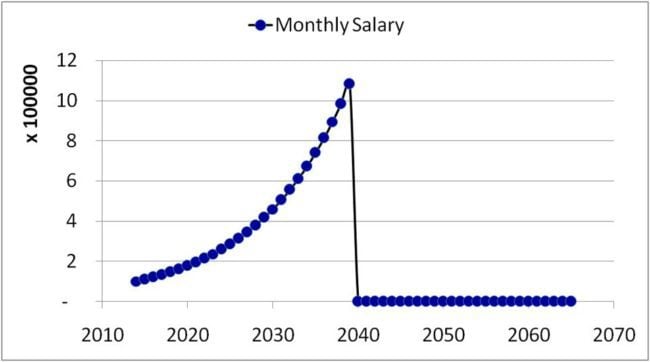
The abrupt stoppage in income represents retirement.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
2. Now imagine how your monthly expenses will evolve in the future
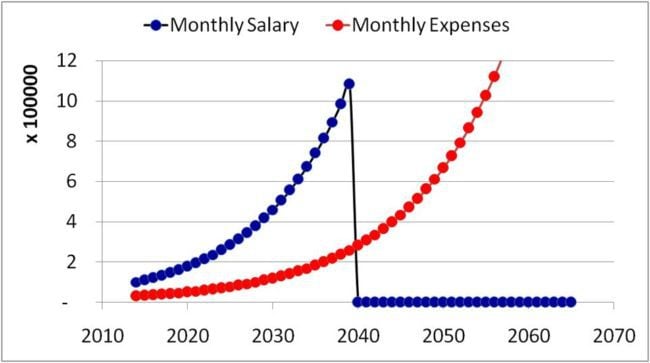
Obviously expenses do not stop when income stops. So those who do not have the means to account for expenses when income stops, better hope they are dead on or before retirement!
The expenses in the above graph seem to head for the roof. Let us rescale it over our expected lifetime.
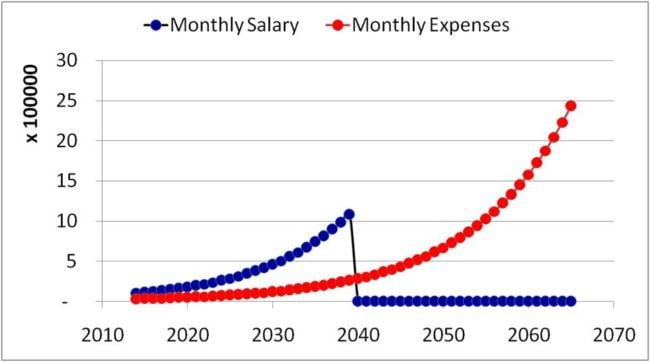
In about 15 years after retirement, the monthly expenses, thanks to inflation is higher the last drawn pay!
Meaning, if I had an (imaginary) monthly pension that equals my last drawn pay, I will only be financially independent for about 15 years after retirement. So we need to do a lot better!
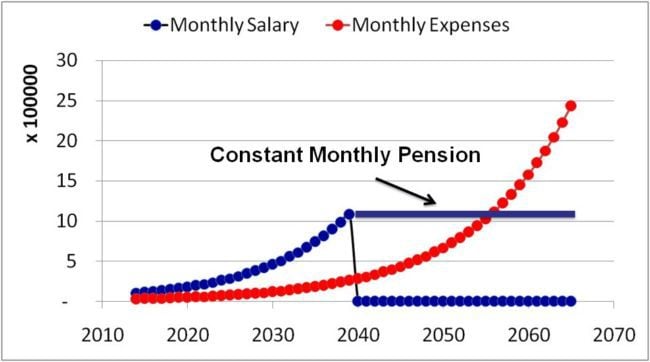
The sad truth is actual pensions (be it from a pension plan or employer-provided annuity) are much, much lower than the last drawn pay. Something like this.
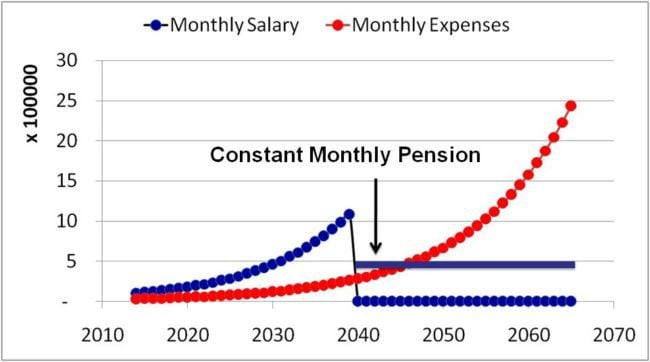
Therefore, for your own sake, eradicate the concept of a ‘pension’ from your minds.
Instead, think: Inflation-protected income (blue dot within the red circles, below)
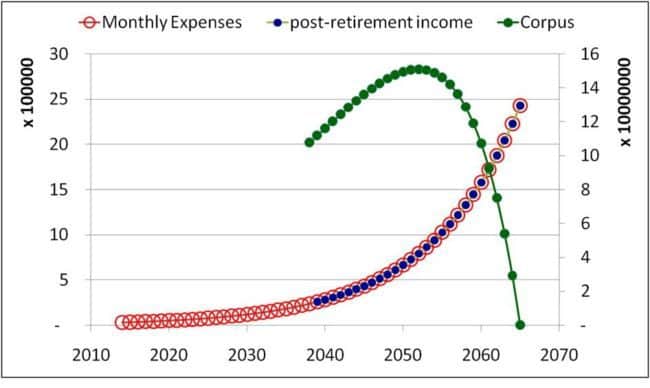
To generate this inflation-protected income, you need a corpus that is anywhere between ~ 25-35 times (depends on inputs) your annual expenses at the time of retirement (the earliest green dot). As you withdraw more and more from the corpus, it decreases and drops to zero hopefully when you die, and only when you die. Ensuring this, is the third stage in retirement planning.
The second stage is to ensure our investments grow and hits the first green dot, when we retire.
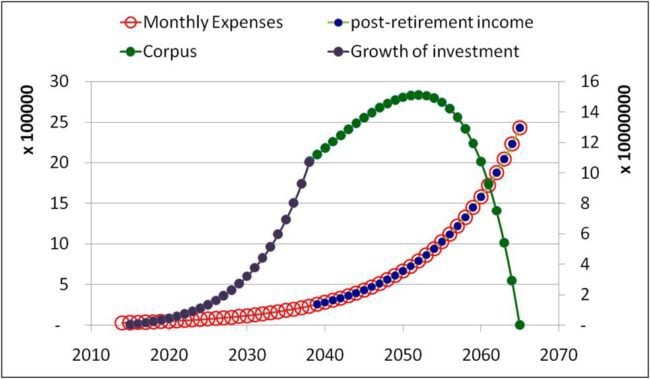
We need to do two things to grow the corpus. 1. Choose a productive, but diversified portfolio; 2. Invest
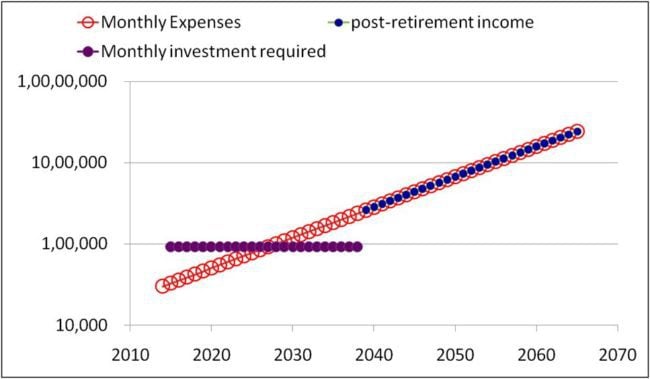
One cannot choose to invest a constant sum because, the monthly investment to be made immediately will be much larger than monthly expenses. The above graph has a logarithmic y-axis and hence the lines appear linear.
To ease our burden, we can instead choose to increase out investment each year from now until retirement.
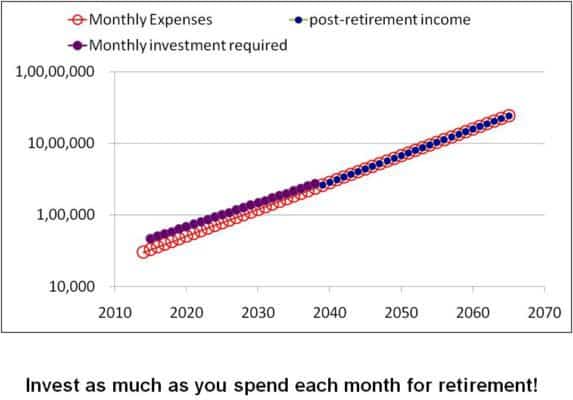
This would imply we must strive to invest as much as spend.
This is easier said than done. Let us have a look at the second graph again
Unfortunately,
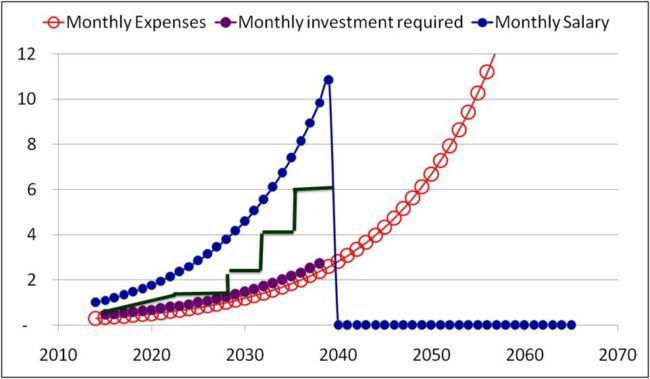
Our expenses tend to grow in steps as shown in green above. Call it lifestyle creep if you like. If we embrace every new technology that arrives, if we cannot distinguish between our needs and wants, if we succumb to peer pressure and buy what others buy, we will never be able to invest enough.
Meaning, we are sowing the seeds for our future financial doom today.
Lifestyle creep, the desire to spends for today and enjoy when young, resides in all of us. What is needed is a definite boundary: We can spend the way, we wish as long as we can manage to invest as much as we can spend.
Safeguarding that boundary is the first and foremost step of retirement planning.
If you want to get started with your retirement planning, do give this a try:The low-stress retirement calculator (hopefully!)