We recently showed that a mutual fund SIP will not help you reduce risk when the market falls! Inspite of seeing data that rupee cost averaging will not reduce risk or enhance returns in any tangible way, many investors keep “talking” about the “averaging benefits of SIP”. In this article, we show further and repeated proof that rupee cost averaging via SIP has no benefit other than accumulating MF units.
Important: We are not against the idea of investing in MFs or investing in MFs via SIPs. Systematic investing is an excellent way to build long-term wealth. Most of our net worth is invested in mutual funds and we strongly believe in systematic investing. However, having false notions about the SIP and believing false propaganda by those who have vested interest is ill-advised.
Blindly investing via SIP without a plan is like leaving the fate of our hard-earned money to luck. Yes the MF units will accumulate but their return is not determined by when you purchase those units. It is only determined by the final market value at the time of redemption or return calculation as shown below and in the above link.
The only benefit of SIPs is they allow the accumulation of MF units without having to worry about “when” to invest. From a behavioural point of view, systematic investing can easily trump market timing provided it is accompanied by proper planning. We are not trying to dispute this here!
In this article, we consider a SIP with market returns to show that SIP risk and reward reach market returns and stay there. This is an extension of similar studies over shorter durations: My lessons from investing in a midcap mutual fund via SIP for 12 years and Mutual Fund SIPs Do Not Reduce Risk! Beware of Misinformation, and SIP vs Lump Sum Investment: Which reacts to market changes more?
We shall consider a SIP in the Sensex price index from 3rd April 1979 to July 1st 2022 and compare it with a lump sum investment made on 3rd April 1979. The lump-sum is therefore a proxy for Senses returns. That is, the monthly variation in Sensex is equal to the monthly variation of the lump sum investment.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
In the graph below, we have normalised both investments wrt 1st July 2022.

After about 8-9 years after the start of the SIP (in the present), the variations of the SIP match the variations of the lump sum or that of the market. If the market moves up (down), the SIP value moves up (down).
Allow us to quickly point out that this 8 – 9 year number is not universally applicable. It is only relevant to this particular graph and depends on the metric used for comparison. It depends on the amount of lump-sum investment considered. The primary takeaway is that fluctuations in SIP value resemble that of market fluctuations after a few years – the number of such years is subjective and is not of practical relevance.
Why does this happen? Again allows us to quote our annoying bucket analogy. Consider two buckets sitting on an unstable platform, both empty to being with. About 80% of one bucket is filled with water. The other bucket is gradually filled with water with a small mug.
Initially, the swishing and swashing seen in both buckets are different. Gradually as the second bucket gets filled more and more with water thanks to our “systematic” mug-pouring, gradually both buckets splish and splash alike. When you pour water from the mug and how much the mug is full is irrelevant.
Today you start a monthly SIP for say, Rs. 100. After three years, the total investment is Rs. 3600 – this is a lump sum compared to the monthly investment. This lump sum will move up and down as per market conditions. When you buy units with that Rs. 100 and how many units you buy are irrelevant. The risk and return associated with the SIP investment are governed only by the market up and down movements.
Now let us consider the six-month absolute return of the SIP compared with the market (lump sum)
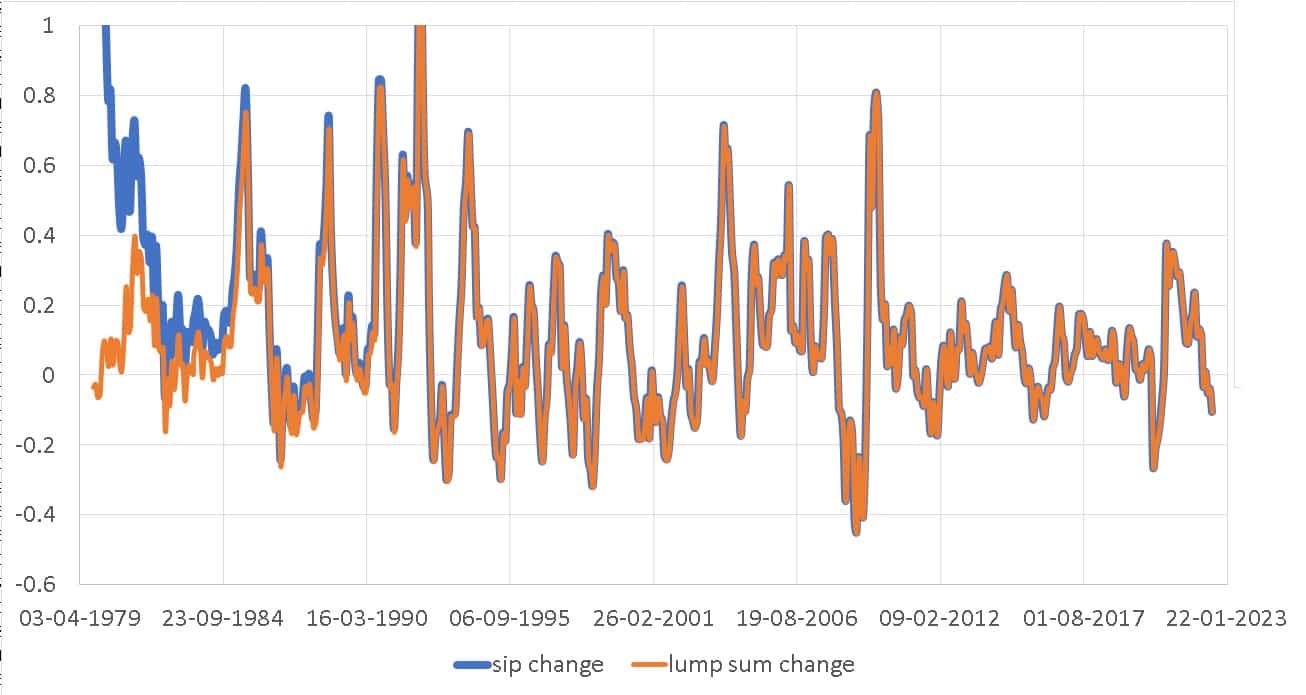
Notice the two are essentially identical after about five years after the start of the investment. This is the difference between the two absolute returns.
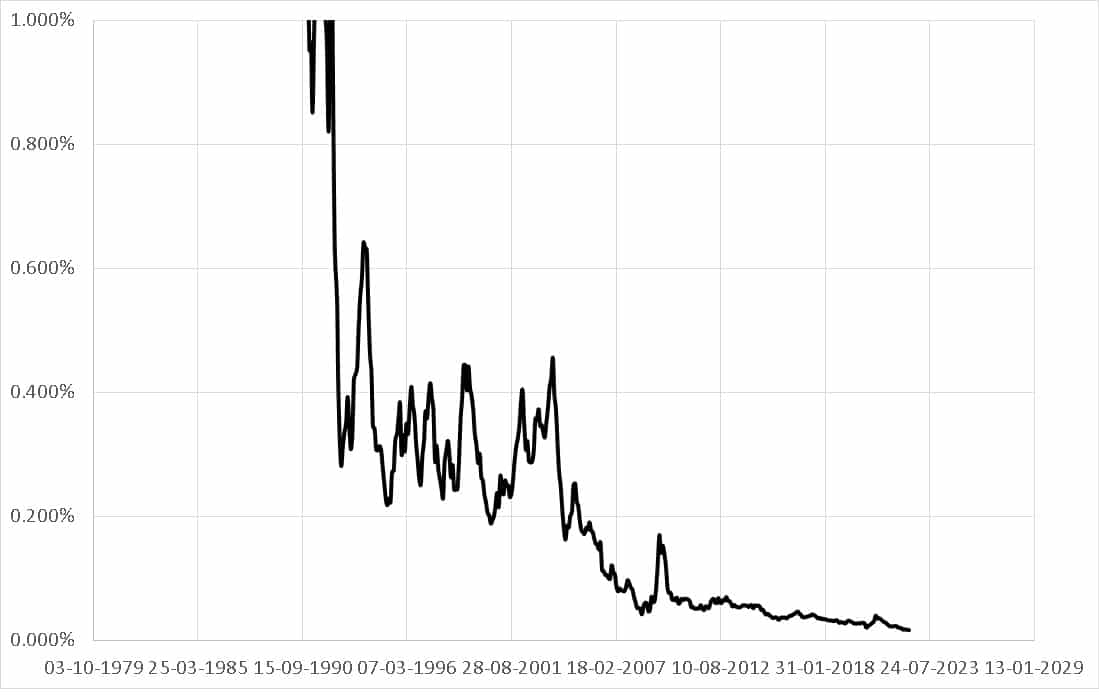
Notice how quickly the difference drops to insignificant values. Thus there is no difference in return between a long term SIP return and a long term market return.
Next, we consider the drawdown (fall from a max) – a measure of risk.
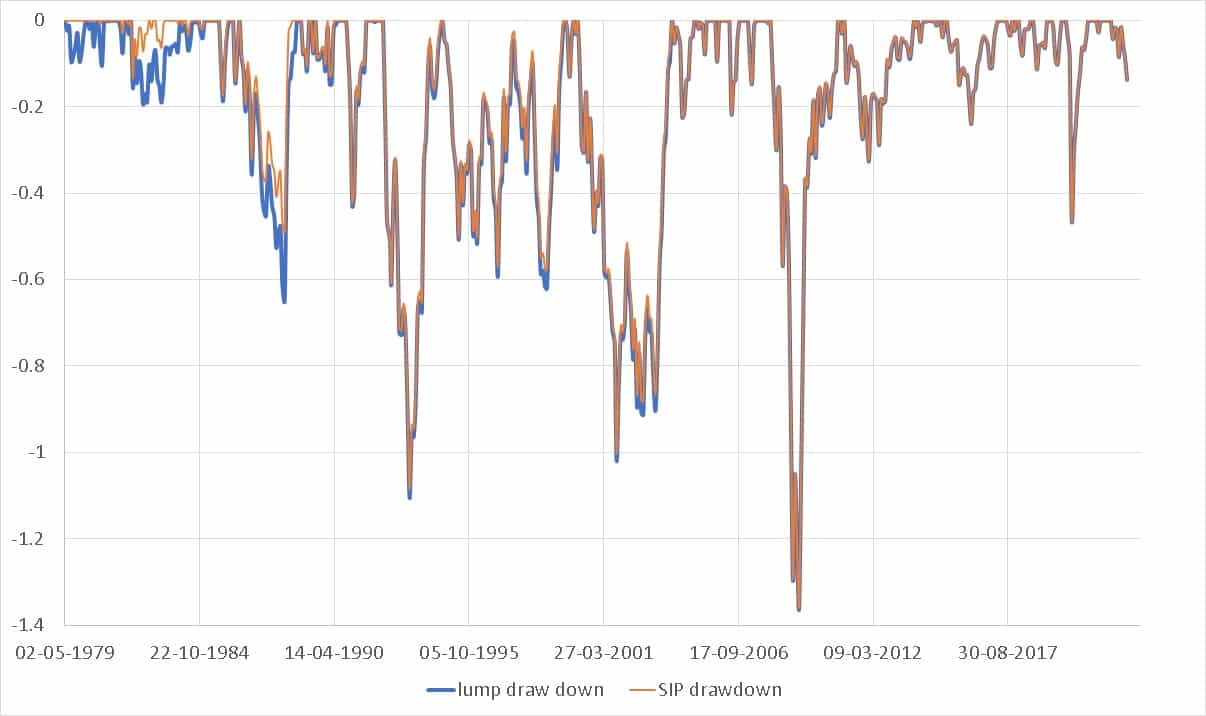
Again after a few years, the drawdowns are essentially the same. There is practically no difference in the volatility (another measure of risk) between a long term SIP (8.14%) and the market (8.13%) from 1990 to 2022 – we ignore the first few years when the SIP is trying to catch up with the market otherwise the SIP would be more volatile!
Thus we see that there is practically no difference between a long-term SIP and the market in terms of both risk and returns. The so-called “averaging benefit” of SIP does nothing more than accumulate units.
We reiterate that systematic investing (manually or automated) is an excellent way to accumulate MF units when done with a plan. However the “so-called” averaging associated with a SIP does nothing for its risk or returns.
There is no credibility associated with statements made by the MF industry such as:
- “Rupee Cost Averaging benefit in SIP may maximize our gains”
- “Rupee Cost Averaging benefit in SIP help when markets are volatile in nature” – markets are always volatile and in fact when the market moves sideways, SIP does not do well. See: Will a lump sum investment beat a SIP over 15 years?
- “SIPs help us get the average of good returns and bad returns” -Nope! They just give you market returns. There is no “averaging” of risk or return as shown above.
We encourage investors to systematically invest with the right expectations and not fall prey to MF industry propaganda.