Last Updated on December 29, 2021 at 6:17 pm
On June 7th 2021, SEBI introduced a “potential Risk Class Matrix for debt schemes based on Interest Rate Risk and Credit Risk” In this article, we explain what it is and discuss if it helps investors. The new rule comes into effect from 1st Dec 2021 but can be implemented immediately by fund houses if they desire.
We had earlier reported how the new mutual fund risk-o-meter is dynamic in nature: From Jan 2021, SEBI allows mutual fund risk to change each month like expense ratio! According to the June 2021 circular, the risk-o-meter will define the current risk level of the scheme and the newly introduced “potential risk class matrix” will represent the maximum interest rate risk and maximum credit risk a debt fund can take.
Hence we shall refer to this as the debt mutual fund maximum risk matrix. This shall set the bounds within which the risk-o-meter can vary. The matrix will like this to investors.
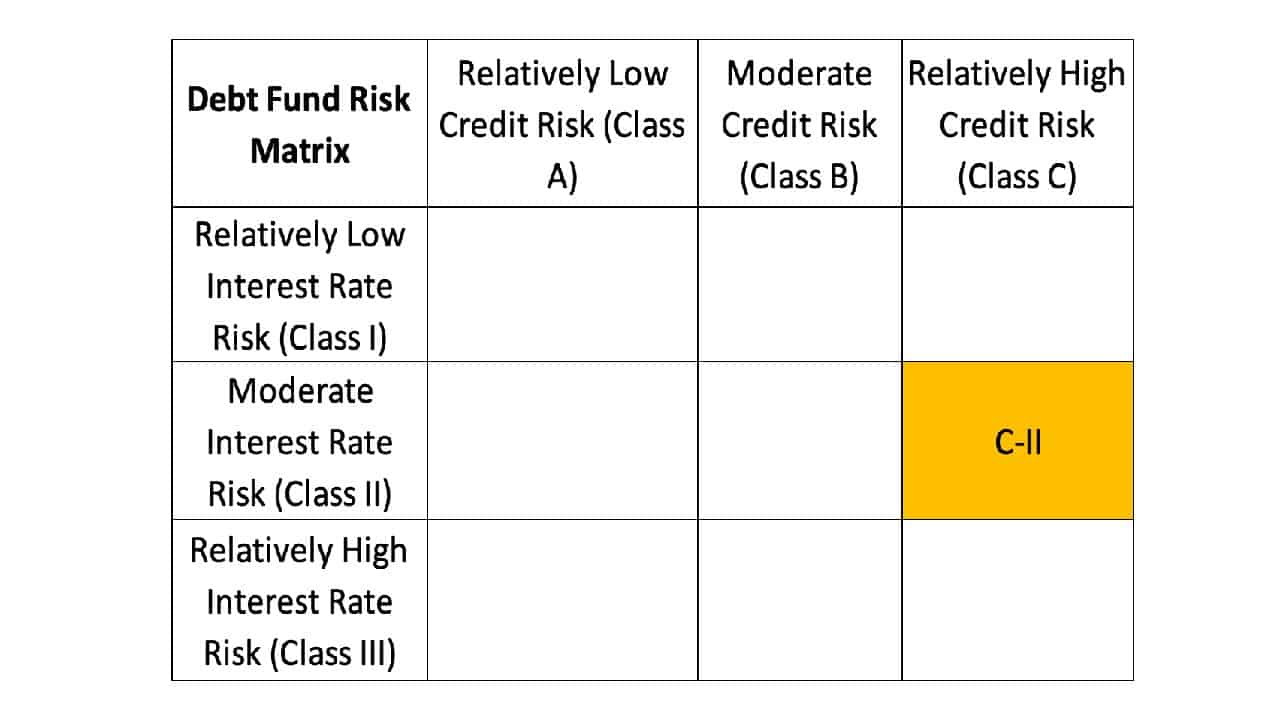
This refers to a fund with maximum risk levels of C-II. That is high credit risk (class C) and moderate interest rate risk (class II). If the fund revises its strategy such that it falls into a higher risk class, it will be considered a change in the fundamental attribute of the fund.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
The fund shall be allowed to make the change only after providing advance intimation to the unitholders and offer then a one month window to exit the scheme before the change is effected free from exit load.
For example, a shift from C-II to C-III in the matrix will be considered a change in fundamental attribute, while a change from C-II to B-II will not. Once the initial risk level is set, the scheme is free to lower the risk without informing unitholders.
This logic is a bit baffling. SEBI seems to be ok with unitholders suddenly seeing lower risk (and possibly lower reward) in the scheme and not vice-versa. Why not make both ways a change in fundamental attribute? That is only fair to those who wish to take on more risk.
Interest rate risk thresholds
1. Class I: MD<= 1 year (all bonds in the scheme should mature within 3Y);
2. Class II: MD<=3 years (all bonds in the scheme should mature within 7Y);
3. Class III: Any Macaulay duration (MD); <= New investments in perpetual bonds (e.g. AT1 bonds) can be made only by these schemes.
Classes I and II are reasonably confined, but III is too vague. The Macaulay duration will be the weighted average value based on the AUM allocation to different bond durations. Therefore investors should not go by the I, II or III classification. A scheme can take exposure to 20-25% of long-duration bonds, making the NAV more volatile and susceptible to shart drops or gains. To understand more about Macaulay Duration, please consult, Why you need to worry about duration if your mutual funds invest in bonds.
For a scheme placing itself in Class I (i.e. MD <=1 year), the maximum residual
maturity of each instrument held by the scheme shall be three years. For a scheme
placing itself in Class II (i.e. MD <=3 years), the maximum residual maturity of each
instrument held by the scheme shall be seven years. A scheme placing itself in
Class III can invest in instruments of any maturity.
Credit risk thresholds
This threshold shall be evaluated with a “credit risk value” or CRV.
1. Class A: CRV >=12
2. Class B: CRV >=10
3. Class C: CRV <10
The credit risk value for different bond ratings is given below. The overall CRV of the portfolio will depend on the weights of each bond.
- G-Sec/ State development loans/ Repo on Government Securities/TREPS / Cash 13
- AAA 12
- AA+ 11
- AA 10
- AA- 9
- A+ 8
- A 7
- A- 6
- BBB+ 5
- BBB 4
- BBB- 3
- Unrated 2
- Below investment grade 1
Thus higher the CRV of the portfolio, the better the credit quality. However, because both interest and credit rate thresholds are based on a weighted average, the investor cannot rest easy.
Consider a debt fund with a portfolio CRV of 12. So it would fall under class A. A naive investor might assume the credit quality in the portfolio is “good”. This need not be true.
A portfolio with 80% of govt bonds and cash and 20% of AA- bonds will also have a CRV of 12. That 20% has considerable credit risk. Therfore it is crucial that debt fund investors look carefully into the portfolio history and not just go by the current risk the fund can take (risk-o-meter) or the maximum risk the fund can take (the above risk matrix).
Is the maximum risk matrix for debt mutual funds useful? It is certainly a step in the right direction. It will help uninitiated investors appreciate that that risk in debt mutual funds can be classified into two: interest rate or duration risk and credit risk and provide a ball-park estimate of a debt funds risk positioning is.
It serves as a debt mutual fund 101 but is not enough to commit money in a fund. Because the matrix is based on weighted averages, investors must still carefully inspect the portfolio contents to fully appreciate where their money is being invested.