Last Updated on April 13, 2022 at 8:27 am
I am often asked this question. The catching up here refers to being able to create an adequate retirement corpus. The answer depends on the age of the person. For someone in the 30s (even late 30s), I think it is quite possible if they put their head down and invest enough for the next 15 years. This is part two of the Ugly Truth: How much should I invest for retirement?
Announcement: Gamechanger paperback is still available at a 25% discount for Rs. 149 only! Grab it or gift it to a young earner
Fifteen years is a lifetime when it comes to investing and with some luck and discipline, even a 40-year-old can make enough corpus to retire by 55 or so. Even by age 40, an exposure to 60% equity need not be risky. So it is not late at all. Only above age 45, the risk becomes too high even if the person has the appetite for it.
Let me punch in some rosy numbers for this post.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Age: 35
Current approximate monthly expenses (annual by 12) : 40,000
No of years you expect to work: 20 (retirement by age 55)
Inflation expectation: 7%
Life expectancy: age 85 (30 years in retirement)
Return expected before retirement from entire portfolio: 10% (after tax)
Return expected after retirement from entire portfolio: 9% (after tax: a tough ask, but please play along)
The rate at which monthly investment will increase each year from now until age 55: 10% (this is a big ask, may seem rosy now, but will get tough in a few year, but again please play along).
The amount at hand for retirement so far: 5 Lakh (this is not unreasonable for someone in 20-30% tax slab who has been work for at least 7-8 years now. The EPF corpus should be close to this.)
Rate of return on the above amount in future: 8%
The monthly investment required is 68% of monthly expenses (40,000) or about 27,000 a month. This includes the mandatory EPF contribution. You can consider a portfolio of 60% in equity and 40% in EPF. Possible or not?
Now, for the same set of assumptions,
- expenses increasing each year by 7%
- retirement at 55
- death by 85
- post-tax portfolio return pre-retirement: 10%
- post-tax portfolio return post-retirement: 9%
- Annual increase in monthly investment: 10%
- 5L growing at 8% each year
If the 35-year-old delays investing by,
- 1Y, the monthly investment required = 73% of the monthly expenses by age 36
- 2Y, the monthly investment required = 80% of the monthly expenses by age 37
- 3Y, the monthly investment required = 87% of the monthly expenses by age 38
- 4Y, the monthly investment required = 95% of the monthly expenses by age 39
- ….
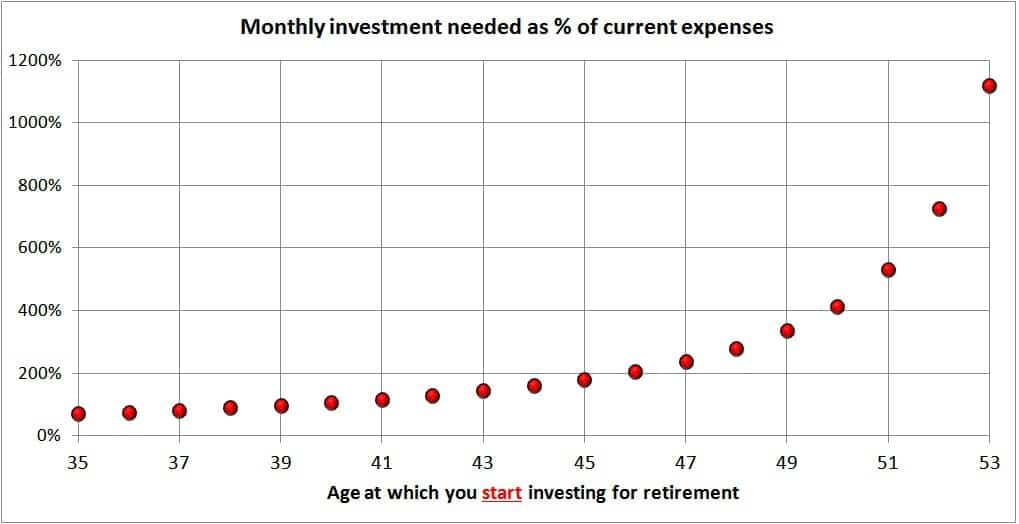
You can use this “Can I catch up?” calculator to punch in your own numbers.
Bottom line: Do not think about the past and regret. Invest as much as you can and invest right with hope, discipline and patience. If you want some motivation, here is a list of all stupid mistakes that I made until I started earning at age 32 (common for academics): The Financial Arrow of Time.