Last Updated on August 22, 2022 at 11:14 pm
We are studying the efficacy of a double moving average market timing model with different market indices. We have already established that the model reasonably works (see links below) with Indian gilts, Nasdaq 100 and the S&P 500. Our primary goal in this updated study is to illustrate market-specific risks and the sequence of returns risk with market timing.
Many readers have become excited about the model looking at its success so far. Please be patient until this series is complete! Do not jump to conclusions on the suitability or unsuitability of the model until all results are in.
Some readers have smirked that this approach is complex. It certainly is. We are discussing this market timing approach from a technical standpoint and our ultimate aim will be to discuss its risks. But then again everything has risks even systematic investing.
We should confuse something that is easy to understand (systematic investing) with something that is easy to do! Behavirouly all methods are difficult. We are not discussing behavioural aspects here. Experience has taught us that it is not our place to claim what is “simple” and what is not. There are different routes to approach the same destination.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Previous episodes in this series:
- Is it possible to time entry and exit from gilt mutual funds for better returns?
- Testing a double moving average market timing model (part 1): Nasdaq 100
- Testing a double moving average market timing model with S&P 500 (Part 2)
Warning and disclaimer: It must also be understood that market-specific risks and sequence of return risks are also applicable to systematic investing. The aim of this is to point out that no strategy (systematic or tactical) will work all the time and will work for all markets.
We have already established the above observation for systematic investing several times in the past. See: Do not expect returns from mutual fund SIPs! Do this instead! And Stock market always moves up in the long term but returns move up and down!
Past work: We have already established that the double moving average method is reasonably effective from an analyst’s point of view.
- Gold (1) Is this a good time to buy gold? A tactical buying strategy for gold
- Equity (large cap) (2) This “buy high, sell low” market timing strategy surprisingly works!
- Equity (Small cap) (3) Do not use SIPs for Small Cap Mutual Funds: Try this instead!
- Gilts (4) Can we get better returns by timing entry & exit from gilt mutual funds?
- We have also developed a tool based on this strategy: A tool for tactical buying and selling using moving averages
- For other tactical strategy backtests (eg. with PE), explore the Tactical Asset Allocation archives.
All our articles on the subject come with lengthy disclaimers about the risks of market timing. We now have an opportunity to showcase the risks with some hard data.
That said, we would also like to point out that the stance taken by the financial services community in general about market timing is wrong. If someone says “Mount Everest can never be claimed”, they are clearly lying. If someone says, “It is extremely hard to climb Mount Everest, then they are being pragmatic”.
The financial services industry has conveniently changed pragmatism (it is hard to time the markets) into a convenient lie (“the markets cannot be timed”).
Is it possible to the time the capital markets? The answer is a resounding “yes”.
Is it possible to find one timing method that will work all the time? The answer is a resounding “no”. Just like systematic investing will not be fruitful at all times, timing will not also provide a reward commensurate with risk at all times.
Can the typical retail investor pull off-market timing? Unlikely. Timing requires higher discipline than systematic investing (which is often nothing more than automation). Most investors fear taxes and avoid rebalancing. Tactical strategies require equity to debt switches or vice versa at least once a year!
At freefincal, we deal with facts. We do not moralise on right and wrong and fudge facts. If you are easily confused and believe less is more, then we recommend not reading this series.
They say “emotions cannot be backtested”. Fair enough. But then such people should not hail the merits of systematic investing for emotions wreak havoc there too!
Please recognise results shown in backtests do not factor in future market movements especially sharp price fluctuations and sequence of returns, human emotions, taxation and exit loads. All these would impact the outcome of market timing.
Tactical (double moving averages) vs Systematic Investing: Gold
For the test, we shall use Gold price per troy ounce in INR and USD from Jan 1979 to May 2022.
Systematic investing: A sum is invested each month in gold (USD or INR) over 5, 10 and 15 years.
Tactical investing: If the six -months moving average (6MMA) of the gold price is greater than the 12-month moving average (12MMA) then we invest in gold.
If 6MMA (green line in the image below) < 12 MMA (red line), then all gold holdings are sold and invested in debt. For gold INR, we consider a debt instrument with 6% per annum. For gold USD, we shall use 2.8% per annum. Tax and exit load due to the switches are not considered.
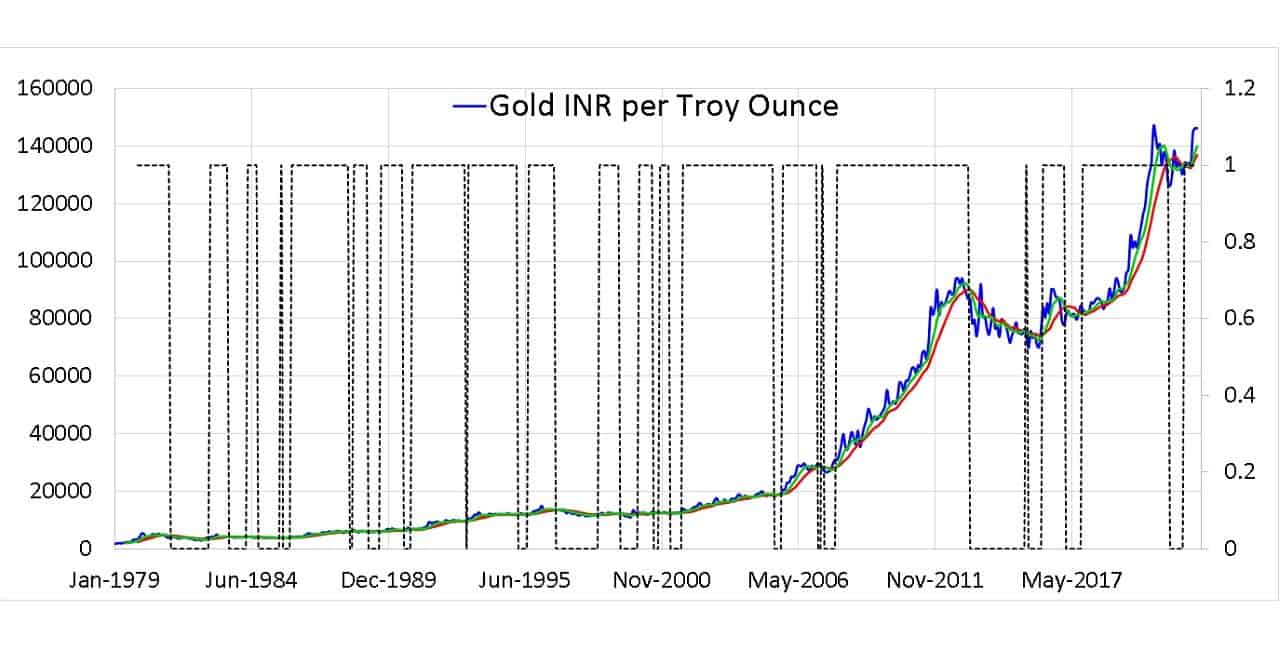
This is an example of a single 15-year run.

Gold INR
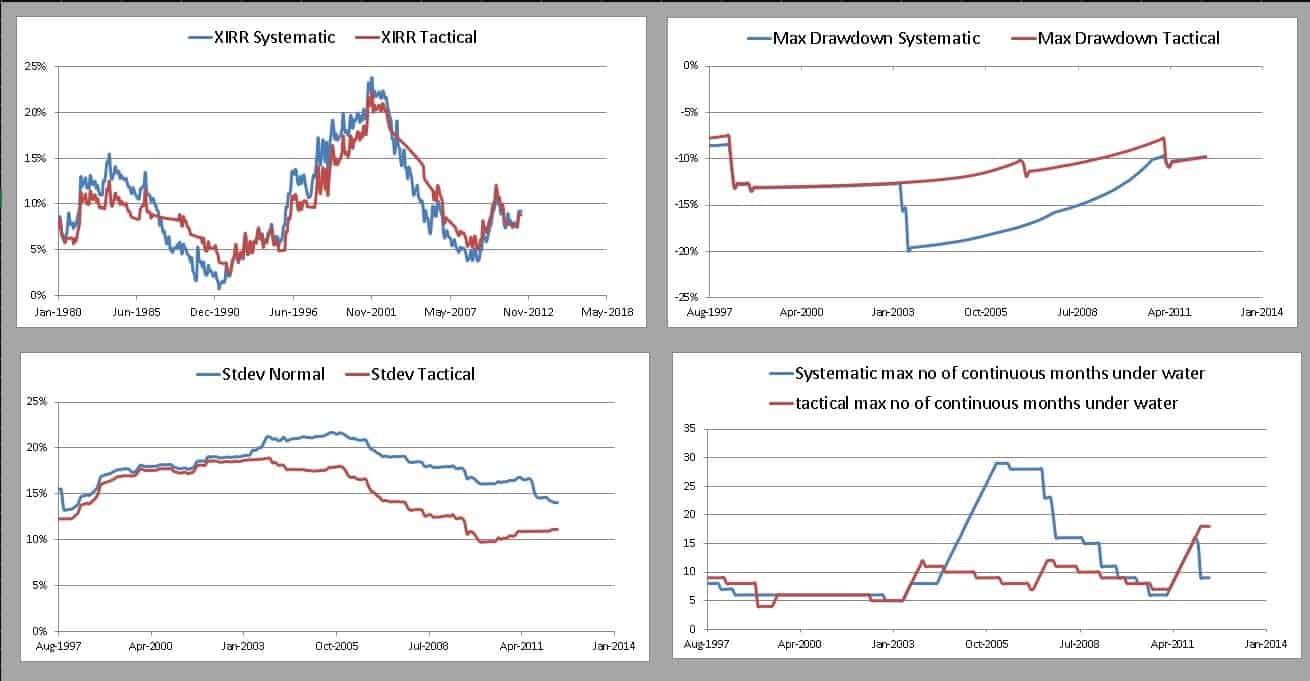
15 years: Between Jan 1979 to May 2022, 341 15-year windows (as the one above) are possible when rolled over monthly. The results for these are shown below.

Top left panel: the XIRR. The tactical strategy does not always win but it does not lose to the systematic strategy as well.
Top right panel: The maximum drawdown (max fall from peak) of the portfolio is shown (less negative the better). The tactical strategy often has a lower drawdown. That is lower risk.
Bottom left panel: The standard deviation or volatility (lower the better). The tactical approach has lower volatility.
Bottom right panel: the max no of months the portfolio was below its peak or underwater (lower the better). The tactical strategy recovers must faster.
This is to be expected as the systematic strategy has only gold and the tactical strategy both gold and debt.
10 years (401 periods)
5 years (461 periods)
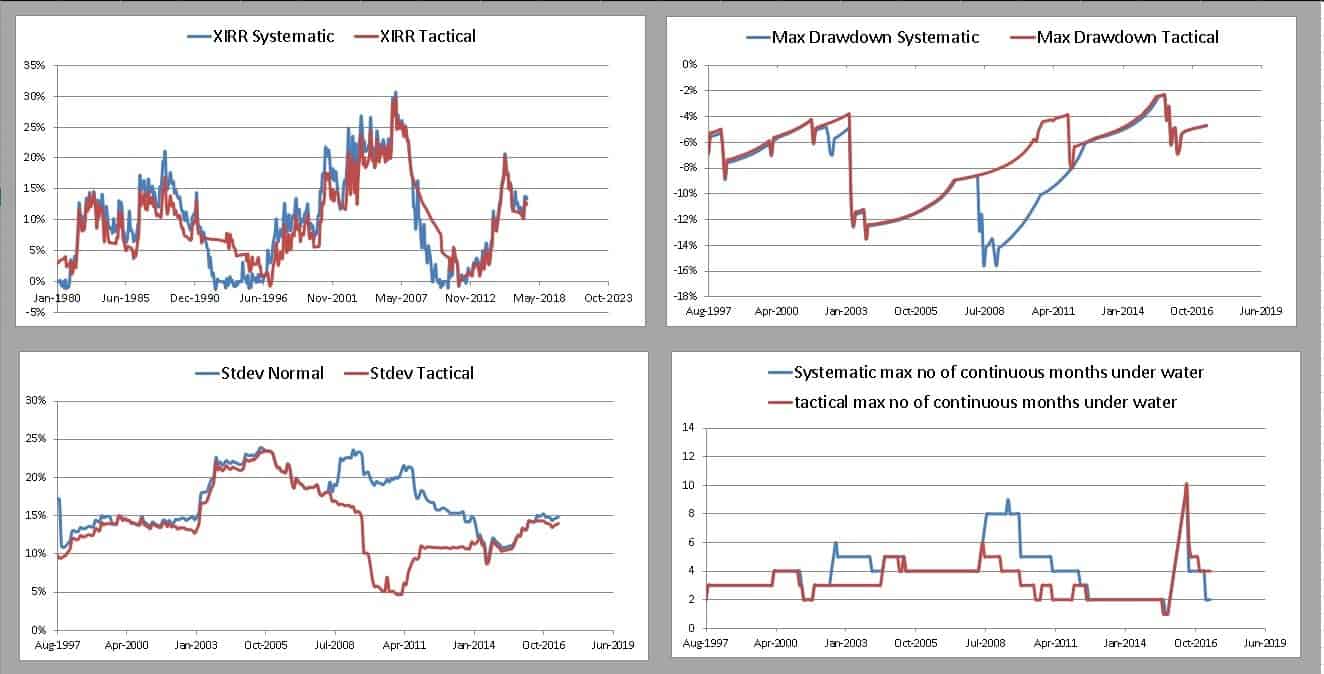
The results are similar to the 15-year data. Sometimes the tactical strategy typically has lower risk and sometimes higher return.
Gold USD
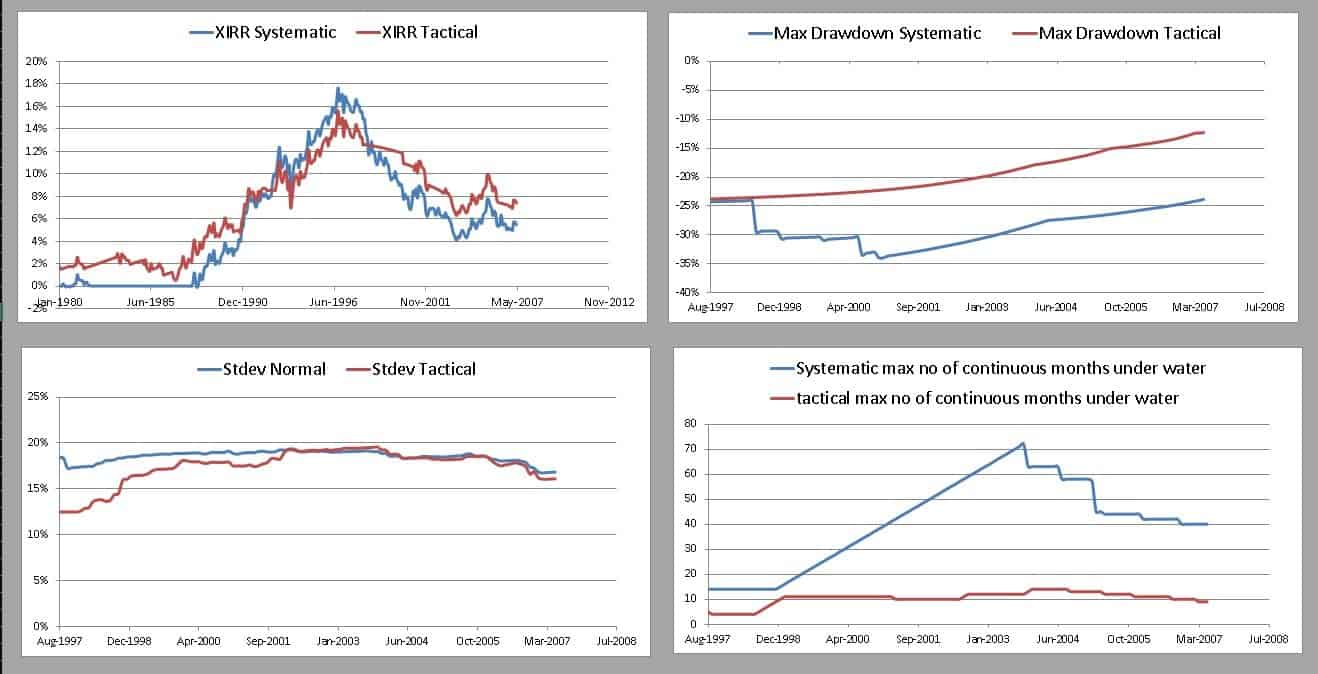
15 years (314 periods)
10 years (401 periods)
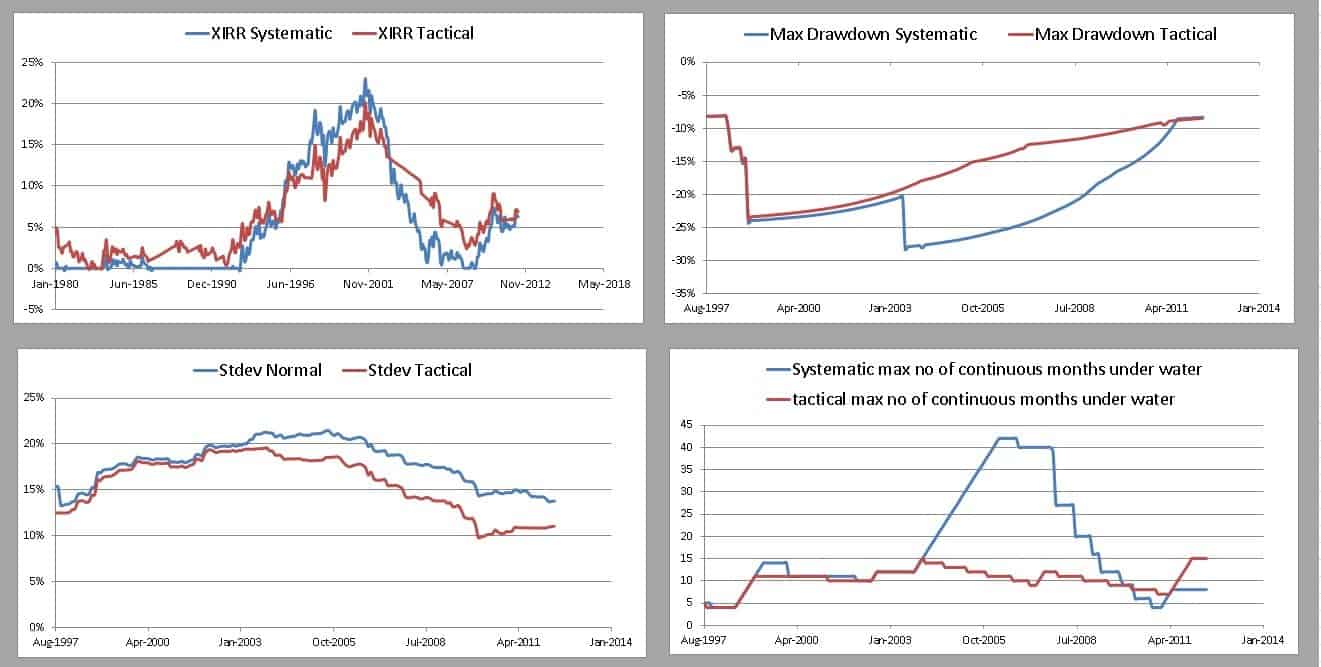
5 years (461 periods)
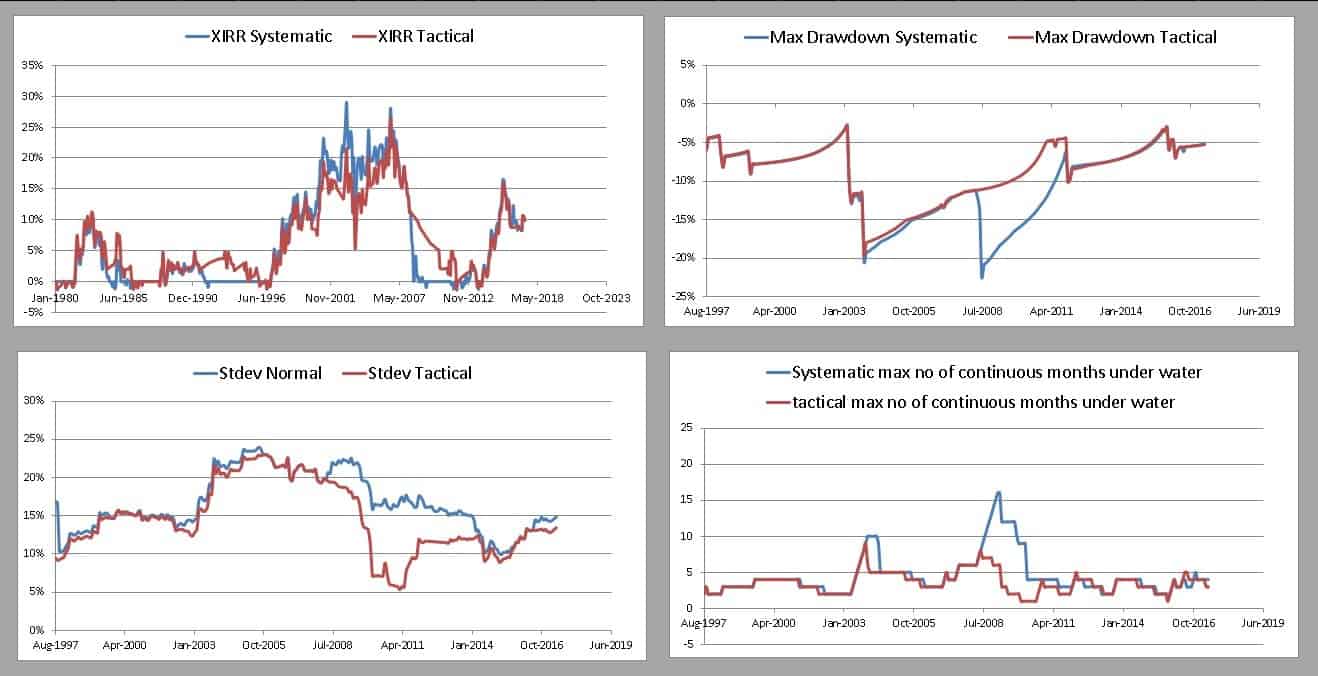
Over 10Y and 15Y, the margin of outperformance of the tactical strategy with gold USD is a bit higher than that with gold INR. The INR-USD rate seems to work in favour of systematic investing in gold INR.
So far we have used the double moving average strategy with gilt yields, Nasdaq 100 TRI, S&P 500 TRI and gold in USD and INR. While it does not offer better returns for all the periods tested, it does not fail badly either. In the next and final part, we find out how this model works with Indian indices.