Last Updated on December 29, 2021 at 5:35 pm
We discuss the basics of portfolio rebalancing: why do it, how to do it and when to do it, to address some of the common questions that investors have.
What does it mean to rebalance a portfolio? On the face of it, portfolio rebalancing seems like a simple enough, though ignored activity. you start with 50% equity and 50% fixed income, after a year, you find the allocation to 57% equity and 43% fixed income. So you remove 7% equity and buy fixed income with it or vice versa. We shall refer to this annual activity as systematic rebalancing. Also see: The What, Why, How and When of Portfolio Rebalancing With Calculators to Boot
Is rebalancing necessary? If you wish to invest with a plan in mind then yes. Rebalancing reduces portfolio risk, makes us sleep better at night and ensures gains from a well-performing asset is removed (before it is too late) and invited in an asset that is “down” or calmer (like say a liquid fund).
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
The primary goal of rebalancing is to reduce risk regardless of taxes and exit loads associated with the asset allocation reset. In a detailed July 2018 backtest the benefits of lower portfolio risk were discussed: Forget tax and exit loads, this is why your portfolio should be rebalanced each year. Also see: Understanding Volatility of Investment Returns with a Portfolio Rebalancing Simulator
Can I rebalance the portfolio by only adjusting investment amounts to avoid taxes? No, not for long. This is a common newbie investor question with not much net worth. So the amount already invested appears comparable to the amount to be invested each month. I do hope you want the situation to change and the amount invested to grow a lot bigger so that actual rebalance is necessary!
How should I rebalance my portfolio? Suppose you started investing Rs. 1000 a month in a Sensex index fund and Rs. 1000 a month in a gilt mutual fund. Your asset allocation is 50:50. After a year, the equity allocation is Rs. 9000 and the gilt allocation is Rs. 12,500.
The equity allocation is now 42%. So the task of rebalancing is to increase it to 50%. So 50% of (9000+ 12500) = Rs, 10,750. This means Rs. 1250 must be redeemed from the gilt fund and invested in the Sensex index fund.
Should I also rebalance within an asset class? Yes. If you hold large cap and mid cap stocks, for example, a similar rebalancing should be done to manage risk. The simplest would be to combine both inter-asset and intra-asset rebalancing.
I have multiple equity funds. Which should I use for rebalancing? This is the root cause of all confusion associated with rebalancing. If your equity allocation has increased from say 50% to 60%, then you need to remove 10%. The question is where from?
If most of the gains are from large caps (as was the case prior to the crash), then you can reduce some large cap exposure, push it to debt, look at the remaining equity portfolio and then make further adjustments as necessary – shift a little more from large cap to mid/small caps or leave it as is.
Investors need to recognise that “solved examples” will not help much as there are too many possibilities, each year is different and they need to develop the courage to stick to a plan and rebalance without fear.
When should I rebalance my portfolio? To answer the titular question, let us consider the options:
- (A) we can choose to never rebalance
- (B) rebalance once a year (aka systematic rebalancing)
- (C) rebalance if the portfolio deviates by 5% from the asset allocation (Akka 5% trigger rebalancing). For a 50% equity 50% debt portfolio, this means, the rebalance is done only if equity is higher than 55% or lower than 45%.
- (D) rebalance if the portfolio deviates by 10% from the asset allocation (Akka 10% trigger rebalancing)
- (E) Rebalance tactically. For instance see: This “buy high, sell low” market timing strategy surprisingly works!
We shall only consider options A to D in this study. Option (E) will also work but requires higher levels of discipline and is not for everyone. We shall consider three different portfolios: with 50% equity, 60% equity and 70% equity.
The backtest is done with Sensex and I-bex gilt index and 95 15-year rolling durations from Aug 1997- Aug 2013 to June 2005-June-2020. In each of the graph shown below, there are 95 data points in each line.
Please keep in mind: we are looking at a static asset allocation over 15-years. Goal-based reduction in equity exposure as the goal approaches are not considered in this study. To understand how to handle this crucial step, see: lectures on goal-based portfolio management
Rebalancing a 50% equity 50% debt portfolio
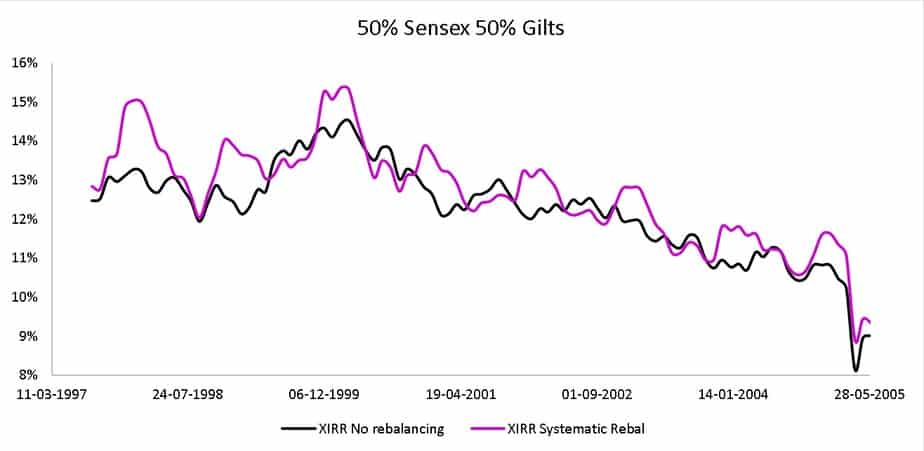
Amusingly, the systematically rebalanced portfolio beats the un-rebalanced one 69% of the backrests. Amusing because that was not the intention!
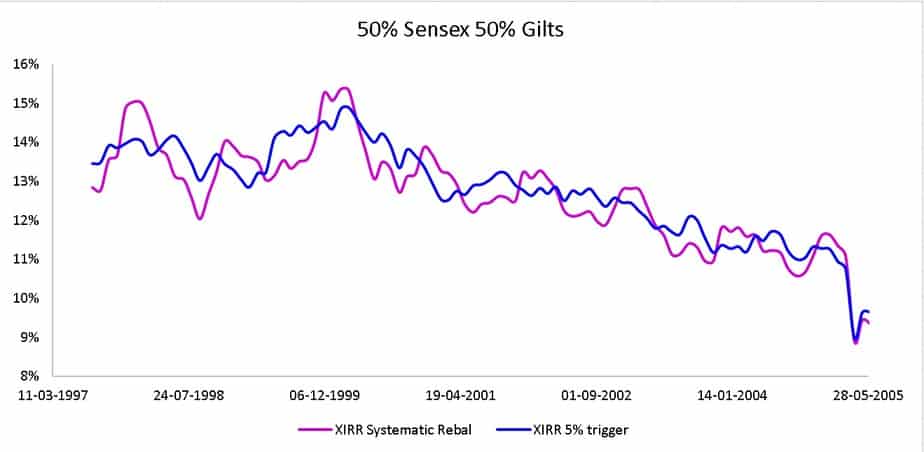
The 5% trigger rebalancing always beats the unbalanced portfolio and sometimes does better than systematic rebalancing.
The 10% trigger also does just as well. Both 5% and 10% triggers do better than systematic rebalancing about 60% of the 95 runs.
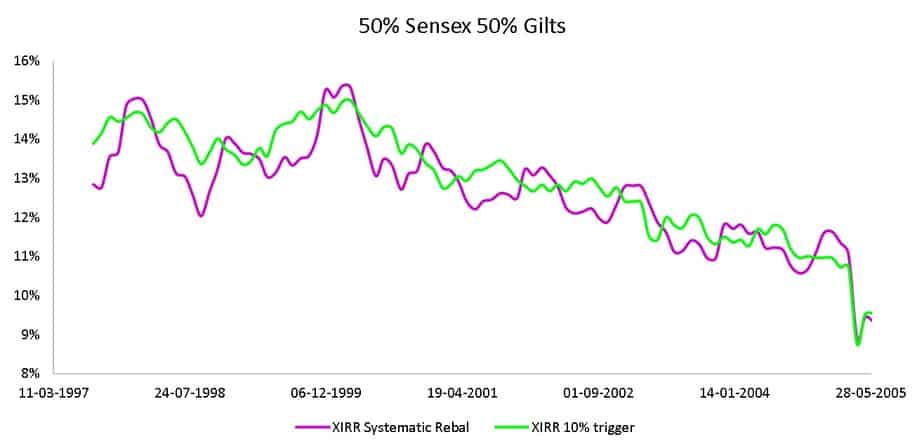
XIRR (% of runs the method worked better than the un-rebalanced portfolio)
- systematic: 69%
- 5% trigger: 100%%
- 10% trigger: 98%
Shown next is the maximum drawdown. That is the maximum the portfolio fell from a peak in its 15-year year journey. If this does not convince you to rebalance regularly, nothing else will.
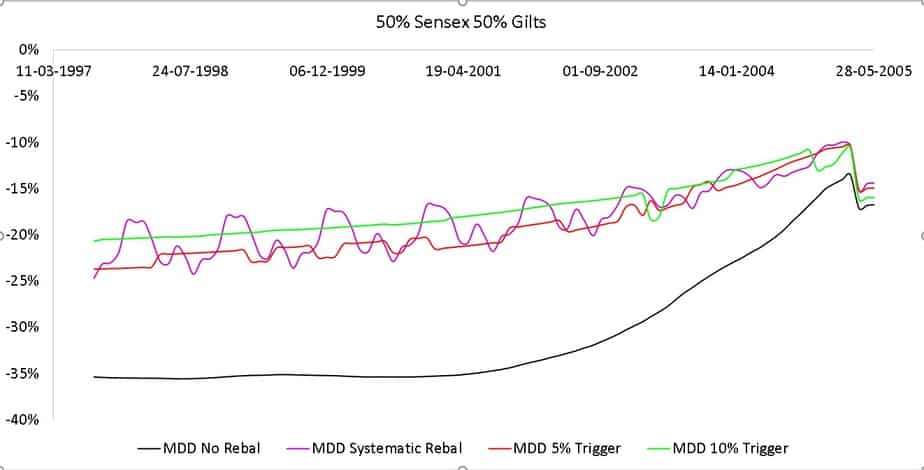
Next, we consider the maximum no of continuous months underwater. This means how long the portfolio was continuously below a peak. The higher this number, the higher the risk.
- Unbalanced: 20 months (typically = median and mode)
- systematic: 15-16 months
- 5% trigger: 16 months
- 10% trigger: 15 months.
Next is the portfolio ups and down month after the month measured via the standard deviation. Higher this value, more the volatility
- Unbalanced: 17%
- systematic: 14%
- 5% trigger: 14%
- 10% trigger: 14%
Finally comes the metric that chooses the winner. We have ignored taxes and exit loads. So the method that results in minimum rebalancing events minimises these costs.
No of rebalancing events
- Unbalanced: not applicable
- systematic: 15 times
- 5% trigger: 19-20 (typically = median and mode)
- 10% trigger: 5-6
Winner for 50% equity 50% debt portfolio: 10% trigger rebalancing. This much deviation can be tolerated because of the “balance” in the portfolio.
See: Will Benjamin Graham’s 50% Stocks 50% Bonds strategy work for India?
Rebalancing a 60% equity 40% debt portfolio
XIRR (% of runs the method worked better than the un-rebalanced portfolio)
- systematic: 71%
- 5% trigger: 14%
- 10% trigger: 33%
The trigger methods work better than the systematic method only 1% (5% trigger) and 18% (10% trigger) of the runs.
Maximum no of continuous months underwater
- Unbalanced: 20-22 (typically = median and mode)
- systematic: 16-17
- 5% trigger: 16-18
- 10% trigger: 16-18
Volatility
- Unbalanced: 19%
- systematic: 16%
- 5% trigger: 15%
- 10% trigger: 15%
No of rebalancing events
- Unbalanced: not applicable
- systematic: 15 times
- 5% trigger: 5 (typically = median and mode)
- 10% trigger: 2
Winner for 60% equity 40% debt portfolio: systematic rebalancing. It performs better and is emotionally easier to handle.
Rebalancing a 70% equity 30% debt portfolio
XIRR (% of runs the method worked better than the un-rebalanced portfolio)
- systematic: 73%
- 5% trigger: 19%
- 10% trigger: 38%
The trigger methods work better than the systematic method only 31% (10% trigger) of the runs and never (5% trigger).
Maximum no of continuous months underwater
- Unbalanced: 22-23 (typically = median and mode)
- systematic: 19-20
- 5% trigger: 18-20
- 10% trigger: 20
Volatility
- Unbalanced: 21%
- systematic: 19%
- 5% trigger: 17%
- 10% trigger: 18%
No of rebalancing events
- Unbalanced: not applicable
- systematic: 15 times
- 5% trigger: 4-5 (typically = median and mode)
- 10% trigger: 2
Winner for 70% equity 30% debt portfolio: systematic rebalancing. It performs better and is emotionally easier to handle.
To summarise, rebalancing is essential to reduce portfolio risk.In the set of limited backrests performed in this study, rebalancing actually manages to outperform (higher returns) a un-rebalanced portfolio. Though that should not be the motive to rebalance. For 50% equity, a trigger of up to 10% deviation works well but for higher allocations, systematic annual rebalancing does the job.