Last Updated on January 29, 2023 at 3:28 pm
From April 1st 2018, long term capital gains on stocks and equity mutual funds over Rs. one lakh have been taxed at the rate of 10% (plus 4% education cess) without indexation benefits.
P V Subramanyam of subramoney recently pointed out to me that we will be paying more tax on equity mutual fund gains in a few years than debt (or non-equity MF) gains. He suggested that I compute this scenario to know when this would happen. Long-term readers may know that I have often made calculators suggested by Subra, culminating in our book, You can be rich too with goal-based investing. The calculators part of this book is now available on SEBI’s investor education website.
Subra’s logic is as follows. The tax rate on equity mutual funds is a flat 10%. Soon the Rs. one lakh tax-free limit would be breached, and the tax will kick in. Non-equity mutual funds (any fund that does not invest in 65% or more of Indian stocks or Indian ETFs) benefit from indexation.
That is, the capital gain will not be computed as the sale price minus the purchase price (as is the case for equity funds). It is computed as the sale price minus the indexed purchase price.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
That is, we inflate the purchase price using the cost inflation indexation to the year of sale. In other words, we ask if we had purchased those non-equity funds units today (when we are going to sell), how much would the purchase price increase due to inflation? A detailed example is here: Taxation of international mutual funds explained with an example.
Subra argues that indexation-benefit can be immense over time. Even though the tax rate of non-equity funds is 20% (plus a 4% education cess), the tax is applied to the indexed capital gain. Therefore the effective tax rate reduces well below 20%.
If we assume equity outperforms debt over the long term, the tax on equity can be higher than on non-equity funds.
Consider an Rs. 1 lakh purchase in equity and non-equity funds simultaneously. Assume that the equity return is 10% and the non-equity fund return is 7% (we shall assume it is a debt fund). We also assume that the cost inflation increases yearly at an average rate of about 5%.
For these assumptions, after 12 years, the tax on equity is higher than the tax on the debt fund, as shown below. The chart starts from three years as we compare equity LTCG taxation with non-equity LTCG taxation.
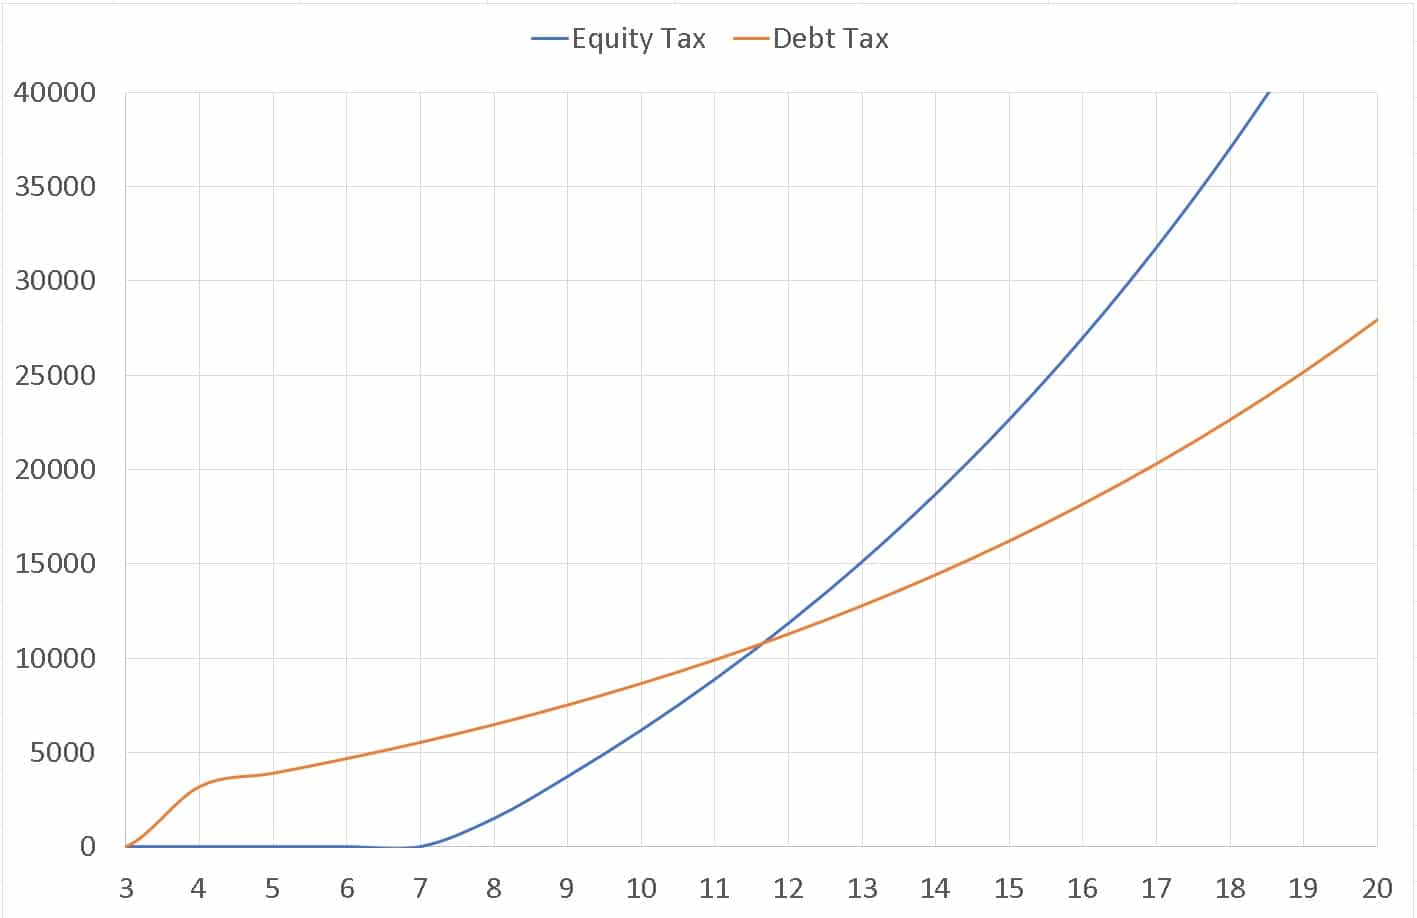
This is why Subra argues that we need indexation benefits for equity as well. The Rs. one lakh tax-free limit will not matter much if our gains are much higher. Over time the tax on this will increase compared to the non-equity LTCG tax, which comes with indexation benefits. Let us hope the government introduces indexation benefits for equity LTCG as well.
The calculator used to create the above graph is part of the freefincal investor circle. You can join the investor circle to get lifetime access to several unique tools, discussion forums, and bug fixes.
Author M T Raghunath prefers a different explanation. Readers may recall his investment book for newbies, Primer on Money and Investing: Fundamental concepts and first-principles-based understanding of money and investing.
Consider the following. An investment of Rs. 15 Lakhs in a debt MF versus an investment of 15 Lakhs in an equity MF. Assume that the returns are the same = 9% and inflation is 6%. In that case, the amount of money at the end of the period before taxes is the same regardless of which fund I had chosen.
Equity would have had higher volatility and is riskier, but here we are assuming that we got the same returns pre-tax because of the volatility or market performance. Now because of the indexation benefit, we end up paying less taxes on the debt returns compared to equity even though the debt rates are higher, and we have a 1L waiver on equity gains. This is illustrated below.
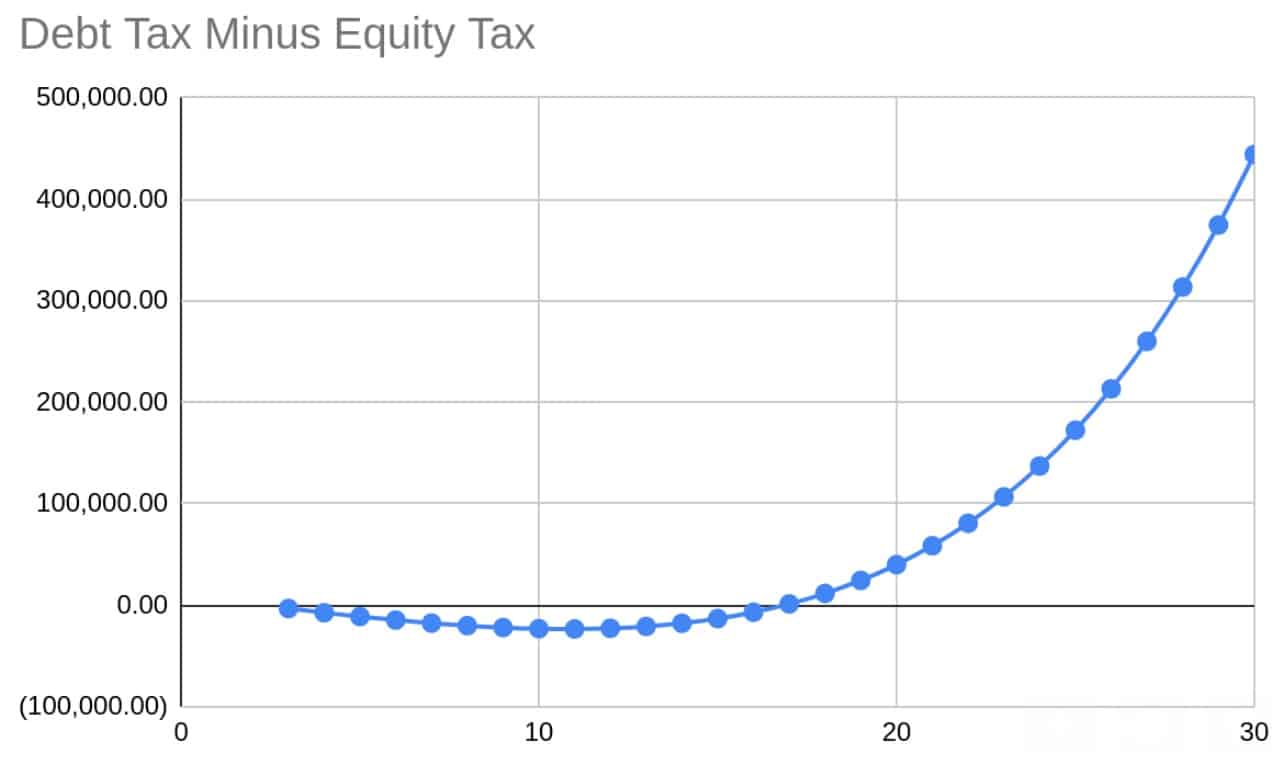
If the investment term is less than 16 years, we will pay more tax on the equity fund than the debt fund. We need that much time for the differential in the compound growth graphs to demonstrate the difference between the 10% and 20% post-indexation tax rates.