Last Updated on October 1, 2023 at 9:31 pm
If you are interested in achieving financial independence in retirement, especially if you hope to retire early, you’ve likely encountered the concept of the safe withdrawal rate, with the 4% rule being particularly well-known. However, it’s unfortunate that this rule is often misunderstood and misapplied, so it may not be a useful tool for retirement planning for most people.
What is a safe withdrawal rate? The safe withdrawal rate is defined as the annual withdrawal amount in the first year of retirement divided by the available retirement corpus. How is this connected to the 4% rule? What is “safe” about this withdrawal rate?
Assuming you retire with a corpus of INR 1 crore and invest it in yielding an overall annual after-tax return of 7%, this may seem like a straightforward retirement plan. However, it is important to note that this approach is simplistic and potentially risky. Additionally, factoring in an annual inflation rate of 7%, your expenses are expected to increase by the same percentage each year without accounting for any sudden increases.
So one crore is invested, and each year, you withdraw an amount equal to current annual expenses from it. Let us assume your expenses in the first year of retirement are Rs. 4 lakhs.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
The initial withdrawal rate is 4 lakh divided by one crore = 4%. This is the same 4% association with the 4% rule. Now the withdrawal rate in the first year of retirement is 4%. In the second year, the expenses are Rs. 4.28 lakh (7% inflation), and the corpus, after the first year withdrawal, has grown by 7% to Rs. 1.0272 Crores (Rs. 102.72 lakhs).
The withdrawal rate in the second year of retirement is 4.28/102.72 = 4.17%. The withdrawal rate keeps increasing as we draw more and more from the corpus. The corpus drops to zero after 25 years of retirement, and the withdrawal rate increases to 100%, as shown below.
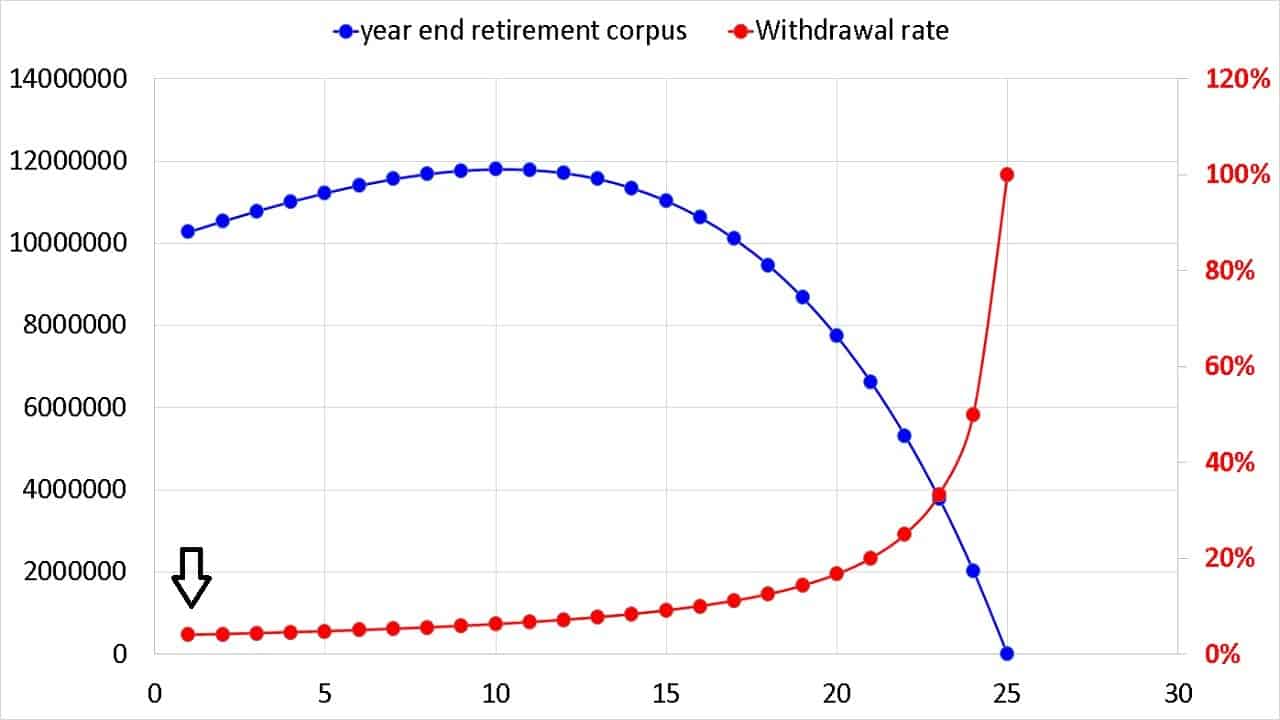
What is the 4% rule? The 4% rule is a rule of thumb for determining safe withdrawal rates in retirement proposed by William Bengen. In a Reddit AMA (ask me anything), Bengen explains the rule most eloquently as follows.
The “4% rule” is actually the “4.5% rule”- I modified it some years ago on the basis of new research. The 4.5% is the percentage you could “safely” withdraw from a tax-advantaged portfolio (like an IRA, Roth IRA, or 401(k)) the first year of retirement, with the expectation you would live for 30 years in retirement. After the first year, you “throw away” the 4.5% rule and just increase the dollar amount of your withdrawals each year by the prior year’s inflation rate. Example: $100,000 in an IRA at retirement. First year withdrawal $4,500. Inflation first year is 10%, so second-year withdrawal would be $4,950
You throw away the 4% or 4.5% rule after one year of retirement because it will keep increasing, as shown above. Unfortunately, the 4% rule has been misinterpreted as “the safe amount you can withdraw in any year of retirement.”
To be more precise, assume you are a financial planner. A client who is just about to retire comes to you and says, X is my retirement corpus, and Y is my annual expenses. How should I manage my money in retirement?
You compute the withdrawal rate in the first year as Y/X. Suppose this is less than or equal to 4.5%. Then there is a reasonable chance that the corpus will not reach zero before your lifetime. If the withdrawal rate is higher than this, then taking on capital market risk would be dangerous. However, how high is too high is arbitrary.
It is practical to define a safe withdrawal rate (SWR) as the following: If the initial withdrawal rate is less, or in other words, the corpus will last the lifetime of a retiree with a reasonable return and inflation expectations. We can refer to it as a “safe” withdrawal rate. If the expenses are too high or if the corpus is too low, the withdrawal rate will be high, and the corpus will get depleted soon if we keep withdrawing from it. Such a withdrawal rate is, therefore, unsafe, and the retiree will have to settle for a pension (annuity),
For example, in the above example, with a one crore corpus, if the initial annual expenses are five lakhs, the initial withdrawal rate becomes 5%, and the corpus will only last 20 years and not 25 years. What would you do then? Say this is too much risk, and buy a pension plan for as much of the corpus as possible? When do you say the retiree cannot take any risk? At 5% WR or 5.5% WR? No one knows. It becomes an opinion.
Most financial advisors in India do not have experience handling such cases, and to make things worse, because of conflict of interest, they would propose bizarre solutions such as monthly dividends or SWP from a “balanced advantage” fund.
The 4% rule is based on US historical data, but newer studies argue this even is flawed: The 4% retirement rule is wrong! Do not retire early in India (or the US) based on that!
Alternative to the safe withdrawal rate
The withdrawal rate can be misleading and easily misinterpreted. Many in the FIRE community assert they will maintain a withdrawal rate of less than 4% per year during retirement. However, this is only feasible if additional income sources are utilized alongside corpus withdrawals.
There are two problems here. (1) How much risk should a retiree take? (2) How should I manage my corpus after I retire in 10 or 15 or 20 or 25 years? Most retirees in India today have no capital market experience and not much of a corpus to play with.
We discussed the first problem in detail more than seven years ago (some return assumptions may need to be tweaked!): When should senior citizens purchase an annuity? The retiree would need at least 80-85% of the corpus required to generate inflation-protected income. If not, buying an annuity for most of the corpus is safer.
Those who have ample time to plan for retirement have some choices to work with.
- Ensure 15 years of inflation-protected income with an income bucket. One chunk of the corpus goes here. During this time, invest the rest corpus is divided among low-risk, medium-risk and high-risk buckets and managed actively. This is the logic used in the freefincal robo advisory tool.
- An alternative innovative variation of equity allocation in retirement is also possible, as discussed in the Online Course on Goal-based portfolio management.
Here are some sample illustrations using the robo-advisory tool.
- I am 30 and wish to retire by 50; how should I plan my investments?
- Retirement plan review: Am I on track to retire by 50?
- How to create retirement buckets for inflation-protected income
In summary, those who are years from retirement need not use withdrawal rates for their plan. Those who are about to retire may use the withdrawal rate in the first year of retirement alone to assess their risk-taking ability. We must understand that withdrawal rates are irrelevant after the first year.