Last Updated on February 12, 2022 at 6:13 pm
Here is another interesting question from a reader who wishes anonymity: I have the following question: Should I stop investing in mutual funds? I am a government employee working in academia. My income is stable, and I wish to retire at the normal age of 60.
My current age is 37, and so far, I have accumulated 50 lakh in mutual funds and NPS (almost 50-50%). I ran numbers on different calculators. I agree with Dr Pattu’s suggestions, about approx. 6-7 crore for my retirement. My monthly expenses are around 50K. Currently, I am saving 35K towards retirement and 15 K towards my son’s education. I am considering stopping mutual fund investments for retirement with the following scenario:
1) If I stop contributing to my MF portfolio, within the next 23 years, 50 lakh corpus will replicate thrice, and at retirement, it will be around 4 crores!
2) Being a government servant, I have a mandatory 20 % salary going towards NPS. Using conservative estimates and a 5% annual step-up, in the next 23 years, the NPS corpus will reach close to 2.5 crores! So I will have a total of around 6.5 crores at the age of 60!
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
3) Further, I am considering continuing savings towards education, use the remaining amount for A) buying a second home B) international travel per year. Do you think it is a practical option? I will appreciate your recommendation on the same.
Let us first consider the present situation of the person (Mr Q for short). He has about 25 lakhs in mutual funds and 25 lakhs in NPS (I am assuming standard govt asset allocation with a majority in gilts). The monthly expenses are about Rs. 50,000.
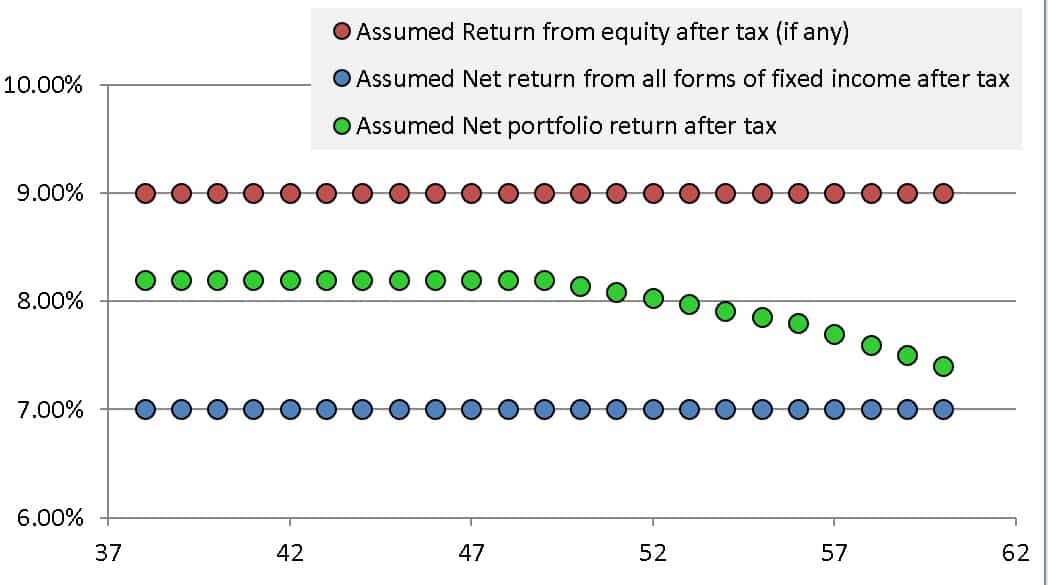
Let us find out if there are any red flags in the above assumptions: 50L becoming 4 crores in 23 years is equivalent to an annualized growth rate of 9.5%. Is this realistic? We need to keep asset allocation in mind. It is currently about 50:50. If we assume NPS offers a return of about 7% over the next 23 years (please don’t say I get 10% now – past tense!)
Let us assume equity mutual funds provide a return of about 9% (post-tax) after 23 years (I think this is a bit optimistic but let us roll with it). The 50L portfolio is left without maintenance (rebalancing) or withdrawals (touch wood!).
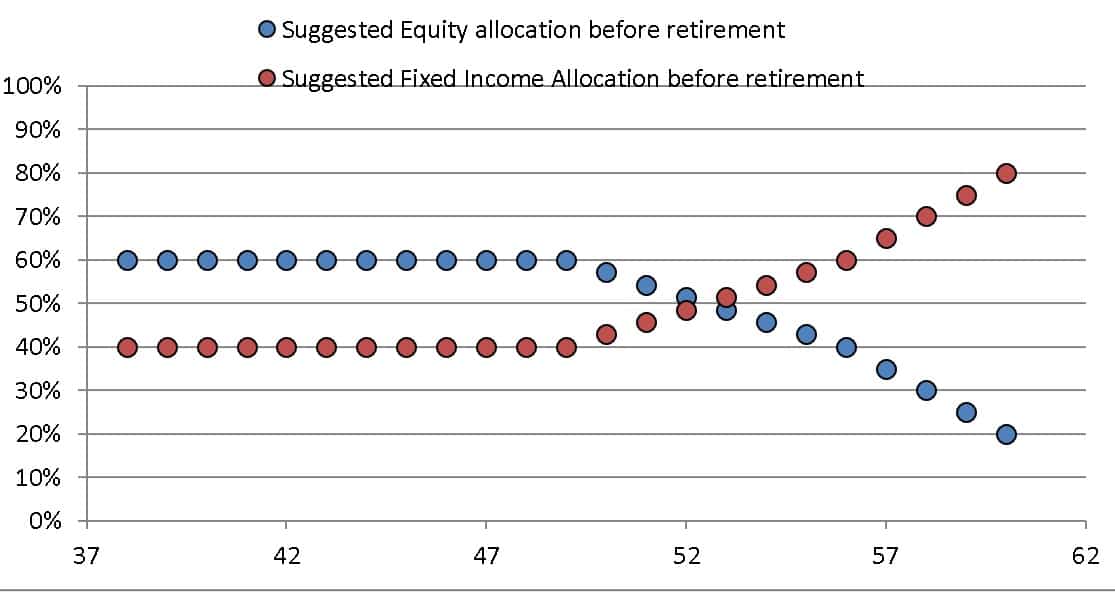
This would grow to about Rs. 3 crores, a good one crore short. Which is a bit too much. More importantly, unmaintained growth is impractical because out of this Rs. 3 crores, the equity component would be 60%. That is a bit too much (considering no further investments) at age 60. Regular rebalancing or a gradual reduction in equity allocation is likely to lower the corpus further.
The second assumption is that further contributions to NPS would result in a corpus of Rs. 2.5 crores. This depends on the return assumed and the current contribution, and future promotions. The 5% increase in contribution per year is easily possible. For a 7% overall return after 23 years, the current contribution should be about 25K. Only Mr Q can check this feasibility.
In any case, the second approximation seems a lot more reasonable than the first. I do not share his enthusiasm that 50L will become 4 Crores in 23 years without further contributions. I would urge him to continue investing for retirement as usual and draw out an equity reduction plan. This would mean investing more than what he does now!
For example, these are the asset allocation variations with return assumptions given by the robo advisory template for the inputs provided. The key point to note is, the investment amount will change as per this plan.
Better safe than sorry: Mr Q has made some safe assumptions on the inflation rate. Otherwise, the corpus is unlikely to be so high. However, the return assumption must also be reasonable and must consider an asset allocation with gradually decreasing equity. He could make a compromise of sorts by assuming about 7% inflation pre-retirement and 6% post-retirement.
After erring on the side of caution in every assumption possible, one can reduce investments (not stop) if there is no further need to invest for retirement! For the last few years, the temple has been telling me this (no need to invest anymore). I however continue to invest normally and increase my investments each year normally.
For example, my stock portfolio is technically tagged to retirement, but I can dip into it for my other dreams at any time. Therefore I would recommend that we never stop investing for retirement even if we don’t need to. We can always dip into the “extra” portion to fund our dreams or requirements in future.