Last Updated on June 26, 2021 at 11:19 am
Neils Bohr, one of the founding fathers of quantum physics, said, ”If quantum mechanics hasn’t profoundly shocked you, you haven’t understood it yet.” The same is true of retirement planning. When you sit down to do a retirement calculation for the first time, it should shock you. If it does not, you are probably making one of these mistakes.
If you have already experienced such shock, here are two inspiring accounts: We lost sleep after using a retirement calculator! This is how we recovered. And, This is how I plan to achieve five crores for retirement. Now let us consider some common mistakes made while planning for retirement.
1 Assuming unrealistic returns
It is quite easy to make a retirement calculation look rosy. Even today, you can easily find mutual fund distributors making projections with 12% or 14% returns (Btw it is illegal for mutual fund distributors to offer investment advice).
Assume for a moment it is possible to get 10% returns (before tax!) from an equity mutual fund (reality can be quite different, but let us play along). An investment portfolio can’t get a 10% return unless all the money is invested in it. That is, the asset allocation is 100% equity.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Obviously, this is far from practical. Even if we assume a person starts investing for retirement from day one of their careers, equity allocation can only be about 50% to 70%. The rest will be in fixed income. Even these high levels of equity cannot be maintained forever. The portfolio will have to be de-risked (equity allocation reduced) in steps well before retirement.
The portfolio return should be used while computing the monthly investment required from a projected retirement corpus, not the return from equity! Also, this portfolio return is not a single number but will gradually decrease as we reduce equity allocation. This is an example of how it works: I am 30 and wish to retire by 50. How should I plan my investments?
Takeaway: All returns used in retirement (or financial goal) calculation should be after-tax portfolio returns!
2 Assuming unrealistic inflation
The only inflation number that is relevant to us is the inflation in our own essential expenses. Not the inflation declared by the government. Results would look nice and rosy if we assume 6% inflation before retirement and 4% inflation after retirement.
Personal inflation (of only essential expenses) is likely to be closer to 8%. This is because of two reasons: Many services in India are unregulated (eg. Medical fees) and there is a gradual, irreversible improvement in our lifestyle. You can use this free Personal Inflation Calculator to check your own numbers.
Takeaway: For young earners 15 or more years away from retirement, we recommend using at least 8% inflation before retirement and at least 6% inflation after retirement.
3 Assuming we can beat inflation after retirement
Many in the “advisor” community and FIRE communities (financial independence and early retirement) happily assume a real return is possible after retirement. That is, they assume, after retirement, they would get a post-tax return higher than inflation on the entire portfolio.
Yes, it is important to include some equity in the portfolio during the withdrawal phase (after retirement), but too much can destroy financial independence. So assuming an overall portfolio return higher than inflation is unrealistic even for early retirement.
It is a mistake to plan with a single return number before or after retirement. We must account for how the corpus will be distributed in different buckets after retirement. This is an example: How much do I need to retire by 45 in India?
Takeaway: Do not go overboard with return assumption (equity allocation) after retirement
4 Extreme views about pension
Even today, many people believe all they need after retirement is a pension. On the other hand, young earners, particularly those seeking FIRE, believe there is no need for a pension after retirement.
Both views are extreme, incorrect and dangerous. Pension or a guaranteed income is valuable after retirement, but it cannot be the dominant component. At the same time, depending only on an SWP from a mutual fund is also dangerous. A balanced approach is necessary. See: Creating the “ideal” retirement plan with income flooring!
Takeaaway: Young earners should aim for a diversifed retirement portfolio consisting for pension, passive income, dividends, savings and investments
5 Be careful while estimating expenses!
While accounting for annual expenses, one should include one-time expenses like car insurance and health insurance. In addition, it helps to add about two months expenses as a buffer.
6 Using outdated inputs!
Retirement planning is a recurring exercise. Each year our circumstances can change, we realise returns from equity and fixed income may not be as high as it was in the past. All these inputs must be fed into the retirement calculator once a year to appreciate where we stand in our journey. This exercise should be continued even after retirement.
7 Delay: the worst retirement mistake
Not taking action is the worst retirement mistake. A single year lost in not investing enough can make a huge difference in the corpus we accumulate 15,20 years from now. This is an illustration from the Cost of Postponement Calculator!
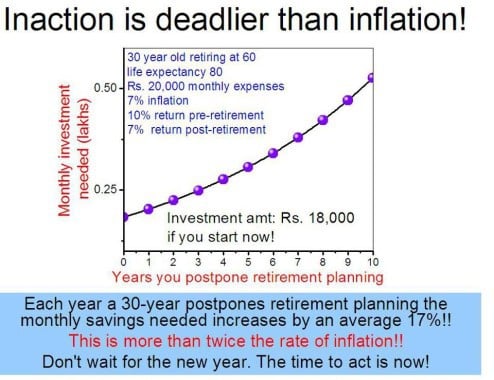
In summary, we recommend investors think about every stage of retirement planning and ask themselves, “are the assumptions justified?”, “can this be planned better in greater detail?”, “what if things do not occur as planned? Is there is a fail-safe mechanism in place?”.
We cannot feel too comfortable about our investment strategy. We must question it to make it better. If this is likely to make you more confused, then you are better off working with a SEBI Registered fee-only advisor.
If you wish to DIY and get started the right way, you can start here: Basics of portfolio construction: A guide for beginners