Last Updated on January 15, 2016 at 9:03 pm
Balanced equity funds or equity-oriented balanced funds are those with min 65% equity exposure so that they can be classified as equity funds by the taxman. The rest of the portfolio (35-25%) has debt securities (gilts, corporate bonds, money-market instruments etc.). Here is why I think these funds can match the returns of diversified equity
Here is why I think these funds can match the returns of diversified equity funds by taking significantly lower risks (approx. 33% lower in terms of the categories standard deviation).
Balanced equity funds are typically recommended by ‘experts’ to new mutual fund investors as a ‘less volatile option’. For a new investor, the volatility associated with 65-70% equity exposure is pretty much the same as that associated with 100% equity exposure.
However, for someone who understands the benefits of a balanced fund, they can the perfect choice: no-frills, low on expenses and most importantly low stress with a reward comparable to diversified equity funds.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Here are some benefits:
1) A single balanced fund is equivalent to an investment portfolio for long-term goals (1oY+). The equity and debt portfolio is independently diversified: across market caps, across bond types etc
2) Gains from the debt portion is available free of tax (as per current law)
3) The fund manager rebalances the portfolio periodically (each month if I am not wrong) and maintains the asset allocation without any tax implications or exit load. This is crucial to reducing volatility and preserving gains.
Balanced funds vs. Equity funds
1) Consider all 12-year-old balanced funds (hybrid equity oriented at VR). There are 18 such funds.
2) Consider all 12-year old large cap, large and mid-cap, mid and small cap and multi-cap funds listed at VR. There are 58 such funds.
3) Calculate the standard deviation of last 12-year annual returns. This is a measure of risk: that is ,by how much do returns each year can vary from the arithmetic average.
4) Calculate CAGR. This is for a lump sum investment 12 years old. XIRR for SIPs will be different. It is tough to calculate this for all 76 funds considered, but I would wager that the results will not be too different.
5) Plot CAGR vs the standard deviation. This is a plot of reward vs. risk.
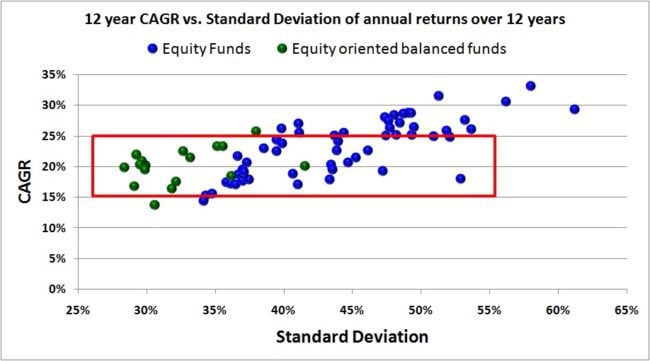
Lower standard deviation implies lower volatility and lower stress. Notice that most balanced funds have a lower standard deviation that equity funds. However, their returns are comparable!
A good 33 out of 56 equity funds are within the red box (between 15% -25% cagr) where all but 2 of the balanced funds reside.
To me, this looks like a terrific deal. I get comparable returns at much lower risk.
Most people will be happy with a 12-year cagr of 15% or even 13.7% – the lowest cagr which is by a balanced fund.
About 39% of the equity funds have produced a return higher than 25%, but only with considerably higher risk. Is it necessary for us to take on such high risk? Not for me thank you.
Two reasons: 1) I value my health and 2) I have better things to do than to constantly watch over my folio, market movements etc.
It is easier to invest in a dull and boring SIP when the volatility is lower.
Many say that it is a good idea to separate the equity and debt components of a portfolio. I agree. However, for a long-term goal, there is no need to do this right from the start.
The investor can start an SIP in a single balanced fund and let it run for a few years (with an annual review). For a 20 year goal, after about 5-7 years of investing, the investor can consider transferring some gains to a debt fund from time to time.
Alternatively, the investor can treat the balanced fund as a pure equity fund and have some debt allocation from the start. That is, ignore the debt allocation in the balanced fund and have a small (say 10-15%) separate debt allocation from the start.
One could even consider the balanced fund as 100% equity, invest 60% in it and 40% in a debt instrument.
There are are so many ways to play this.
Conclusion: Equity oriented balanced funds are not just for the newbie. They are for everyone.