Last Updated on October 8, 2023 at 1:46 pm
“Pessimism is a self-fulfilling prophecy”. These words by Sandeep keep ringing in my head all through the day. Two days ago I was chatting with a few friends on FB. I stepped out for a bit, and came back to find my less than 2-year old laptop screen say, “ disk not found”. A few days later the service person told me that the disk drum is broken. A new hard disk set me back by a few thousand and I am yet to know the cost of data recovery from the old disk – my guess, at least 15K.
Last month, I was shocked to find that the electricity bill for the last two months was a big fat zero! This is impossible as someone is always at home. Turns out, my neighbours had gone to the US and my EB meter was connected to theirs and vice versa. The wrong-connection was made in Sep. 2015. Since then we have been paying each others bill! So when I sat down to check, turns out I need to pay him about 10K!
Perhaps I am to blame for the first expense for taking regular backups (oh that is so boring), but the second expense?! That is the nature of emergencies. We can neither predict their source or nature.
Yes, a healthy emergency fund is essential, but it is important to recognize that the ability to replenish the fund after each emergency is more important.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
We can replenish the emergency fund from our salary, reduce the investments that we make for a few months or as a last resort redeem from some of our investments, depending on the nature or severity of the emergency. That is life, no amount of planning can help beyond a point.
The question is, how are we going to handle emergencies after retirement? Especially when so many of us dream and plan for early retirement? I cannot live without a PC today. It is where I work, read, engage socially and get entertained. So if the PC fails, it is an emergency for me and it could well be for the rest of my life. I have regularly spent new PCs or repairs every other year. So it is practically a regular expense that will persist after retirement.
Imagine if the electricity meter situation had hit a senior citizen in the 5% or 0% slab with most of the income from pensions and interest. A sudden expense of a few thousand (will not as big as mine, but still) will rock their boat. How do you think the retirement crisis gathers momentum?!
Well, the point is, people who use my retirement calculators complain that I am being pessimistic and those who read my early retirements posts or e-book refer to me as “that conservative author”. Such expenses justify my conservative stand.
Once the salary stops, our ability to handle emergencies will take a beating, unless we have a large enough corpus. In order to have a large enough corpus, we must invest with the right asset allocation and strategy and invest as early as possible. More importantly, we must invest enough.
We will invest enough only if we err on the side of caution and work with at least 8% inflation and only 10% return on equity. Change these numbers today in the assumption that “it will all turn out fine” or “God is there” and invest less, then a single emergency can crack our financial castle.
Bottom line: invest at least as much as you spend today, preferably more. As they say, pray for the best, but prepare for the worst.
If only optimism was a self-fulfilling prophecy!
Ask Questions with this form
And I will respond to them coming Monday. I welcome tough questions. Please do not ask for investment advice. Before asking, please search the site if the issue has already been discussed. Thank you. PLEASE DO NOT POST COMMENTS WITH THIS FORM it is for questions only.
[contact-form][contact-field label=’Name’ type=’name’ required=’1’/][contact-field label=’Email’ type=’email’ required=’1’/][contact-field label=’Comment’ type=’textarea’ required=’1’/][/contact-form]
GameChanger– Forget Startups, Join Corporate & Live The Rich Life You want
My second book, Gamechanger: Forget Start-ups, Join Corporate and Still Live the Rich Life you want, co-authored with Pranav Surya is now available at Amazon as paperback (₹ 199) and Kindle (free in unlimited or ₹ 99 – you could read with their free app on PC/tablet/mobile, no kindle necessary).
It is a book that tells you how to travel anywhere on a budget (eg. to Europe at 50% lower costs) and specific investment advice for young earners.
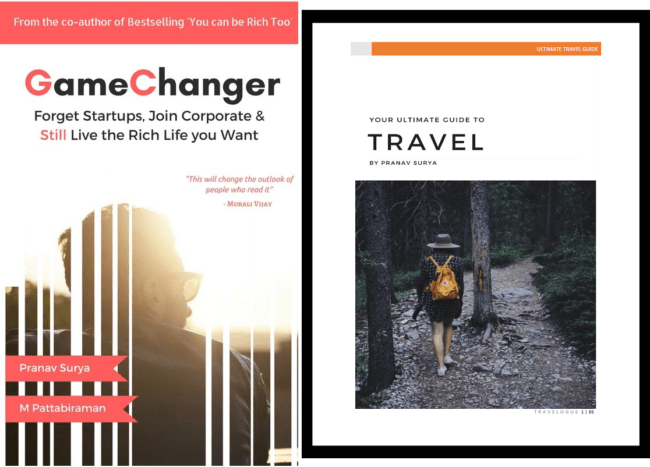
The ultimate guide to travel by Pranav Surya is a deep dive analysis into vacation planning, finding cheap flights, budget accommodation, what to do when travelling, how travelling slowly is better financially and psychologically with links to the web pages and hand-holding at every step. Get the pdf for ₹199 (instant download)
You can Be Rich Too with Goal-Based Investing
My first book with PV Subramanyam helps you ask the risk questions about money, seek simple solutions and find your own personalised answers with nine online calculator modules.
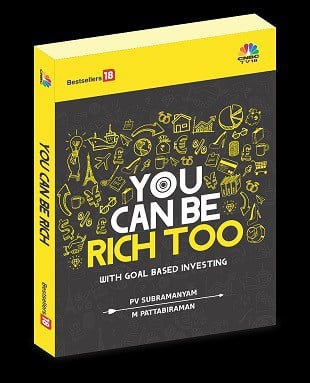
The book is available at:
Amazon Hardcover Rs. 271. 32% OFF
Infibeam Now just Rs. 270 32% OFF. If you use a mobikwik wallet, and purchase via infibeam, you can get up to 100% cashback!!
Flipkart Rs. 279. 30% off
Kindle at Amazon.in (Rs.271) Read with free app
Google PlayRs. 271 Read on your PC/Tablet/Mobile
Now in Hindi!
Order the Hindi version via this link