Last Updated on February 12, 2022 at 6:21 pm
Suppose we have Rs. one Crore with us today, can we retire with it? Let us punch some numbers in the freefincal robo advisory template and check what good is Rs. 1 Crore.
One Crore is a psychological or emotional benchmark for wealth. Financially it is just one followed by seven zeros with its value constantly eroded by inflation. That said, it is still a good chunk of money as we shall see below.
Assumptions
Every projection will have assumptions and the following are made in the robo advisory template
Inflation before and after retirement: 8% (to a small extent, this can factor in lifestyle changes)
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Life expectancy: 85 years (could be more, but on average, this is reasonable)
Return from equity: 10% (better to be cautious and this could be the case a couple of decades from now)
After retirement return from instrument providing income is 6% (post-tax)
Return from fixed income (used as investment) is 7% (post-tax).
The retirement corpus (when possible) will be invested in four buckets:
B1: income for first 15 years in retirement
B2: low -risk bucket with 20-50% equity depending on age of the retiree
B3: Medium-risk bucket with 30-70% equity (again age dependent)
B4: High-risk 70% or 100% equity.
While B1 provides inflation protected income for the first 15 years in retirement, B2, B3, B4 grow for later use.
In this example, if one crore is less than the total corpus necessary to invest in the four buckets, a much simple suggestion will be provided.
We will assume emergencies will be handled from other sources. This is a weak assumption, but do play along.
There are some more details, but let me not bore you with them. On to the examples for all ages from 60 to 30.
A 60-year old with Rs. 1 crore
Monthly expenses: Rs. 60,000 + another Rs. 60,000 for annual expenses (say health insurance)
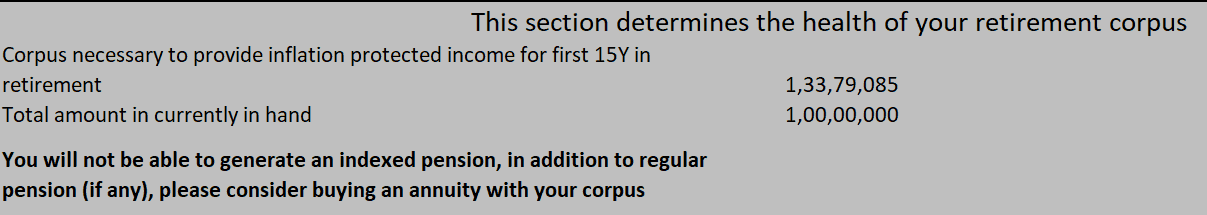
There is not enough money to provide inflation protected income for the first 15Y. Taking any form of investment risk is ill-advised. So the robo says: Buy an annuity and seek constant pension.
Monthly expenses: Rs. 40,000 + another Rs. 40,000 for annual expenses
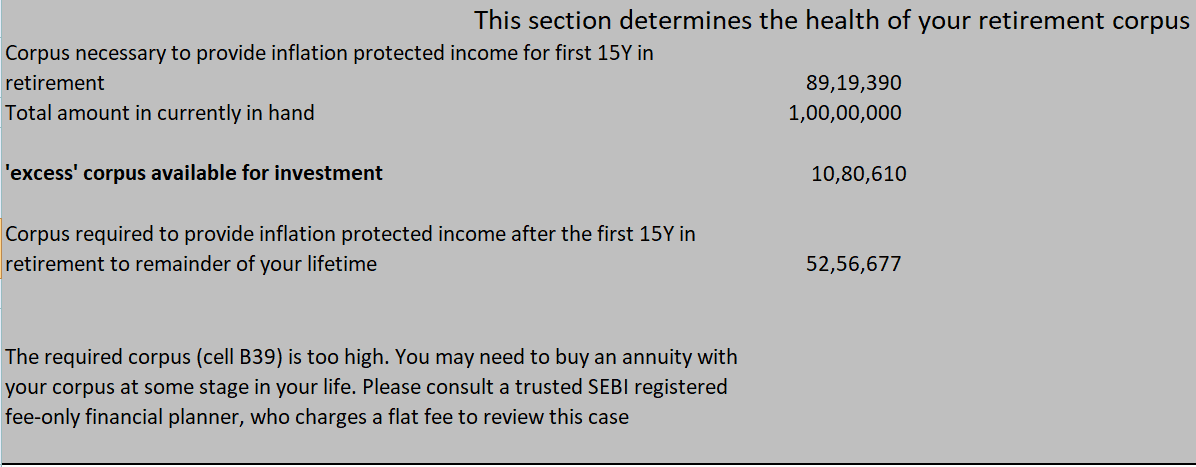
Now, about 89L is necessary to generate inflation protected income for first 15Y in retirement. However, 52L is necessary to do the same for the remaining 11 years. Only, 10.8L is in hand.
This again amounts to an excessive risk. The person will have to buy an annuity sooner or later. This is a tricky case requiring a SEBI registered Human advisor. I am still trying to see if the advice here can be automated.
Monthly expenses: Rs. 30,000 + another Rs. 30,000 for annual expenses
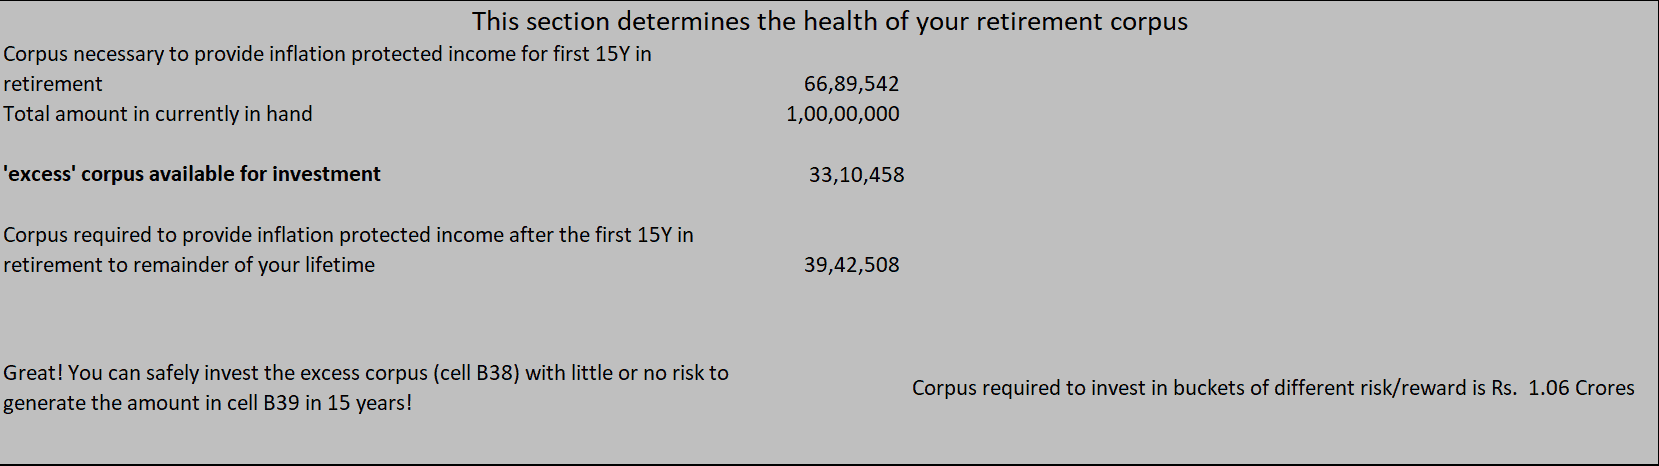
Now, 66.9 L is needed for 15Y inflation-protected income. Another 39.4L for the rest of the person’s life. So 1.06 Crore in all against 1 Crore in hand. That is pretty good. The person can adopt a bucket strategy with zero or minimal equity exposure.
Now let us look at the case for younger people. Obviously, the result will change depending on expenses as shown above, but I cannot show all possibilities here.
A 55-year old with Rs. 1 crore
Monthly expenses: Rs. 30,000 + another Rs. 30,000 for annual expenses
Rs. 66L is necessary for the first 15Y and another Rs. 56L for the rest. So the corpus is about 23L short. This is “cat on the wall” situation. Take risk and it may become too much risk. Taking no risk is also a risk! If the person chooses not to buy an annuity, then careful portfolio management is essential.
A 50-year old with Rs. 1 crore
Monthly expenses: Rs. 30,000 + another Rs. 30,000 for annual expenses
Now, 1.35 Crores is necessary. About 67 L for the first 15Y and 69 L for the remainder of the person’s life.
Again, it is on the fence.
A 45-year old with Rs. 1 crore
Monthly expenses: Rs. 20,000 + another Rs. 20,000 for annual expenses
At last, only 99L is required to be invested in the four buckets as shown below! The person can comfortably retire (as per current expenses!)

A 40-year old with Rs. 1 crore
Monthly expenses: Rs. 30,000 + another Rs. 30,000 for annual expenses (say health insurance).
An additional 66L is required. The person cannot retire.
A 35-year old with Rs. 1 crore
Monthly expenses: Rs. 20,000 + another Rs. 20,000 for annual expenses (say health insurance)
Now there is a shortfall of 18L. Too risky to retire that young. Many youngsters in early retirement forums believe that it is possible, but if they see a bit more of life, they will agree that it is simply too risky. A single unexpected recurring expense can screw up the whole plan.
So the answer to “Can I Retire With Rs. One Crore Today?” depends on several factors. It is certainly not impossible as the above example show. As mentioned this is a sneak preview of the post-retirement suggestion provided by the robo template. It will also cough up pre-retirement suggestions.
A 40-Year-old with 1 Crore wanting to retire by 55
Monthly expenses: Rs. 40,000 + another Rs. 40,000 for annual expenses (say health insurance)

Get the freefincal robo advisory template