A reader says, “The next trance of Sovereign Gold Bonds is now available for purchase. Can I buy these for portfolio diversification?”
The short answer is: Don’t! In principle, gold can be used for diversification (that it is not of much use is another matter, see below), but the product should be liquid. We should be able to freely sell it at a fair market price to rebalance the portfolio to reset or vary asset allocation (assuming we have one in mind, most investors don’t bother).
Sovereign Gold Bonds are not suited for this. Most investors only want to buy it because of its tax-free nature when held to maturity. Such investors will never sell mid-way to rebalance the portfolio, defeating the essence of diversification. Of course, no limits exist to how much one can di-worsify a portfolio.
Regarding buying and holding an SGB to “maturity” to earn some return from gold, the spread in possible returns is so wide that it is much akin to gambling. This can be seen from below from the 8-year rolling returns of gold USD and gold INR price per troy ounce. Read more: Do you wish to buy Sovereign Gold Bonds for the wrong reasons?!
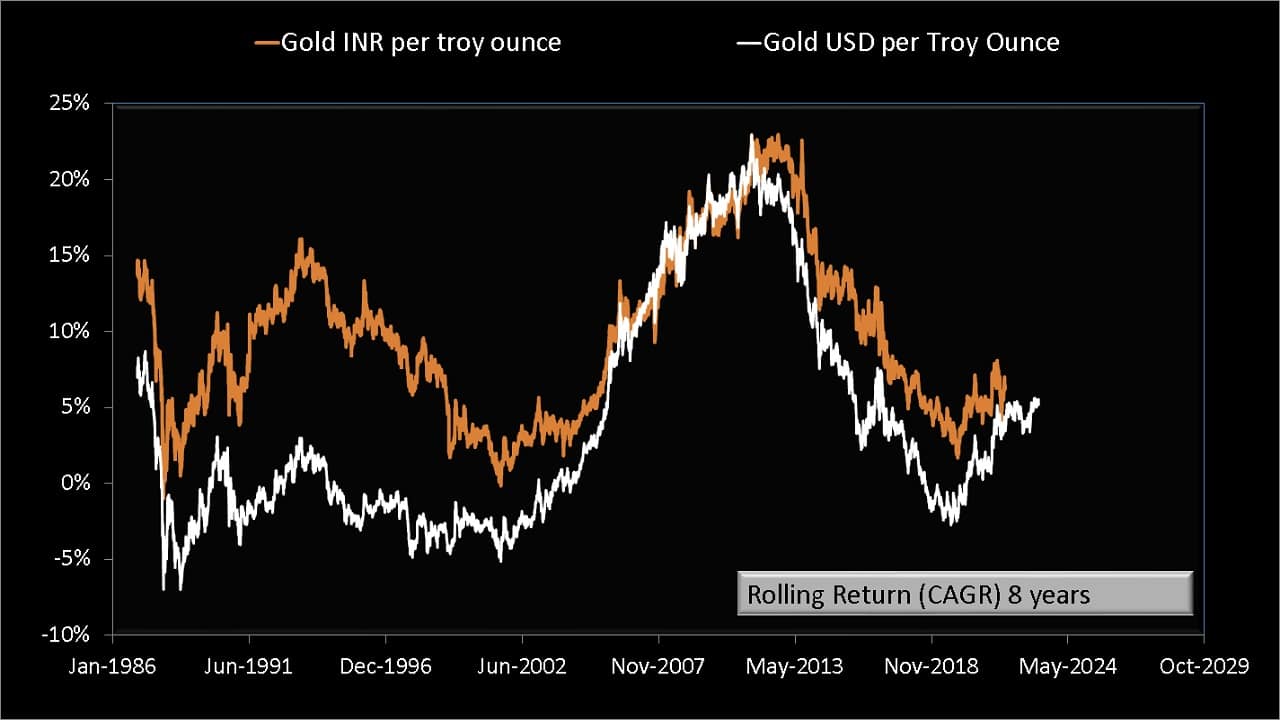
Now, gold funds or gold ETFs can be used for diversification. But is it worth the effort? We have repeatedly shown that gold is not an inflation hedge (at least not an efficient one), and adding a small amount of gold (10% – 20%) will not make a big difference to an investment portfolio. Gold is an unnecessary passenger in a portfolio. See: Can I add 10-20% gold to my 15-year investment portfolio? Also, Can I use Sovereign Gold Bonds in my retirement portfolio?
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
If you must have gold in your portfolio, buy a multi-asset fund and make it a key portfolio holding and you will get that gold exposure without the tax and rebalancing hassle. For recommendations, see: Handpicked List of Mutual Funds (PlumbLine)
So does this mean one should not invest in sovereign gold bonds?
Use these only if you aim to accumulate gold for a future need, say for a marriage. Sovereign gold bonds offer a tax-free, risk-free way to accumulate gold if your future gold purchase is over eight years away*. You also get 2.5% interest (taxable as per slab) on the initial gold value as a “thank you for trying to reduce gold imports” gift from the govt.
* If it is too far away, like 15-20 years, then an equity + debt mix will get the job done. Remember, gold is quite volatile and may or may not be rewarding as equity over the long term. Gold vs Equity (Sensex) 40 year return and risk comparison
You can buy these bonds in the secondary market via a demat account from desperate investors looking for cash and willing to take a loss. This approach is risk-free because the bond tracks the price of 24-carat gold and at any given time and after eight years one could buy 22-carat jewellery