Last Updated on October 1, 2020 at 5:22 pm
ICIC Amc launched a new feature called ‘moneyback’ in its ICICI Balanced Advantage fund. Here is why retirees or young investors should not choose the moneyback feature of ICICI Balanced Advantage fund.
The moneyback feature is a terribly misleading term for a Systematic Withdrawal Plan or a SWP (check out a Step-up SWP Calculator).
A SWP is the opposite of a SIP. From a corpus, a constant amount is withdrawn like a pension. It is extremely disappointing to find financial advisors suggest retirees to set up a SWP from equity-oriented funds like the ICICI Balanced Advantage fund. In such a case, when the NAV falls, the constant withdrawals will imply redemption of more units. SWP from a debt fund, while part of the corpus grows in equity funds is a much better idea (depending on the size of the corpus).
The addendum to the scheme states
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Moneyback is only a feature for regular withdrawal from the scheme and shall not be construed as an assurance or guarantee of returns) has been introduced under the Scheme with effect from September 10, 2015
This feature will allow investors to redeem a fixed sum of money periodically at the prevailing Net Asset Value (NAV) depending on the option chosen by the investor.
To capture the attention of retirees, it is being mis-sold as regular, guaranteed moneyback from the scheme.
The moneyback payouts are not dividends. They are automated redemptions.
Regular payouts will erode the capital invested in the scheme!
Asan Ideas for Wealth (FB group) can see the thread started by Nikhil Vora (thanks to whom I write this post):
https://goo.gl/yOWa5f
It took me a while to realize that this is just a SWP in disguise.
The ICICI Balanced Advantage fund without this moneyback features is a solid performer and can be considered as part of a minimalist portfolio by both young earners and retirees. However, retirees should be careful not to invest too much in this scheme. Although the fund is touted as a ‘less volatile’ option due to the use of equity derivates, it can result is large negative returns and can permanently (for a retiree) erode your purchasing power and financial independence in retirement. For instance, have a look at past annual returns (data from value research)
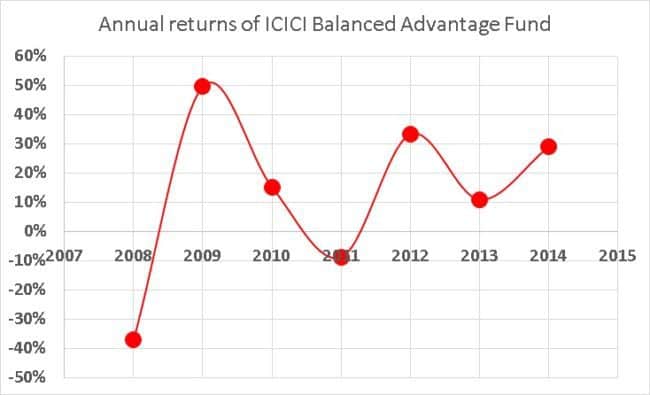
Do not, repeat, do not invest in equities after retirement blindly following suggestions of an advisor. Please do you own research, understand how volatile equity can be and only then proceed. If you are interested, you can consider reading:
Investment options for senior citizens
When should senior citizens purchase an annuity?