Last Updated on December 29, 2021 at 5:46 pm
In a circular dated Oct 5th2020, SEBI once again changed the norms for “Product Labeling in Mutual Fund schemes” – the third such change in the last seven years. In what can only be seen as bizarre, SEBI ruled that a change in the “risk-o-meter” dial for a fund need not be considered as a change in fundamental attribute! There is no limit on the number of such changes permitted!
In March 2013, SEBI adopted a traffic signal like system for labelling MF risk: Blue – principal at low risk; Yellow – principal at medium risk; Brown – principal at high risk. They did not want to use green, amber and red and scare investors away from red!
From three notches on the dial, the risk-o-meter had five notches from April 2015: i: Low – principal at low risk; ii. Moderately Low – principal at moderately low risk; iii. Moderate – principal at moderate risk; iv. Moderately High — principal at moderately high risk; v. High – principal at high risk/
Now five notches have become six! “Moderately Low” now becomes “Low to Moderate Risk” and a new notch “Very High Risk” added. The first troubling aspect of this new circular is the conspicuous absence of the most important phrase “principal at risk
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
While the earlier circular bothered to at least inform the investor what was at risk, the new circular does not clarify this! Perhaps that is just as well because regulatory risk appears to be bigger than mutual fund risk.
From arbitrary risk levels on the dial, SEBI has gone all out on “detailed guidelines for evaluation of risk levels of a scheme along with few examples”. Before we fall into that Rabbit hole, consider these allowances given to mutual funds.
- The risk-o-meter reading will be evaluated each month and disclosed
- the number of times the reading changes each year will be disclosed
- “Change in risk-o-meter will not be considered as a Fundamental Attribute
Change”. This means the funds risk and therefore return profile can change at will and the investor will not be given a chance to exit the fund without load.
What is the point in providing elaborate formulae and examples if the fund house is free to vary the risk profile of the scheme? At least the 2015 circular had a vague “Mutual funds may ‘product label’ their schemes on the basis of the best practice
guidelines issued by the Association of Mutual Funds in India (AMFI) in this regard”.
If the risk-o-meter is expected to be so variable then it is useless, to begin with. When we invest in mutual funds, we need to pin the fund in the risk vs return map. It is fine if the fund is placed in a broad space such as this schematic. Movement of the red dot within the blue zone should not be a problem as long as the category classification is properly done – it is not: See: SEBI Multicap MF Rule: Are other fund categories “true to label”
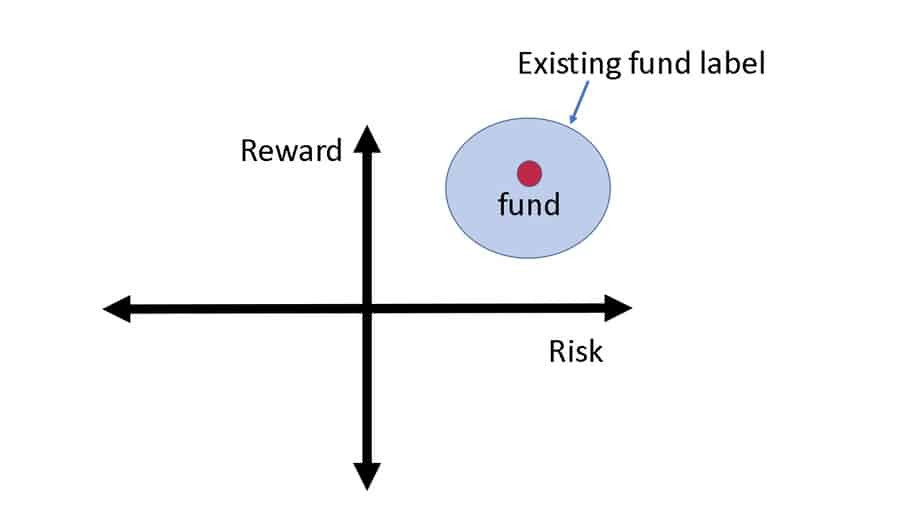
When I read the new rules (what little I can make out of it), it appears as if the “binning zone” has shrunk and even small changes in the fund’s risk profile is being computed and communicated to investors (dotted line).
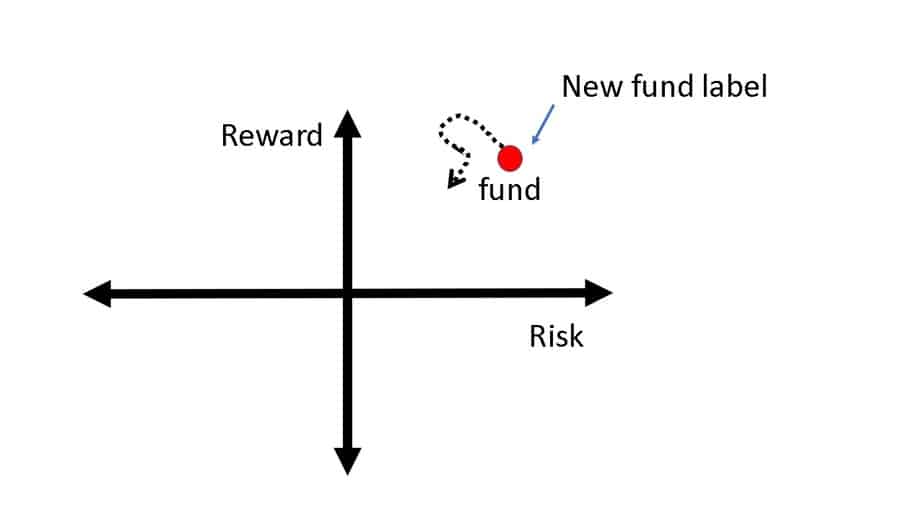
Surely, this is unnecessary. When I buy a debt mutual fund, I expect it to invest in only one type of bonds predominantly or at least in fixed proportions of different types. For example, a fund can invest bet 40-0% in gilts, 50-70% in AAA bonds, 10-20% in AA bonds and 0-10% in A bonds. All I want is clarity of these levels. I do not need to be informed of a change in risk-o-meter reading when the fund’s asset allocation swings by a huge amount. This is just going to make the retail investor worried. This is the reason, I think, the phrase ‘principal at risk’ is missing from the circular.
The new risk-o-meter is only going to confuse mutual funds investor’s and the only way to avoid confusion is to ignore it altogether. SEBI should have focussed on tightening the norms of fund categorization instead of adding more graduations to the risk dial with elaborate annexures.
For example, most investors have no idea what a Macaulay duration is. Instead of using such an obscure term for classifying interest rate risk, the average portfolio maturity or the average portfolio maturity per risk category would have been a better and easier-to-understand choice.
Already AMCs send enough addendums and circulars on their own. Thanks to SEBI, they will now send more of these and cause investors to worry. Mutual funds are subject to regulatory risks, ignorance risks and market risks in that order. Save yourself by doing your own research and expecting everything to change for the worse.
Join our exclusive Facebook Groups!
- 500+ members are now part of our new course, How to get people to pay for your skills! (watch 1st lecture for free). This was launched Sep 28th 2020.
- 1822 members have signed for Goal-based portfolio management(watch 1st lecture for free). This was launched in Jan 2020.