Last Updated on December 29, 2021 at 5:43 pm
This is a question posed by 35-year-old Prakash: “I would like to get Rs. one lakh a month pension when I retire. How should I invest to achieve this?” A pension after retirement is a necessary component of a post-retirement investment portfolio. However, it is not sufficient. A discussion.
Nothing beats the comfort and security of a guaranteed pension payout each month. However, as discussed earlier – Why have we not seen a retirement crisis in India? – retirees from our parent’s generation are managing their lives by reducing their needs and depending on their children. This happens so gradually within the fungibility of common family income that it is hard to spot.
The best aspect of Prakash’s retirement plan is time. As of now, he has about twenty years of gainful employment left in him. Rs. one lakh a month pension may seem like a huge amount to many but is an emotional measure based on current income. Just one assumes one crore term insurance is ‘large enough’ without detailed calculation.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Suppose Praksh’s essential expenses today cost about Rs. 30,000. Even if use a timid 6% a year inflation, at age 55 those expenses would have grown to Rs. 96,000. ‘Those’ is highlighted because this calculation has to be repeated each year with current essential expenses. Essential here refers to expenses that are likely to last the lifetime of the person.
Now let us assume Prakash has enough corpus to generate Rs. one lakh a month pension. He buys a pension annuity from a life insurer and also buys some govt bonds that pay out interest every six months. In effect, his total annual income from these two sources is about Rs. 14 lakh.
Assuming he pays 20% tax on this (down 10% from the current rate as this is 20 years from now), this would approximately result in 12 lakhs a year or one lakh a month on average. This is how the pension would fare against a projection of his expenses from age 55 to age 85 (approximate life expectancy).
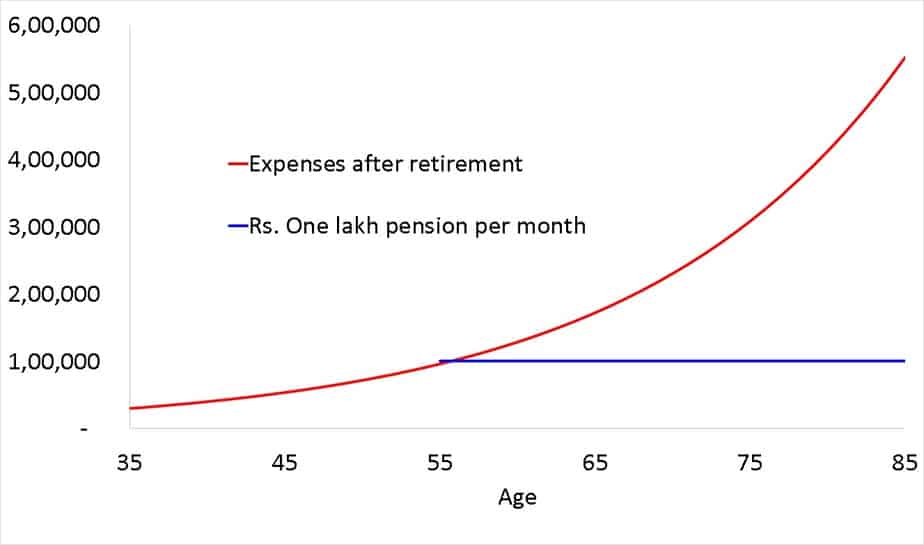
The problem of settling for a constant seemingly “high pension” of Rs. one lakh a month should be immediately clear from the above illustration which at the moment does not include any additional expenses from age 35 to age 85.
That said as shown before, a constant pension source in retirement is always welcome as it aids the emotional well-being of the retiree. See: Creating the “ideal” retirement plan with income flooring!
What Prakash should appreciate before it becomes too late is, this constant pension should only be one component of his retirement basket (a term used by PV Subramanyam). After twenty years annuity and bond rates are likely to significantly lower. So assuming a rate of 5.5%, an pre-tax income of Rs. 14 lakhs a year requires, hold on to your chair, 2.5 crores.
So even to get a pension, which is grossly inadequate, a person needs to be a “multi-crorepati”. Yet another reason why we should stop fixating in terms of lakhs and crores and think in terms of future expenses.
In order to compensate for the gap between expenses and pension, Prakas will require another 2 crores as of now assuming this money grows at a post-tax income of 7% after retirement. See this video for the income flooring illustration.
Notice the number of assumptions being made in every sentence. The only way to keep these as close to reality as possible is to re-do this calculation with new inputs like current expenses, current rates etc every year.
Now assuming Prakash achieves a portfolio return of 9-10% after-tax over the next 20 years, he would need to invest Rs. 35,000 to Rs. 40,000 a month increasing 6% a year to get close to the 4.5 Crore mark!! Recognise his expenses are Rs. 30,000 a month!
Even with a portfolio of 50-60% equity (to achieve the 9-10% return), a sum more than expenses has to be allocated for financial independence after retirement. Imagine how much a person who wants the safety of fixed income should invest!
Key Takeaways:
- One lakh is just a number. It means nothing if we do not factor in inflation.
- Pension is just one component of a retirement plan, but an important one.
- Inflation after retirement is a crucial factor.
- We need to take on investment risk when we are young and not look for the safety of fixed income to combat inflation.
- Even if we take on investment risk, we need to invest at least as much as we spend for retirement.
- Think thrice before adding any new expense because it will lower your investment.
- Avoid debt as much as possible or at least postpone essential debt like a home loan until basic financial goal planning is in place and at least 30% of salary is allocated to investing even while servicing the loan.
- This of additional income sources today! See: Passive income is a crucial part of your retirement plan: How to get started