Last Updated on October 1, 2023 at 9:23 pm
ICICI Prudential Insurance has introduced a Single-Premium Annuity Plan called ICICI Pru Guaranteed Pension Plan. In this review, let us analyse its features, merits and demerits and evaluate if the plan has any value to offer. What Is It? ICICI Pru Guaranteed Pension Plan is a “Non-linked Non-participating Individual Annuity Plan”
About the author: Ragesh G R is a Software Architect with 13 years of experience. His interests are computers, personal finance, cars, technology, maths and music. He helps his friends and family with their personal finance. Also, he actively guides physically challenged people all over India with buying and registering cars and procuring driving license via his blog at Ragesh in Full Throttle! Check out his other articles: (1) Financial Considerations and optimisations while buying a car; (2) What you need to know before buying term Insurance; (3) Used Car vs New Car: Which is a better buy?
What does it offer? A Single-Premium Annuity Pension Plan. You pay a Single Premium as lump-sum to the insurer. They provide you with a regular annuity for life. It has the following options to choose from:
Immediate Annuity Options
In this option, you start receiving the annuity immediately after you pay the premium. This has further sub-categories.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
- Single Life: Annuity is paid till the life of the insured. It has the following sub-options:
- Without Return of Purchase price: Upon your death, the policy terminates.
- With Return of Purchase price: Upon your death, the purchase price is returned to the nominee and policy is terminated.
- Critical Illness and Permanent disability rider. You have the option of getting back the purchase price upon the occurrence of any of the 7 CI’s or PD before the age of 80.
- Age-based riders. You have the option of getting back:
- The full purchase at 80, or,
- Half the purchase price at 80, or,
- 5% of the purchase price every year for 20 years from age 76 to 95
- Joint Life: Annuity is paid as long as either of the Annuitants (typically you and your spouse) are alive. This option also has the choice of choosing to return the purchase price to the nominee upon the death of both annuitants.
Deferred Annuity Options
In this option, you can choose to start receiving a pension at a later stage, 1 to 10 years after purchasing the annuity. But you can lock-in the current interest rates.
This has the following sub-categories:
- Single Life
- Joint Life
Both the above options offer the following death benefits
Death Benefit during the deferment period which is higher of:
- Purchase Price + Accrued Guaranteed Additions
- 105% of Purchase Price
Death Benefit post the deferment period which is higher of:
- Purchase Price + Accrued Guaranteed Additions – Total annuity paid out till date of intimation of death
- Purchase Price
Here too, you have the Critical Illness and Permanent Disability riders.
How does it work? We will first look at what it looks like, at face value and then we will delve deep into what it actually is in its crux. Let us understand the workings of this policy with a few examples.
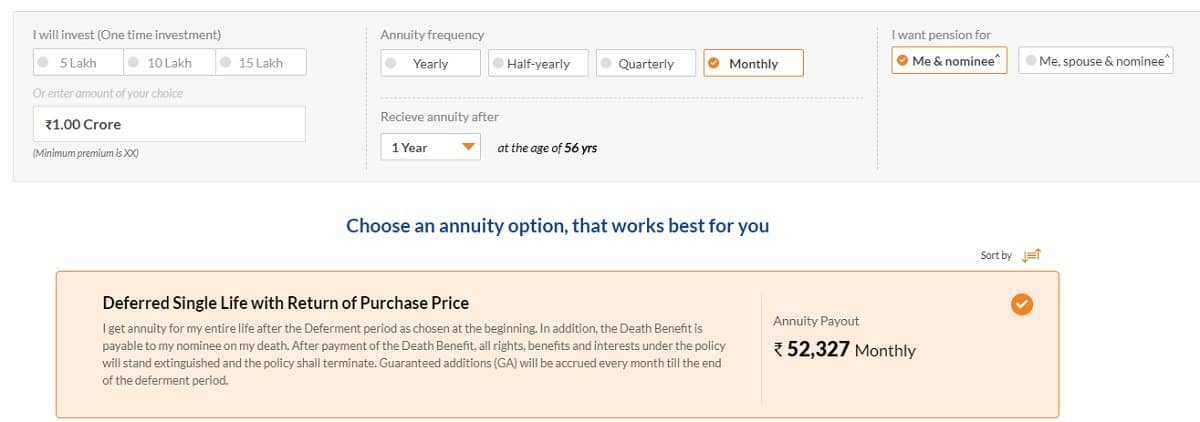
Example: A 55-year-old male purchases this policy.
Policy Type: Deferred Single Life with Return of Purchase Price
Deferment Period: 1 year
Annuity Frequency: Monthly
One-time Premium : 1,00,00,000 (1 Crore)
Annuity Payout per month: Rs. 52,327
Total Annuity Paid out per year: Rs. 6,27,924
You will receive this annuity monthly as long as you are alive. When you pass away, your nominee will get the purchase price back. The snapshot is given below.
Analysis: At the outset, it looks like you will receive a payout of 6,27,924 on a 1 Crore so that comes to around 6.3% return which is really good. However, you need to apply 1.8% GST to the premium so your returns will drop to 6.16%. This is still really good in this day and age. You need to pay tax on the annuity, the income is taxable as per your slab. So you will have to pay Rs 28,085 tax on this. So your post-tax income is 599839 ~ 6 Lacs.
So our post-tax returns will become 5.89% this is about 0.4-0.5% higher for the corresponding option and age group that the return given by LIC’s Jeevan Akshay – VII (Plan No. 857, UIN: 512N337V01)
This is a respectable return for the current interest rate situation for a deferment period of one year where the money value of time can be ignored. If the deferment period is longer, then the delay between premium payment and annuity payment will decrease returns significantly. Do not take the “lock-in pension at current rates” sales pitch at face value. See further examples: Why Time is Money and How Life Insurance Plans Exploit it!
For example, although the pension itself is at an effective post-tax rate of 5.89% of the premium paid, if the payout is for 30Y with one-year deferment, the effective IRR at the end of the 30Y period is 3.84% (this IRR has no practical relevance to the retiree but is used just to illustrate the money value of time). Increase the deferment to five years, the IRR drops to 2.98%.
Another way of saying this is, by paying the insurer a lump sum to get a future pension at current rates, we are sacrificing the opportunity to get better returns in the intervening period. Therefore it is important to ensure the deferment period is as low as possible, preferably zero (immediate annuity).
What potential buyers need to know
Although the interest payout is reasonable, the buyer will have to keep these additional factors in mind:
- This provides static annuity with no option to increase the annuity as time passes. So in real terms, inflation will take away the value of the money, and each year, your real income keeps on reducing. So you will need some other parallel investment to fortify the income to take care of inflation. You can use this annuity plan only for income flooring. See: Creating the “ideal” retirement plan with income flooring!
- Annuity income is completely taxed as per slab.
- Alternative pension sources (as one component of a retirement portfolio):
- GOI bonds obtained via NSEgobid is an option to get 30,40-year interest payout as a pension, but this depends on individual on yields, the bid price and allotted price.
- PM Vaya Vandana Yojana which offers 7.66% pre-tax interest for ten years with a maximum investment amount of Rs. 15 lakh.
- Senior Citizens Savings Scheme (30 lakh max investment for a couple) with max eight-year tenure; the rate can be locked in upon purchase but depend on the time of purchase (decided each quarter)
Also, see: Building the ideal retirement portfolio that goes beyond money