Last Updated on December 19, 2021 at 7:18 pm
Benjamin Franklin wrote in 1748 that Time is Money in a note titled “Advice to a Young Tradesman”. This can be used in multiple ways and in this post, I use it to explain an important idea known as the Time Value of Money. Shall try to follow it up with other examples in future posts.
Journalist Yogita Khatri did an article for ET Wealth as to why traditional life insurance plans should be avoided (link below) that includes my inputs. I expand on some of the numbers provided to her.
Scenario 1: Guaranteed, but gradual payouts
Consider a typical “guaranteed income plan” offered by many insurers. This promises to pay a “regular income” for Y no of years after the premium is paid for X no of years. This sounds so great on paper. Let us investigate more with an example.
Say you need to pay a premium of Rs. 100 for 10 years. Then over the next 10 years, the insurer will pay you, double the total amount of total premiums paid. That is, you paid Rs. 100 x 10 = 1000 over ten years. It will pay you 2 x 1000 = 2000 over the next ten. Does it sound like a good deal?
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
We ned to find out the internal rate of return (IRR or XIRR) to find out how good this is. IRR represents the annualised rate of return. Read more: CAGR vs. IRR: Understanding investment growth measures.
The premium paid is written as a -100 to represent cash leaving your hand. The payout is +100 to represent a receipt. So you can see the cash flow for 20 years below.

Notice that the payout is only Rs. 100 for nine years (from years 11 to 19). In year 20, the payout is Rs. 100 + Rs. 1000 = Rs. 1100. Making the total payout received twice the total premiums paid. Notice the IRR. It is a pathetic 5.84%. Many people fall into the lure of guaranteed income without understanding the idea of IRR and how to calculate it.
The formula one can use in Excel or Google Spreadsheet is indicated at the bottom.
Scenario 2: Guaranteed, but immediate payout
What if the insurer paid you twice the amount of premiums paid in the 11th year itself?
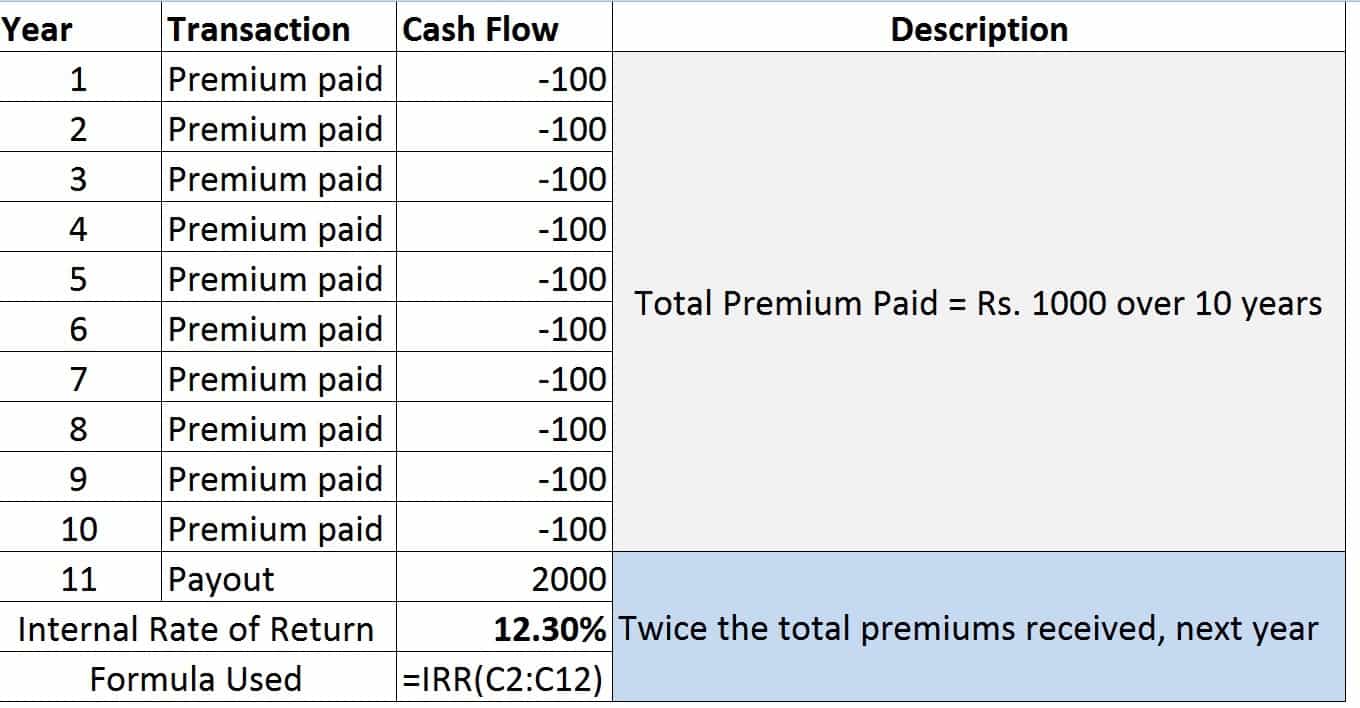
Well, if they did that, they will have to close down! Notice the huge difference in IRR. More than twice. This is the time value of money at work. When the payments are not immediate, you lose immensely and they gain immensely. And we are not even considering the fact that the insurer can invest the premiums collected and earn a return on it over the many years they hold on to it. Where do you think the bonuses come from?!!
If you receive the payout immediately, not only is the return high, you can use it any way you want. If they delay payouts, they can use it any way they want. Time is money!! This idea is also known as opportunity cost.
In context, it also means that liquidity matters! If the money is locked-in, we lose more than we know. In a sense, this proverb sums it up:
Link to Yogita Khatri’s ET Wealth Article: https://goo.gl/q7cF7p
Link to Benjamin Franklin’s essay: Advice to a Young Tradesman