Last Updated on March 3, 2024 at 9:02 am
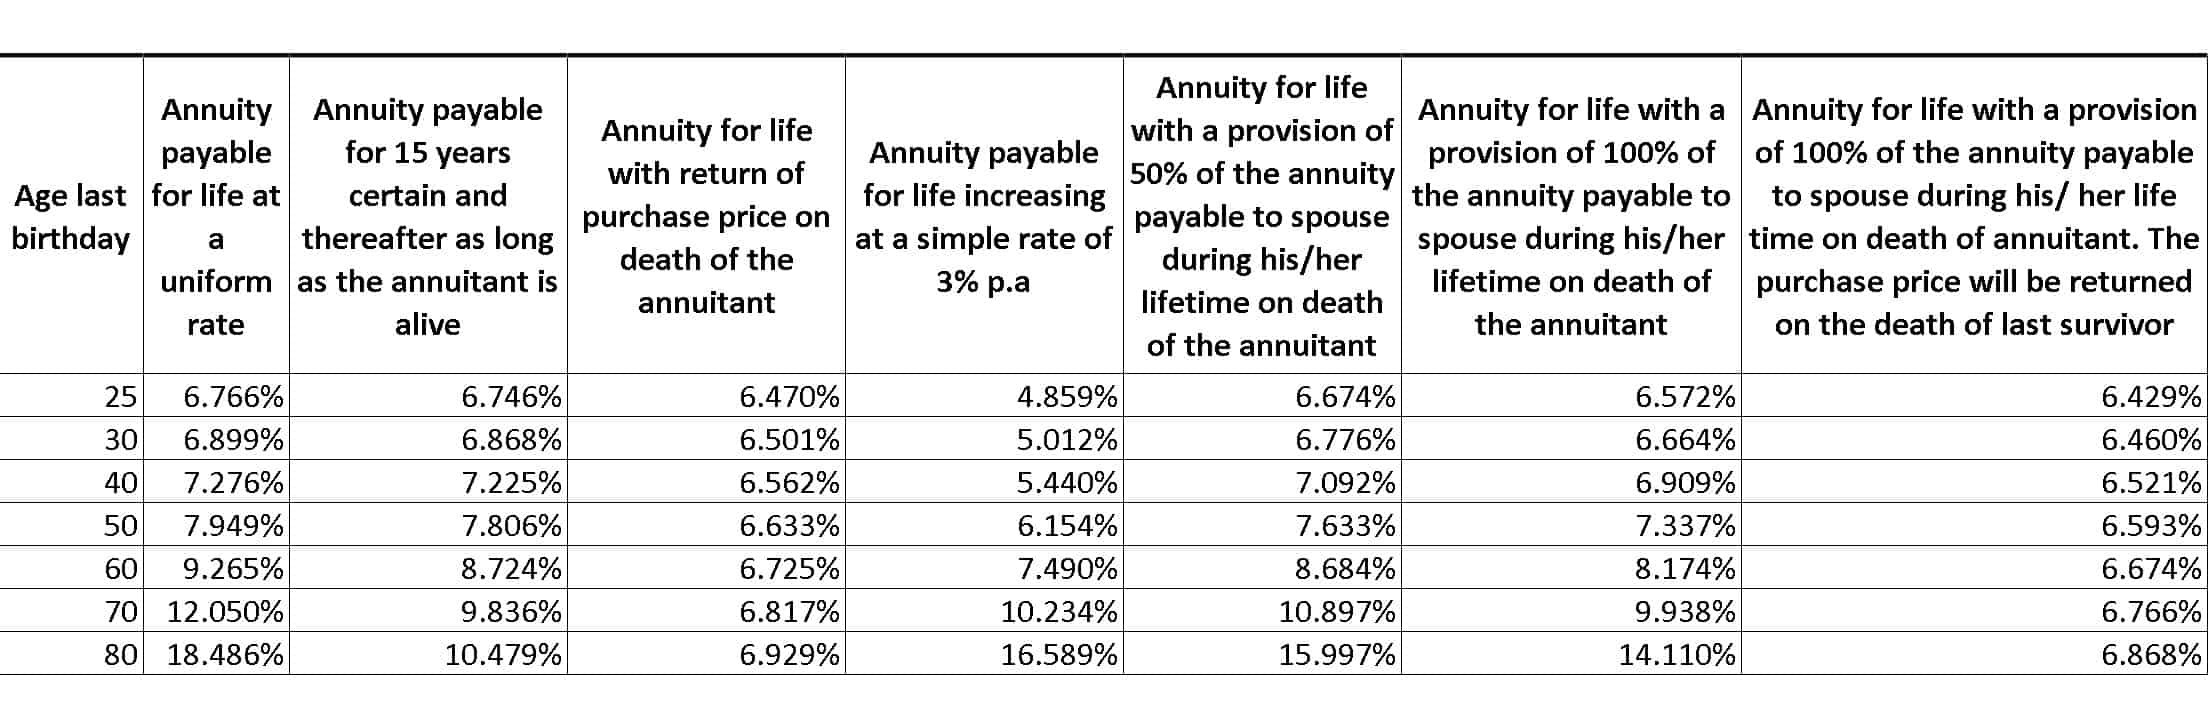
LIC’s Jeevan Akshay – VII (UIN – 512N337V05) is an Immediate Annuity plan. You can purchase a pension (annuity) by paying a lump sum. The annuity rates applicable from Feb 2024 are listed in this article. According to LIC’s online purchase portal, the rates are the same as last year.
Additional resources
- Use this annuity ladder calculator to plan for retirement with multiple pension streams.
- How LIC annuity rates have changed over the last 20 years
- I need a pension: Should I buy an annuity or a govt bond?
- How Annuity Plans Work
- When should senior citizens purchase an annuity?
- Higher annuity rates of LIC Jeevan Akshay applicable from Feb 2023
Annuity Options
A. Annuity payable for life at a uniform rate.
B. Annuity payable for 5 years certain and after that as long as the annuitant is alive*.
C. Annuity payable for 10 years certain and after that as long as the annuitant is alive*.
D. Annuity payable for 15 years certain and after that as long as the annuitant is alive*.
E. Annuity payable for 20 years certain and after that as long as the annuitant is alive*.
F. Annuity for life with return of purchase price on death of the annuitant.
G. Annuity payable for life increasing at a simple rate of 3% p.a.
H. Annuity for life with a provision of 50% of the annuity payable to spouse during his/her lifetime on death of the annuitant.
I. Annuity for life with a provision of 100% of the annuity payable to spouse during his/her lifetime on death of the annuitant.
J. Annuity for life with a provision of 100% of the annuity payable to spouse during his/ her lifetime on annuitant’s death. The purchase price will be returned on the death of the last survivor.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
* In these options, if the annuitant dies within the stated period, the pension will be paid to the nominee until the end of the guaranteed period.
The option that looks most beneficial to us is least beneficial to the insurer; therefore, the annuity rate will be lower. For example, the insurer keeps the purchase price on the annuitant’s death in option A. In option F, the insurer must return the purchase price to the nominee.
So they would offer a terrible interest rate (annuity rate) on option F and the best rate for option A! For all options other than A, the rate will drop quickly and fast!
In option G, the income increases each year by 3%. If the annuitant is old (55 or above), this has a higher rate than option F. Older people are likely to die sooner, and the insurer with option F must repay sooner!
Annuity rates dramatically increase with age because older people need not be paid for long! This is the underlying principle behind laddering annuities (more on this in the coming days). We shall also study the time value of money for these options. To learn more
Annuity rate comparison
Let us look at how the rates have increased for option A: Annuity payable for life at a uniform rate.
| Age | Feb 28th 2023 to Feb 2th 2023 | From Feb 28th 2023 (also applicable from Feb 2024) |
| 30 | 6.205% | 6.899% |
| 40 | 6.535% | 7.276% |
| 50 | 7.155% | 7.949% |
| 60 | 8.325% | 9.265% |
| 70 | 10.690% | 12.050% |
| 80 | 17.230% | 18.486% |
Annuity Rates of LIC Jeevan Akshay VII from Feb 7th 2024
Plan no: UIN – 512N337V05
There are incentives for buying online and for a higher purchase price, which would increase the annuity rate. These are not considered in this illustration.
Younger retirees might get a better deal if they buy govt bonds (although this is not guaranteed income for life and could be recalled by the govt). See an example: How I used RBI Retail Direct to buy government bonds and create an income source. Also see:
- RBI Retail Direct: A look inside: how to register and what you can buy/sell
- RBI Retail Direct for govt bonds: Who should use it and who should not