Last Updated on September 15, 2025 at 11:44 am
A few years AMCs hit upon a brainwave. Since dividends from equity-oriented funds were tax-free (until March 31st, 2018), they came up with a monthly dividend plan in “balanced funds” (old name). This option was then (mis-)sold as a way to get monthly income to senior citizens. First, a dividend distribution tax of 10% (11.648% effective) and then from April 1st, 2020, all dividends from shares and all mutual funds will be taxed as per slab. While this will hopefully affect sales of such plans, what should existing investors in monthly dividend mutual funds do? A discussion.
To understand the impact of mutual fund dividends being taxed as per slab for debt and equity funds, please consult: Mutual Fund Dividends: When and how to use them from April 2020.
This article stems from a comment received from Mr. C B Rameshkumaar. “Since I have deposited a lot of money in a Balanced fund monthly dividend, please advise me what to do after April 2020. I am absolutely confused at the present juncture. My broker informs me that since STT is removed, I might get more money as dividends from April 2020.Kindly advice. I am a 63-year-old citizen with no pension.”
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
First of all, this broker does not seem to know the difference between STT (securities transaction tax, which applies to the sale of equity mutual fund units) and DTT (dividend distribution tax, which applies to mutual fund dividends).
It is DDT that has been removed from April 1st, 2020. Yes, this would mean more dividends as the tax deduction done at source is done away with. However, the unitholder will have to pay tax as per slab on the dividend.
Those in the 0% or 5% tax slabs, this would be mean more “income” and would hurt those in the 20% or 30%-plus slabs. Since Mr. Rameshkumaar’s net worth and other investment details are unknown, all one can say is, he – and others in the same boat – should reevaluate the need for monthly income from equity-oriented funds in their portfolio.
Does it make sense to get monthly dividends from a fund which can hold a significant amount of stocks after retirement? A huge crash can wipe out a significant portion of the corpus. This is especially dangerous in the absence of a pension.
Risk management takes precedence over taxation. Dividends taxed per slab will reduce the “income” of those in 20% and above tax slabs. Those who wish to exit may do either in one-shot or gradually depending on their capital gains liability.
Please observe the NAV movement since the inception of the monthly dividend options in ICICI Balanced Advantage Fund. Since most of the gains have already been paid out as dividends, those who wish to exit now may not have to pay much capital gains tax.
For unit older than one year, there is a one-lakh tax-free limit. So this will further reduce the effective long-term capital gains. Therefore a switch to either the growth option or any other investment will not hurt as much. Investor switch either now or in the new financial year (2020-21). When you switch, switch to direct plans. Ignore what your broker or distributor has to say.
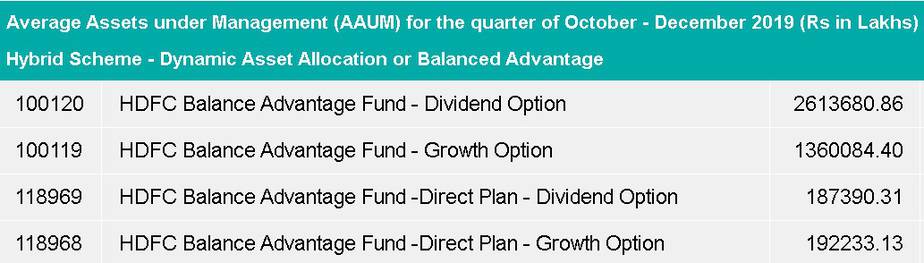
Now, let us look at the Average Assets under Management (AAUM) for the quarter of October – December 2019 (Rs in Lakhs) (Source AMFI)
| ICICI Prudential Balanced Advantage Fund – Direct Plan – Dividend | 14957.24 |
| ICICI Prudential Balanced Advantage Fund – Direct Plan – Growth | 259819.73 |
| ICICI Prudential Balanced Advantage Fund – Direct Plan – Monthly Dividend | 11945.27 |
| ICICI Prudential Balanced Advantage Fund – Direct Plan – Quarterly Dividend | 21.88 |
| ICICI Prudential Balanced Advantage Fund – Dividend | 160102.97 |
| ICICI Prudential Balanced Advantage Fund – Growth | 2024191.29 |
| ICICI Prudential Balanced Advantage Fund – Monthly Dividend | 339844.07 |
| ICICI Prudential Balanced Advantage Fund – Quarterly Dividend | 1279.29 |
| HDFC Balance Advantage Fund – Dividend Option | 2613680.86 |
| HDFC Balanced Advantage Fund – Growth Option | 1360084.4 |
| HDFC Balanced Advantage Fund -Direct Plan – Dividend Option | 187390.31 |
| HDFC Balanced Advantage Fund -Direct Plan – Growth Option | 192233.13 |
About 12.08% of the total AUM of ICICI Bal Advantage Fund is from regular plan monthly dividend. That should tell you the extent of pushing distributors have done.
About 60% of the total AUM of HDFC Balanced Advantage Fund is from the regular plan, dividend option. This is the normal dividend option, not monthy. Just in case those numbers are hard to believe this is the screenshot from AMFI. The numbers to the left of the fund name are the AMFI scheme code.
Yes, it is time to switch out from monthly dividend options for most investors. Not just because of the change in dividend taxation, but because they have been misinformed and misunderstood the associated risks.