Last Updated on August 4, 2025 at 5:27 pm
The Pension Fund Regulatory and Development Authority (PFRDA) has announced guidelines regarding partial withdrawal from the National Pension System (NPS).
(1) A subscriber whose NPS account is at least 10 years old will be eligible for withdrawing 25% of his/her contributions alone. Employer contributions (if any) cannot be withdrawn. Notice the similarity with the recently announced EPF withdrawal rules. Update This has now been reduced to 3 years. See: NPS 2019 withdrawal rules
Although the circular says, 25% of accumulations due to self-contributions, the application form appended to the circular (link below), make it clear that it is Max 25% of own contributions without accrued income earned thereon.
Update budget 2017: this 25% is no tax free but is subject to overall 40% tax limit.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Tax Status. There is no explicit mention of this. My understanding is, since 40% withdrawal from NPS corpus is tax-free, partial withdrawals should also count under this limit. That is, the overall tax-free limit is 40% of the total amount withdrawn over time.
The amount withdrawn should also count under the total amount that can be withdrawn. Clarity is required with respect to this after Budget 2016. We only know that 40% of total corpus is tax-free if withdrawn (thanks to Manoj Nagpal for finding out about this, as well as posting about the present circular on twitter)
(2) The withdrawal can only be made for specific reason as noted in the PFRDA circular
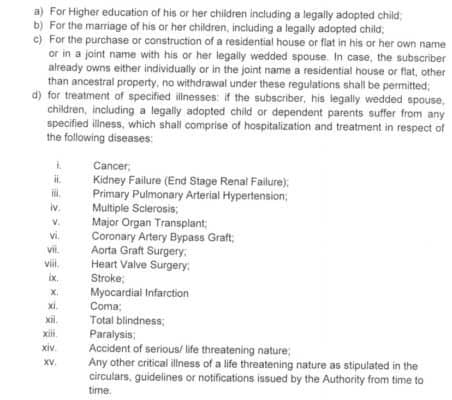
Twenty-five percent limit for points (a,b and c) is quite reasonable. Anybody which has seen the terms of a critical illness cover will immediately recognise the illnesses listed in (d). For such an illness a much larger limit would be helpful, especially if withdrawals have been made earlier.
(3) only 3 partial withdrawals are possible and each withdrawal must be spaced 5 years apart. For the subsequent withdrawal, only incremental contributions made after the earlier withdrawal will be eligible for redemption. I think the 25% rule will also apply to incremental contributions! (Awful!)
(4) The withdrawal application by the subscriber (for reasons a,b,c) or relatives in case illness as stated in (d) should be submitted to the point-of-presence POP office. They will have to verify the authenticity of the claim and forward it to CRA. For (a,b,c) processing time is 3 days. For (d) – illness same day. After that there should be a direct bank credit within 3 days.
Opinion: Just how useful is this feature? Not very. In fact, I would use this as another reason to not join the NPS or shift from EPF.
The EPF subscriber has much more control over the entire corpus arising from his/her contributions. Stay away from the NPS.