Last Updated on December 29, 2021 at 5:31 pm
“I fail to see the need for debt funds when we can invest in safe options like EPF, VPF, PPF, SSY, insurance policies, FD, and RDs. Some are even tax-free!” The Franklin debt fund closure naturally triggers questions such as this. The problem is, every choice has a risk. When we seek safety we mean safety from only one kind of risk and that may prove to be riskier!
Even a casual attempt at using a retirement calculator would tell you that the investment amount is a big number and this a return greater than inflation! Running to the safety of fixed income would only make things worse.
Every option available has a risk. FDs and RDs require tax to be paid as per slab each year with gradually falling interest rates which can only get worse in future (reinvestment risk).
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Insurance policies are too expensive leaving little for investing elsewhere. Remember a good amount of equity is necessary for any kind of chance against inflation.
Overnight funds are too conservative for long term goals and suffer the highest reinvestment risk: Overnight Mutual Funds also have risks! What investors need to know
Liquid funds are also too conservative for long term goals, also suffer from reinvestment risk and can be volatile in time likes these: Why Liquid funds and money market funds also fell in the last few days
If we skip all other debt funds and consider only gilt funds, actively managed gilt funds suffer from fund manager risk when they shift asset allocation bet gilts and non-gilts as per market conditions. They suffer from interest rate risk and are volatile.
10-year constant maturity gilt funds have little fund manager risk, the closest we have to a gilt index fund but are the most volatile and can frustrate buyers with long periods of poor returns.
Our good old PPF can only be used for 15Y-plus goals, cannot be redeemed from at will. Similar constraints also apply to EPF, VPF and SSY. “Why must I worry about lock-in? After all, the goal is for the long term, is it not?”
That is the problem. Use only these for the long term and you end will less purchasing power because of inflation. Use only a little equity and inflation will hit you again. Most people simply do not have the money to compensate for safety with higher investments.
As an example, Rs. 1000 invested at 9% (annualized) for 16 years would give you 3.6 times the investment. If you want the same benefit with safer 7% return, you will have to invest 32% more. If we include tax, it will only make things worse.
All well to say, I am going to avoid X or Y instrument and stick to safe FDs and RDs but there is always a cost. Now the following would make sense to only those who appreciate the benefits of asset allocation.
Most investors who are 35-plus today would have an EPF + PPF debt-heavy allocation for long-term goals. They have little chance of correcting (most do not wish to anyway) and it will affect the way they live after retirement.
The following illustration is for a young earner with not too much invested in EPF and can sooner than later get to an asset allocation of 50% equity and 50% fixed income for a long term goal like retirement.
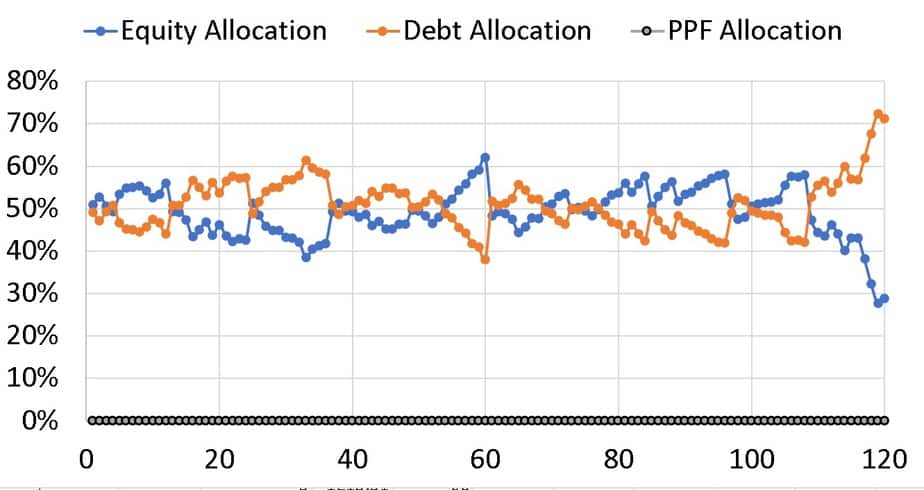
Consider a portfolio with 50% equity and 50% liquid fixed income. That is, say a gilt debt fund which one can redeem or invest in freely. If the portfolio is not rebalanced (asset allocation reset to 50:50) once a year it can drift like this. The first 120 months (10 years) movement is shown below.

The asset allocation can swing towards equity or debt both of which can increase the risk of not achieving our goals. With annual rebalancing, the swings are significantly lower.
Now with 50% equity and 50% PPF, rebalancing is not possible (at least not each year and not to the full extent).
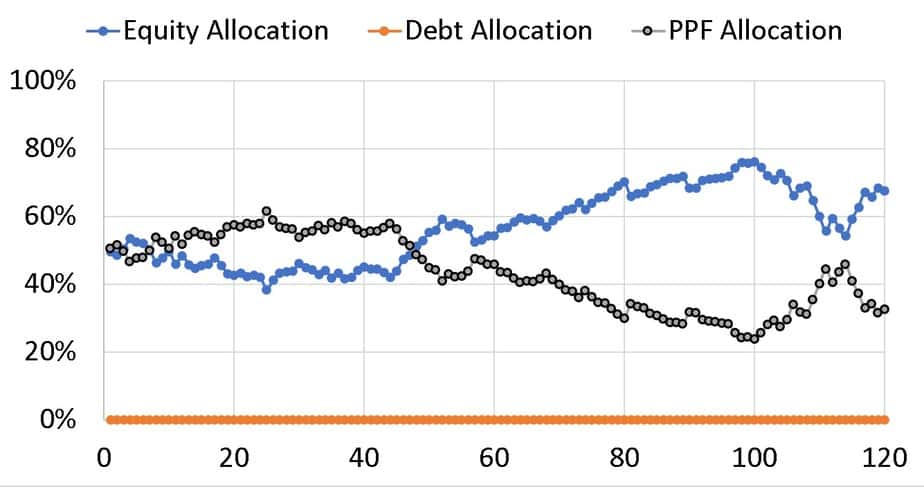
In the above example, 50% of equity can move close to 80% increasing portfolio risk. If one argues the amount can be removed to say an SB account and then put back in, then they have realised the value of liquid debt!
This is 50% equity, 25% PPF and 25% long-term gilts with annual rebalancing for the same return sequence. Notice the reduction in deviations. The rebalancing here is done only bet the equity and gilt component.
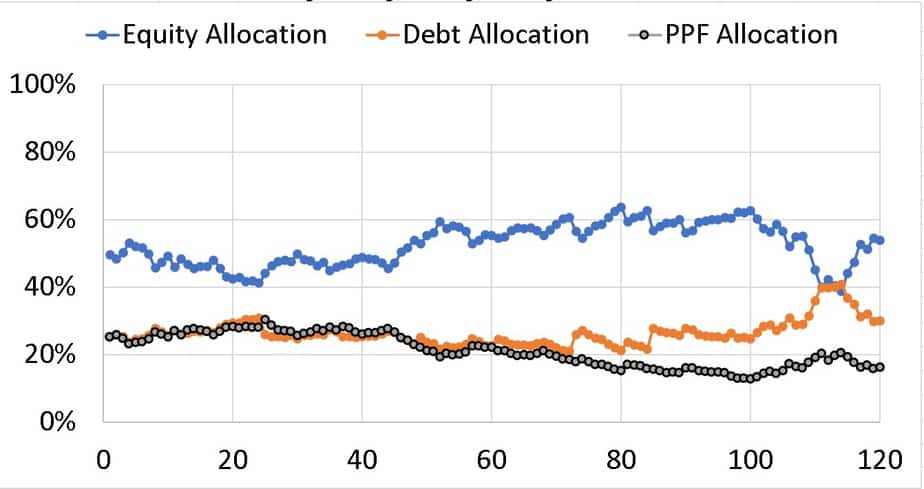
The reason for choosing gilts and not just an SB account or liquid fund is their volatility, they providing selling and buying opportunities like equity and times could coincide with the buying and selling opportunity in equity (as observed from asset allocation variations). This would lower risk.
What should young investors do?
- Do not lock your money into bonds and deposits
- Do not maximise PPF or VPF without looking at your asset allocation. You may forever destroy your ability to beat inflation and reach your desired target corpus and increase portfolio risk if equity exposure is reasonable.
- Have room for liquid fixed income in your portfolio. If scared of debt funds and arbitrage funds (which also have bonds) use long term gilts. Instead of worrying about their volatility, exploit it to reduce portfolio risk.
There is always a risk in every option. That is why there is no best option. Like every successful marriage, comprise is the key. Which risks can I accept so that the investment amount is reasonable, will keep portfolio risk at manageable levels and will take me close to my goal with minimal maintenance. The answer to this question is the holy grail of investing and varies from person to person!